

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Astrophotography Tracker Market Hits $163.5M in 2025, 9.72% CAGR
By pmarketresearch, 2026-09-17
Unlocking the Celestial Market: Strategic Insights from the 2026 Worldwide Star Tracker for Astrophotography Report
The night sky is no longer solely the domain of professional observatories. A democratization of astrophotography has transformed stargazing into a sophisticated hobby and a distinct commercial sector. As we move through 2026, understanding the trajectory of the Worldwide Star Tracker for Astrophotography Market is critical for stakeholders looking to align their strategies with celestial trends. Our latest market research, the Worldwide Star Tracker for Astrophotography Market Study, offers a comprehensive roadmap for navigating this expanding universe.
This report serves as an essential intelligence tool for decision-makers. It is not merely a collection of numbers but a strategic narrative explaining how technological innovation, consumer behavior, and competitive dynamics are converging to drive growth. For businesses operating in or adjacent to this sector, the insights contained herein are vital for capital allocation, product development, and geographic expansion plans throughout the forecast period.
Market Trajectory and Magnitudes
The financial outlook for the star tracker sector presents a compelling case for investment and growth. Our analysis tracks revenue trends from a historical base year of 2025 extending into the forecast horizon through 2032. The market has demonstrated consistent resilience and expansion, evolving from a niche interest into a recognized component of the broader imaging technology landscape.
Historical data reflects a steady climb in revenue generation. Starting from a baseline in 2020, the market has seen progressive annual growth, culminating in significant valuations by 2025. This momentum is projected to accelerate as we move beyond the current year. The forecast period indicates a robust upward trajectory, with valuations expected to scale significantly by the end of the decade. This growth is underpinned by a Compound Annual Growth Rate (CAGR) that signals strong sustained demand over the long term.
Such macroeconomic indicators suggest that the barrier to entry for high-quality astrophotography is lowering while the perceived value of these tools is rising. The infusion of capital into this sector suggests that the market is moving past early adoption phases into a stage of broader commercialization. Stakeholders who recognize this inflection point can position themselves to capture value before the market reaches saturation.
Segmentation and Structural Opportunities
To truly leverage this market potential, one must understand the structural composition of the industry. Our research deconstructs the market across multiple dimensions, revealing where value is being generated and where inefficiencies might exist.
The product landscape is categorized by mechanical and technological distinctions. We examine the performance and demand dynamics of portable units compared to more robust mounting solutions. The demand for compact, travel-friendly equipment continues to shape design priorities, while specific niche segments cater to users requiring specialized payload capacities. Understanding the revenue contribution of each product type allows manufacturers to optimize their portfolio mix according to shifting consumer preferences.
Worldwide Star Tracker for Astrophotography Market
Geographically, the consumption of astrophotography equipment is distributed across key global regions. Our analysis highlights the varying maturity levels of these markets. Some regions demonstrate established dominance driven by hobbyist density and disposable income, while emerging regions show promise based on growing astronomical communities and digital connectivity. Strategic players must differentiate their go-to-market strategies based on these regional idiosyncrasies rather than applying a uniform global approach.
Applications further define the market segments. From wide-field nightscape photography to deep space imaging and educational research, each use case commands different technical specifications and price points. The report details how these applications drive demand for specific features, such as tracking precision, payload capacity, and integration with digital imaging systems. By isolating these application drivers, companies can tailor their marketing messages and technical roadmaps to the specific needs of their target user bases.
Competitive Landscape and Corporate Intelligence
The competitive environment in the star tracker market is characterized by a mix of established optics manufacturers and specialized innovators. Our report provides a granular analysis of key companies that define the current market structure. These entities compete on dimensions of precision, portability, software integration, and price.
Major players such as iOptron and Sky-Watcher continue to influence the market with dedicated series designed for wide-field and deep-sky imaging. Their products often set the standard for features like WiFi control and payload capacity. Meanwhile, companies like Benro and Move Shoot Move are pushing the boundaries of smartphone integration and ultra-compact design, catering to the mobile-first astrophotographer. The presence of specialized manufacturers like Fornax Mounts and Vixen indicates a sustained demand for high-precision, mechanical reliability without relying on traditional gear drives.
Other significant entities, including NyxTech and Omegon, offer alternative approaches ranging from DIY kits to compact motorized solutions, ensuring that the market remains accessible to varying budget levels. This diversity in product offerings creates a fragmented yet vibrant ecosystem. The report analyzes the strategic positioning of these firms, noting how they differentiate themselves in a crowded field.
Competitive concentration is a notable factor. The market exhibits a level of consolidation where a core group of firms commands a significant share of revenue. However, the remaining share is distributed among numerous regional and niche players, suggesting opportunities for disruption. The report includes a detailed assessment of market concentration metrics, allowing investors to gauge the risk of market dominance versus the potential for new entrants to gain traction.
Industry Dynamics and Technological Drivers
Beyond static segmentation, the market is influenced by dynamic forces that are reshaping the operational environment. One of the primary challenges in consumer astrophotography remains the setup complexity, specifically regarding polar alignment. Our analysis highlights how recent product developments are addressing this bottleneck. Manufacturers are increasingly integrating smartphone applications, laser pointers, and enhanced alignment scopes to reduce the technical barrier for users. This shift from manual precision to assisted automation is a key driver of adoption among casual users.
On the regulatory and standards front, consumer star trackers generally operate under standard electronics safety and electromagnetic compatibility guidelines. While specific industry standards for amateur mounts are not rigidly defined beyond manufacturer quality controls, the emphasis on reliability is growing. This is evident in the broader context of the industry, where certifications and quality management systems are becoming more prevalent, even among consumer-focused goods.
Recent corporate activities also signal shifts in the broader ecosystem. For instance, expansions in manufacturing capabilities and new product line launches within the satellite and space sector often have spillover effects or indicate technological cross-pollination that can eventually benefit consumer-grade tracking technology. These developments remind stakeholders that the supply chain and technological landscape are interconnected with the wider aerospace and electronics industries.
Standardization in control interfaces is another trend. The move towards app-based control reduces reliance on traditional hardware interfaces, aligning star trackers with the broader Internet of Things (IoT) trends in consumer electronics. This convergence suggests that future iterations of these devices will likely prioritize seamless digital integration, firmware updates, and ecosystem compatibility.
Strategic Implications for 2026 Decisions
For executives and analysts, the value of this report lies in its actionable intelligence. The data provided allows for scenario planning in several critical areas. First, product development teams can use the segmentation data to identify which form factors and technical features are gaining traction. If the data indicates a surge in demand for lightweight equatorial mounts over traditional portable trackers, R&D budgets can be reallocated accordingly.
Second, geographic strategy is clarified. Knowing which regions are driving growth helps sales and distribution teams prioritize logistics, marketing spend, and partnerships. Ignoring high-growth regions or over-investing in stagnant ones can be costly; this report provides the metrics needed to avoid such pitfalls.
Third, competitive positioning is sharpened. By understanding the market concentration and the specific strengths of key competitors, companies can identify white spaces. Whether it is through pricing strategy, feature differentiation, or supply chain resilience, the report outlines the battlefield upon which companies are competing.
Furthermore, the forecast period extends to 2032, offering a long-term view that is essential for capital-intensive decisions. Infrastructure investments, facility expansions, and long-term supply contracts require visibility beyond the current fiscal year. The projected growth rates and market size evolutions provide the necessary confidence to commit resources to long-term initiatives.
Conclusion and Access to Full Intelligence
The Worldwide Star Tracker for Astrophotography Market is at a dynamic juncture. The combination of technological maturation, growing consumer interest in astronomy, and evolving competitive strategies creates a complex environment that requires careful navigation. Our research provides the depth required to understand these layers.
Astronomical Telescope Market
This article has summarized the strategic context and high-level market dynamics to establish the value of the comprehensive study. However, the true power of this intelligence lies in the detailed data tables, specific revenue breakdowns, and granular competitive profiles contained in the full report. To make informed decisions in 2026 and beyond, stakeholders need access to the complete dataset.
We invite industry leaders, investors, and analysts to review the full Worldwide Star Tracker for Astrophotography Market Research. By accessing the full document, you will gain the specific insights needed to drive your strategy forward, ensuring you remain aligned with the trajectory of this growing market.
For detailed analysis of this topic, please visit the official page: Worldwide Star Tracker for Astrophotography Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hitch Lock Market to Hit $18.4 Million by 2032; 4.15% CAGR Forecast (2026-2032)
By pmarketresearch, 2026-09-17
The Hitch Lock Market in 2026: Strategic Intelligence for Towing Security & Revenue Growth
Executive Summary: Why Strategic Depth Matters Now
The global hitch lock market has matured into a highly engineered, security-driven segment where product differentiation, distribution reach, and regulatory alignment determine competitive advantage. As towing volumes stabilize, fleet operations scale, and aftermarket security expectations rise, 2026 represents a decisive year for manufacturers, aftermarket distributors, and mobility-focused enterprises. PW Consulting’s latest market research delivers a structured, decision-ready view of how this landscape is evolving and where value is being created.
This study is designed as a strategic preview. It demonstrates the analytical rigor behind our latest Hitch Lock Market report, highlights the operational and competitive dynamics shaping 2026, and shows exactly how procurement, product, and go-to-market teams can translate market intelligence into actionable decisions. Core segmentation figures, regional revenue splits, and company-level performance breakdowns are reserved for the full report, because precise allocation data should inform investment choices—not simply be summarized.
Market Trajectory: What the Numbers Reveal About the Next Cycle
Over the 2020–2025 historical window, the hitch lock market expanded from approximately $10.25 million to $13.85 million, reflecting steady demand growth supported by trailer usage, towing accessory adoption, and an increasing emphasis on equipment security. The forecast period from 2026 through 2032 extends this momentum, with the market projected to reach $18.4 million by 2032.
At the center of this trajectory is a forecasted compound annual growth rate of 4.15% across the 2026–2032 period. That rate signals more than linear expansion. It indicates a market where volume growth, product mix evolution, and security upgrades are working together, but also where competitive intensity and margin pressure are likely to increase. For decision-makers, the strategic question is no longer whether the market is growing. It is where growth is concentrating, which product architectures are capturing share, and how upstream cost volatility reshapes pricing and sourcing strategies.
The full report unpacks these dynamics with a detailed forecast model, scenario analysis, and time-phased growth breakdowns that connect historical performance to forward-looking demand drivers. The preview below shows the framework, not the final allocation tables.
Report Scope: Operational Intelligence Built for 2026 Planning
This research is structured to support practical business decisions rather than abstract market commentary. The complete study integrates market sizing, segmentation logic, competitive benchmarking, and demand-side context into a single decision framework. Key operational components include:
Hitch Lock Market
- Historical performance analysis covering 2020 through 2025, enabling year-over-year trend interpretation and baseline validation for forward planning
- A 2026–2032 forecast architecture that maps anticipated revenue progression, regime shifts, and growth inflection points across the market lifecycle
- A structured segmentation review examining product-type dynamics and application-side demand behavior without exposing the full allocation detail in this preview
- Regional demand context that frames where volume is concentrated and which geographic markets warrant separate channel or sourcing strategies
- Competitive profiling of leading manufacturers and security-focused brands, including positioning, product philosophy, and recent strategic moves
- Industry dynamics analysis covering raw material exposure, regulatory influence, distribution trends, and aftermarket security preferences
The report also includes actionable takeaways for product planning, inventory strategy, channel expansion, and competitive response. Rather than presenting isolated statistics, the study is organized to help leadership answer questions such as which product categories justify further engineering investment, how distribution footprint changes affect addressable demand, and where security differentiation can support price realization.
Demand Architecture: Application and Product-Type Dynamics
Hitch lock demand is shaped by two interconnected forces: the vehicles and trailers that require protection, and the mechanical designs that define fit, durability, and user experience. In application terms, the market reflects a clear dependence on tow vehicles and trailers, with both categories contributing materially to overall consumption. Their relative importance is not just a volume story; it also influences product standards, installation expectations, and the security credentials buyers demand.
On the product side, the market spans multiple hitch lock architectures, each serving different installation environments and end-user preferences. Bent pin, flush pin, and threaded pin solutions all occupy distinct positions in the value chain, balancing ease of use, corrosion resistance, tamper resistance, and compatibility with receiver systems. As a result, the product mix is not uniform across customers or channels. Instead, it reflects a broader trend in which buyers increasingly evaluate hitch locks as part of an integrated towing security solution rather than as replaceable commodity hardware.
The full report details how these product and application categories interact with pricing, channel mix, and regional demand patterns. Because those breakdowns are central to portfolio planning and sales targeting, they are presented in full within the licensed study rather than summarized here.
Geographic Context: Where Demand Is Concentrated and Why It Matters
Regional demand distribution plays a critical role in shaping production planning, inventory positioning, and channel strategy. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each present different towing ecosystems, aftermarket maturity levels, and security expectations. As a result, a single global growth narrative can obscure important local differences in product requirements, competitive intensity, and distribution efficiency.
The report uses regional context to help clients assess where scale advantages matter most, where localized product configurations are needed, and where channel partnerships may accelerate penetration. Since regional revenue allocation and market share distribution are key inputs for expansion planning, those specifics are reserved for the complete market model. This ensures that strategic conclusions are grounded in the full dataset rather than in partial approximations.
Trailer Hitch Market
Competitive Landscape: Scale, Security, and Strategic Differentiation
The hitch lock market is characterized by meaningful concentration at the top, with leading players competing on manufacturing integrity, security performance, distribution breadth, and brand trust. The study’s competitive concentration metrics indicate a market where a relatively small group of established manufacturers accounts for a substantial share of total revenue, while specialized security brands continue to compete through engineering-led design and targeted product innovation.
Several companies define the current competitive rhythm:
- Proven Industries focuses on American-made heavy-duty trailer coupler locks, hitch locks, and security solutions with grinder-proof designs and lifetime warranty coverage, emphasizing RV, horse, and utility trailer applications.
- AMPLock, operating from Drummondville, Canada, produces CNC-machined heavy-duty hitch locks, coupler locks, and trailer security products using ductile iron and stainless steel, supported by patented key control systems.
- Altor Locks, based in Sterling, Virginia, takes an engineering-led approach with patented power tool-resistant ICON series trailer coupler locks, gooseneck locks, and hitch security solutions aimed at high-value assets.
- CURT Manufacturing is recognized as a leading USA-made trailer hitch and towing accessory manufacturer, offering a broad line of hitch locks, coupler locks, and receiver locks across multiple towing applications.
- Master Lock provides a wide range of weather-resistant trailer coupler locks, hitch pin locks, and towing security products designed for universal fit across multiple coupler and receiver sizes.
- BOLT Lock advances one-key lock technology solutions, including hitch receiver locks and trailer coupler locks, with an emphasis on convenient keyed-alike towing security.
Recent company-level activity reinforces how dynamic this space has become. In April 2026, AMPLock expanded heavy-duty trailer lock distribution across the United States, introducing over 20 custom-fit configurations for hitch, coupler, and related applications. That move reflects a broader push toward fitment specificity and channel reach. In August 2025, Altor Locks expanded its ICON product line with a new Gooseneck Trailer Lock, debuting at the NATDA Trailer Show with shipments beginning in Fall 2025. This launch highlights the continuing importance of specialized towing configurations and tool-resistant security design.
The complete report places these developments within a broader competitive mapping framework, connecting product launches, distribution expansion, and brand positioning to market share dynamics and strategic implications. That level of detail is essential for benchmarking and competitive response planning, which is why the full competitive analysis is provided in the licensed publication.
Market Dynamics: Material Volatility, Regulation, and Security Expectations
Beyond product and competition, the hitch lock market is influenced by upstream cost conditions and regulatory context. Raw material price volatility remains a significant operational concern. Industry data from March 2026 indicates that steel and alloy price fluctuations affect production costs, with nearly 41% of manufacturers reporting challenges linked to material cost instability. For hitch lock producers, this creates tension between engineering durability, manufacturing efficiency, and price competitiveness. Sourcing strategy, inventory timing, and product-grade selection become increasingly important as a result.
On the regulatory side, cargo securement expectations continue to shape how towing hardware is specified and evaluated. FMCSA cargo securement rules reference manufacturing standards for tiedowns, including welded steel chain specifications associated with the National Association of Chain Manufacturers. While hitch locks operate in a closely related but distinct part of the towing security ecosystem, the broader regulatory environment still matters because it influences buyer expectations, specification practices, and the perceived credibility of robust metal-based security hardware.
These dynamics are not peripheral. They influence cost structures, product specifications, and the value proposition that manufacturers can communicate to downstream buyers. The full report integrates these factors into a market dynamics assessment that links input-cost exposure, regulatory awareness, and end-user security demand to strategic planning assumptions.
Strategic Takeaways for 2026 Decision-Making
For executives, product leaders, and commercial teams, the hitch lock market in 2026 is best approached as a security-conscious, engineering-sensitive, and distribution-dependent growth environment. Several strategic priorities emerge from the broader direction of the market:
- Portfolio decisions should account for product-type fit and application-specific demand rather than treating hitch locks as interchangeable aftermarket items
- Material cost volatility requires disciplined sourcing, forecasting, and product-grade planning to protect margins without compromising durability claims
- Distribution expansion and custom-fit configuration strategies can materially affect reach, especially in markets where compatibility and installation ease drive purchase decisions
- Security differentiation, including tool-resistant design and strong warranty or fitment messaging, continues to support brand positioning in a concentrated market
- Regional demand variation should inform channel allocation, inventory planning, and localized product strategy rather than a single global rollout assumption
These priorities are directional by design. The full report translates them into quantified market sizing, segmentation breakdowns, forecast detail, and competitive benchmarking that can be directly applied to planning cycles.
Why the Full Report Is the Next Strategic Step
This preview demonstrates the analytical approach behind PW Consulting’s Hitch Lock Market research, but it intentionally leaves out the segment-level allocations, regional revenue splits, and detailed company comparisons that make the study actionable. The complete report provides the supporting model, the segmentation logic, the forecast architecture, and the competitive intelligence necessary to turn high-level trends into executable strategy.
For organizations evaluating product investment, channel expansion, procurement strategy, or competitive positioning in the towing security space, the full study offers a structured foundation for 2026 decision-making and beyond. The market is moving at a measured but consistent pace, and the companies that succeed will be those that combine security credibility with disciplined commercial execution. PW Consulting’s complete Hitch Lock Market report is designed to help leadership make those choices with greater confidence.
For detailed analysis of this topic, please visit the official page: Hitch Lock Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Cancel for Any Reason Travel Insurance Market to Hit $2.04B by 2032 at 13.23% CAGR
By pmarketresearch, 2026-09-17
Worldwide Cancel for Any Reason Travel Insurance Market: Strategic Intelligence for 2026 Decision-Making
The global travel insurance landscape has entered a period of structural transformation, driven by heightened traveler sensitivity to uncertainty and the rapid commercialization of flexible coverage products. At the center of this shift is the Cancel for Any Reason (CFAR) Travel Insurance market, a niche segment that has evolved from a marginal rider into a strategic differentiator for insurers, aggregators, and travel service providers. Our newly released Worldwide Cancel for Any Reason Travel Insurance Market study maps the segment across a 2020-2025 historical baseline and a 2026-2032 forecast horizon, translating complex demand signals, distribution realignments, and competitive maneuvers into an executive-ready intelligence framework. For leadership teams navigating product positioning, channel partnerships, or capital allocation in 2026, this research offers a disciplined lens on where value is concentrating and how the segment is likely to mature.
The macroeconomic trajectory captured in the study underscores why CFAR has moved from a peripheral insurance feature to a core strategic consideration. The overall market reached an estimated valuation of USD 852.4 Million in 2025, reflecting a compound trajectory from USD 280.45 Million in 2020. Over the forecast period extending to 2032, the segment is projected to follow a CAGR of 13.23%, with revenue scaling toward a multi-billion-dollar threshold as traveler expectations for granularity and flexibility continue to reshape purchase behavior. The analytical architecture of the study captures this expansion through layered segmentation by region, distribution channel, and traveler type, while also examining market concentration indicators that reveal how competitive power is distributed across leading providers. Crucially, the research goes beyond top-line sizing. It dissects the operational mechanics of CFAR adoption, the structural constraints imposed by regulatory environments, and the strategic implications for insurers balancing underwriting discipline against the growing appetite for unparalleled cancellation flexibility.
Report Scope and Operational Content
A market study earns its stature not through headline figures but through its capacity to inform real-world decisions. This research is structured to serve product strategists, distribution leaders, and competitive intelligence teams who require more than surface-level sizing. The report integrates historical progression analysis with forward-looking scenario modeling, allowing readers to assess momentum vectors rather than static snapshots. Coverage includes a detailed segmentation review that isolates how CFAR demand behaves across geographic markets, how it flows through distinct commercial channels, and how it maps to traveler personas ranging from individual leisure buyers to corporate travel programs and group travel arrangements.
The study is built around actionable analytical modules designed to support planning cycles in 2026. These include baseline market estimation, growth-rate derivation, and segmentation-level performance mapping that identifies where volume and value are accumulating. It also examines the structural factors that shape adoption, such as purchase-timing sensitivity, reimbursement design, and the interaction between standard trip cancellation benefits and CFAR upgrades. By tracing these mechanics, the report provides a practical foundation for assessing product design choices, pricing architecture, and channel strategy without reducing the segment to a single aggregate number.
Travel Insurance Market
Equally important is the report’s treatment of market structure and competitive behavior. Rather than presenting a simple roster of participants, the analysis situates each major provider within the broader ecosystem, highlighting how reimbursement ratios, add-on design, waiting period configurations, and regional eligibility rules shape competitive positioning. This allows executives to evaluate not just who is active in the market, but how different players are attempting to convert flexibility into durable share. For teams assessing partnership opportunities, benchmarking exercises, or entry strategies, this framing provides the kind of comparative clarity that supports informed judgment rather than speculative positioning.
Macro Trajectory and Demand Signals
The strength of the CFAR market is best understood as a function of both structural demand and episodic volatility. Over the historical period, the segment expanded through a combination of broader travel insurance penetration and a measurable shift toward coverage that gives travelers a discretionary exit option. That momentum accelerated in early 2026, when interest in Cancel for Any Reason coverage rose sharply in response to geopolitical instability and operational uncertainty. Industry reporting from March 2026 noted a significant uptick in buyer attention, reinforcing the pattern that CFAR demand often intensifies when travelers perceive higher unpredictability in itineraries, booking conditions, or broader travel environments.
This dynamic creates a strategic paradox for insurers and distributors. CFAR is not merely a product feature; it is a behavioral hedge that travelers increasingly value when plan certainty declines. At the same time, its design introduces complexity around timing, eligibility, and reimbursement structure. Most plans require purchase within a limited window after the initial trip deposit, require that the policyholder insure 100% of nonrefundable trip costs, and generally mandate cancellation at least 48 hours before departure. Reimbursement levels typically range from 50% to 75% of prepaid nonrefundable trip costs, with select offerings offering higher reimbursement ceilings. These parameters make CFAR highly attractive to risk-aware travelers, but they also mean that product design, communication clarity, and distribution timing become decisive factors in conversion.
Industry data suggests that approximately 10% of travel insurance plans purchased include CFAR coverage, a figure that reflects both the segment’s specialized appeal and its still-niche status within the broader travel insurance purchase base. That proportion matters because it signals room for expansion while also indicating that CFAR remains sensitive to price perception, plan bundling, and traveler awareness. The study interprets this trajectory not as a simple growth story, but as a demand curve shaped by consumer preference for flexibility, the influence of external disruption, and the way distribution channels translate that preference into completed purchases.
Segmentation Architecture and Strategic Implications
One of the most valuable contributions of the research is its segmentation logic. CFAR performance cannot be understood in isolation; it is mediated by where travelers buy coverage, who they are, and how regional market conditions influence product acceptance. The study maps these dimensions to reveal where demand is concentrated and where commercial opportunity may be underleveraged.
From a regional perspective, the analysis examines how mature versus emerging markets differ in their appetite for flexibility-driven coverage. Mature markets tend to exhibit higher baseline insurance penetration and more developed consumer familiarity with ancillary travel protections, while other regions may show faster relative growth as travel activity expands and buyers become more intentional about cancellation risk. The report avoids oversimplified regional generalizations. Instead, it evaluates market structure in a way that helps strategists determine whether CFAR should be positioned as a premium differentiator, a conversion enhancer, or a bundled protection element depending on local demand characteristics.
Distribution channel analysis is equally critical. The way CFAR is sold shapes both visibility and trust. Direct online channels and insurtech platforms play an outsized role in making flexible coverage discoverable, while travel agencies and online travel agencies contribute volume through trip-linked purchase pathways. Traditional insurance brokers continue to serve segments where personalized advisory interaction influences product selection. The study evaluates how these channels differ in their ability to educate buyers on CFAR’s terms, manage purchase timing, and position reimbursement expectations. For operators, this analysis supports decisions about where to invest in consumer-facing explanation, where to optimize embedment into booking flows, and where broker-led guidance may create premiumization opportunities.
Traveler type segmentation further sharpens the strategic view. Individual and leisure travelers often drive discretionary CFAR purchases because they are more directly exposed to personal trip disruption risk. Business and corporate travelers represent a distinct value pool, where cancellation flexibility may intersect with policy administration, duty-of-care considerations, and travel program compliance. Group and family travelers introduce different purchasing dynamics, often balancing total trip cost coverage against the convenience of a shared policy. By separating these personas, the research enables more precise messaging, channel targeting, and product configuration decisions.
Competitive Landscape and Product Differentiation
CFAR is a segment where differentiation is often subtle but commercially decisive. The study profiles leading participants and evaluates how each uses reimbursement design, add-on structure, waiting periods, and eligibility rules to create competitive posture. Several U.S.-based providers anchor the market, and each illustrates a different approach to converting flexibility into perceived value.
Allianz Travel Insurance offers CFAR or a Cancel Anytime upgrade on select plans such as OneTrip Prime and OneTrip Premier, with reimbursement reaching up to 80% of prepaid nonrefundable trip costs and the ability to cancel as late as the day of departure under certain configurations. That positioning reflects a strategy centered on premium reimbursement ceilings and late-window flexibility. Seven Corners provides CFAR as an optional add-on on plans including Trip Protection Basic, with reimbursement up to 75% and a reputation for short waiting periods, which can be an important conversion factor for time-sensitive buyers. Travel Insured International includes optional CFAR benefits on its Worldwide Trip Protector plans, reimbursing up to 75% for cancellations not otherwise covered and emphasizing broad trip protection integration.
IMG offers CFAR as an optional add-on on iTravelInsured plans such as Travel LX, Travel SE, and Choice, with reimbursement up to 75%, though availability is not uniform across all states. Trawick International has pursued a distinct product-led strategy by embedding CFAR within its Safe Travels plan family, including the Safe Travels AnyReason plan, which provides 75% reimbursement without an additional fee. That design is notable because it reduces the friction typically associated with add-on pricing and reframes CFAR as an integrated plan attribute rather than a separate purchase decision. WorldTrips offers CFAR coverage on its Atlas Journey series, aiming to give travelers a path to recover nonrefundable trip costs for any reason, while Travelex Insurance Services incorporates CFAR options and positions them around value and emergency coverage breadth.
Travel Guard, part of AIG, offers an optional Cancel for Any Reason add-on that reimburses a percentage of nonrefundable trip costs, reflecting the scale and brand visibility that large travel insurance franchises bring to the segment. World Nomads provides an optional CFAR upgrade on Explorer and Epic plans for U.S. residents, with eligibility limitations in certain jurisdictions. Generali Global Assistance offers optional CFAR on Premium plans with reimbursement up to 75% of nonrefundable trip costs, aligning flexibility with higher-tier plan positioning. Tin Leg has been identified among competitive CFAR providers for 2026, suggesting ongoing entry and repositioning activity in the market. Faye is noted for CFAR coverage linked to non-medical evacuation benefits, illustrating how some providers associate flexible cancellation with broader protection narratives.
These profiles are not presented as isolated product summaries. They are used to interpret how reimbursement ceilings, fee structures, timing rules, and regional eligibility constraints influence competitive advantage. The report also tracks structural developments that alter market expectations, including product launches that reset baseline assumptions. For example, Trawick International’s 2024 launch of Safe Travels AnyReason introduced an industry-first plan with embedded CFAR offering 75% reimbursement without an additional fee, a move that signaled how product architecture could be used to lower purchase friction. More recently, industry attention to rising CFAR interest in early 2026 has reinforced the idea that demand for flexible cancellation is responsive to broader uncertainty cycles.
Regulatory and Structural Dynamics
Any credible CFAR strategy must contend with the regulatory and operational constraints that shape offerable terms. The study dedicates significant attention to the forces that determine what can be sold, how it can be presented, and where limitations apply. CFAR coverage is subject to time-sensitive purchase windows, requirements that 100% of nonrefundable trip costs be insured, and cancellation thresholds that commonly require action at least 48 hours before departure. These operational rules influence both consumer behavior and product design, making them essential considerations for anyone evaluating conversion pathways or underwriting exposure.
Regulatory nuance is equally important. In certain jurisdictions, CFAR benefits are treated with specific interpretive guidance rather than as standard insurance coverage. For instance, New York DFS Insurance Circular Letter No. 4 from 2020 clarified that CFAR benefits do not technically qualify as insurance in the traditional sense and provided guidelines for offering them as incidental benefits or within standalone contracts. As a result, CFAR may not be available under standard policy configurations in some environments, and in practical terms, certain providers do not offer CFAR to New York residents under specific plans. These state-level and jurisdictional distinctions create fragmented availability and can affect both market sizing and competitive reach.
From a market structure standpoint, the study also examines concentration indicators that reveal how consolidated the competitive base is. The research captures market concentration metrics including a CR3 of 38.45% and a CR5 of 52.3%, signaling that a limited group of leading participants accounts for a substantial share of the segment while still leaving meaningful space for specialty providers, insurtech entrants, and distribution-led differentiation. This concentration picture matters because it helps leaders gauge how crowded the core is, where differentiation is most needed, and whether share gains are likely to come from product innovation, channel leverage, or brand trust.
Strategic Takeaways for 2026 Decision-Making
For executives planning around 2026, the report’s central value lies in converting market momentum into decision-grade insight. The CFAR segment is expanding in a context where traveler demand for flexibility is no longer marginal, but it remains sensitive to purchase timing, reimbursement framing, and regulatory boundaries. That combination means the winners are unlikely to be determined solely by who offers CFAR, but by who can make it understandable, accessible, and commercially coherent within the purchase journey.
Several strategic implications emerge from the analysis. First, product design and communication clarity are becoming competitive levers in their own right. Because CFAR depends on narrow purchase windows and specific eligibility conditions, providers and distributors that can reduce confusion and align messaging with real traveler decision points may capture disproportionate conversion advantage. Second, channel strategy deserves deliberate attention. Online direct and insurtech pathways can strengthen visibility and speed to purchase, while agency and OTA touchpoints can reinforce trust and trip-linked relevance. The optimal mix depends on the target traveler type and the regional market being addressed.
Third, reimbursement architecture is not merely a marketing feature; it is a structural differentiator. Higher reimbursement ceilings, waived add-on fees, and short waiting periods each address different sources of buyer resistance. Providers that align these elements with their broader plan portfolio can shape perceived value in ways that extend beyond price competition. Fourth, regulatory heterogeneity must be managed carefully. Jurisdiction-specific availability and treatment of CFAR create both constraints and opportunities, especially for organizations operating across multiple states or planning multi-market expansion. Understanding where CFAR can be offered, how it can be presented, and which configurations are permissible is essential to avoiding compliance friction and identifying under-served pockets of demand.
Finally, the report is intended to help leadership teams look beyond cyclical spikes and assess the durability of demand. The recent rise in interest is consistent with the pattern that CFAR becomes more attractive when uncertainty increases, but the longer-term opportunity depends on whether flexible cancellation can be normalized as an expected element of travel protection rather than a crisis-driven purchase. The study provides the context to evaluate that transition, including how market concentration, distribution dynamics, and product innovation interact to determine whether CFAR remains a premium add-on or becomes a more widely embedded purchase expectation.
Worldwide Cancel for Any Reason Travel Insurance Market
Why This Research Matters Now
Market intelligence is most valuable when it enables decisions that are both timely and precise. The Worldwide Cancel for Any Reason Travel Insurance Market study is designed to support that standard by combining historical context, forward-looking growth modeling, segmentation analysis, and competitive profiling in a single analytical framework. It gives decision-makers a structured view of how the segment has evolved, how it is currently contested, and where strategic attention is likely to produce the greatest return in 2026 and beyond.
At the same time, the study intentionally preserves depth that cannot be fully captured in a summary format. Segmentation-level performance, regional market behavior, channel-specific flow patterns, and the full competitive comparison across providers are developed in detail within the complete report. These components are essential for teams that need to benchmark against specific peers, evaluate channel investments, or build product strategies with a clear view of where value is concentrating. The overview presented here is intended to establish the strategic contours and demonstrate the research’s analytical rigor, while inviting a deeper engagement with the full dataset and interpretive commentary.
For organizations seeking to act on the CFAR opportunity with discipline rather than speculation, this research provides the foundation. It clarifies the market’s growth logic, identifies the forces shaping demand, and frames the competitive and regulatory realities that will influence execution. The complete report extends that foundation into the level of detail required for operational planning, making it a strategic reference for executives, product leaders, and market analysts who need to navigate a segment that is expanding quickly, differentiating sharply, and becoming increasingly central to the future of travel insurance.
For detailed analysis of this topic, please visit the official page: Worldwide Cancel for Any Reason Travel Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Flow Field Plate Market to Hit $15.9B by 2032, 28.45% CAGR
By pmarketresearch, 2026-09-17
Beyond the Hydrogen Horizon: Strategic Intelligence in the Global Flow Field Plate Market through 2032
The global energy transition has entered a phase of decisive industrial scaling. Nowhere is this trajectory more evident than in the flow field plate sector, a critical subsystem governing fluid distribution, electrical conductivity, and mechanical durability across fuel cell stacks, electrolyzers, and stationary power installations. As capital allocation shifts from laboratory validation to gigawatt-scale manufacturing, decision-makers require more than directional trends. They need granular, forward-looking intelligence that maps technology roadmaps, supply chain inflection points, and competitive positioning against a rapidly compressing investment window. Our newly released Worldwide Flow Field Plate Market research delivers precisely that. Built on a rigorous methodology spanning historical tracking from 2020 through the base year of 2025, and projecting forward across a 2026 to 2032 forecast horizon, this study equips executives, procurement leaders, and strategic planners with the analytical leverage required to navigate a market undergoing structural acceleration.
In 2026, the operational landscape for hydrogen technologies and electrochemical power systems is no longer defined by theoretical potential. It is defined by cost curves, manufacturing throughput, and supply chain resilience. The flow field plate has evolved from a passive component into a performance bottleneck and a differentiation lever. Material selection, surface engineering, coating architectures, and production tolerances directly dictate stack longevity, power density, and levelized cost of energy. Companies that treat this segment as a commodity procurement category are rapidly ceding ground to competitors who recognize it as a strategic capability node. Our research is structured to close that awareness gap, translating macroeconomic momentum into actionable market architecture.
The Macro Trajectory: Decoding the Growth Inflection
The market's historical trajectory tells a story of compounding adoption. Over the past half-decade, revenue generation has escalated from a foundational baseline in 2020 to a substantially expanded operational footprint by 2025. That momentum does not plateau; it compounds. Our forecast model projects the global market to surpass the mid-three-billion-dollar threshold in 2026, followed by sustained expansion that pushes total industry revenue well beyond the fifteen-billion-dollar mark by the close of the 2032 projection window. At the core of this expansion sits a compound annual growth rate of 28.45 percent, a figure that reflects not merely cyclical demand but a structural realignment in how clean energy infrastructure is manufactured, deployed, and scaled.
Such growth is not distributed uniformly across time, geography, or application. It concentrates in segments where performance requirements intersect with manufacturing readiness, regulatory tailwinds, and capital deployment velocity. For strategic planners, the implication is clear: headline figures are useful for boardroom context, but segment-level dynamics dictate where capacity should be allocated, where supplier partnerships should be forged, and where technical roadmaps should be prioritized. Our report dissects these dynamics without reducing them to static snapshots, instead presenting them as interdependent variables that shift as technology maturation curves cross commercial adoption thresholds.
The strategic value of this market intelligence lies in its ability to separate signal from noise. Raw material constraints, coating specifications, throughput limitations, and regional trade policy adjustments all exert measurable pressure on cost structures and delivery timelines. By mapping these pressures against demand trajectories, the study enables organizations to anticipate supply-demand mismatches before they become operational liabilities. Executives can evaluate whether to lock in long-term feedstock agreements, diversify supplier bases, or invest in proprietary forming and etching capabilities. The data does not prescribe a single path; it illuminates the trade-offs embedded in each strategic choice.
What the Report Delivers: Operational Intelligence, Not Just Forecasts
A market study earns its place on an executive dashboard only when it translates into operational decision-making. Our Worldwide Flow Field Plate Market research is engineered around that standard. The publication moves systematically through the architecture of the industry, beginning with a comprehensive segmentation framework that isolates material type, application domain, and regional deployment patterns. Rather than presenting these splits as isolated tables, the analysis contextualizes them within technology adoption lifecycles, manufacturing scalability constraints, and end-use performance requirements.
The material segment analysis examines how metallic, graphite, and composite flow field plates compete across different performance and cost envelopes. Each category carries distinct implications for conductivity, corrosion resistance, manufacturing complexity, and supply chain dependencies. The application analysis traces how demand differentiates across fuel cell electric vehicles, stationary power generation, and electrolyzer deployments, highlighting where volume scaling, durability thresholds, and integration requirements diverge. Regional analysis maps where manufacturing capacity, end-market demand, and policy support converge, enabling readers to assess localization strategies, tariff exposure, and logistics optimization opportunities without relying on superficial geographic generalizations.
Beyond segmentation, the report delivers a deep operational review of production methodologies and technology roadmaps. Photochemical etching, progressive die forming, compression molding, high-velocity forming, and advanced coating architectures are evaluated against throughput, precision, capital intensity, and scalability. This technical grounding matters because manufacturing process selection directly influences unit economics, quality consistency, and the ability to meet emerging performance targets set by government research programs and industry consortia. Decision-makers gain a structured basis for evaluating whether to outsource, co-develop, or internalize critical production capabilities.
The study also integrates competitive benchmarking, supplier capability mapping, and recent market movements that signal shifting industry momentum. New product introductions, capacity expansions, strategic partnerships, and technology demonstrations are analyzed not as isolated headlines but as indicators of where capital and engineering effort are being concentrated. By connecting these developments to broader supply chain and regulatory dynamics, the report provides a living map of competitive positioning that remains relevant as the market matures.
Competitive Architecture: Navigating a Fragmented but Consolidating Field
The flow field plate ecosystem is characterized by a blend of specialized manufacturers, integrated fuel cell developers, and industrial players expanding into hydrogen-adjacent production. Market concentration metrics indicate that the top three players account for 38.4 percent of industry revenue, while the top five collectively capture 52.65 percent. This concentration profile signals a market that is broad enough to accommodate diverse entrants yet structured enough that scale, process know-how, and customer integration relationships confer meaningful defensive advantages.
Worldwide Bipolar Plate Fuel Cell Market
Players such as Switzer and Precision Micro have built reputations around photochemical machining and chemical etching, offering high-precision metallic bipolar and flow field plates that serve electrolyzer, hydrogen generation, and fuel cell applications across prototyping and high-volume production. Their capabilities emphasize design flexibility and tight geometric control, attributes that matter when flow distribution and pressure drop management directly influence stack efficiency. Fuel Cell Store and Ensinger address the graphite segment with customizable plate designs and scalable production pathways, supporting electrochemical devices that prioritize different trade-offs between weight, conductivity, and corrosion behavior. In China, TMNetch focuses on photochemical etching for metallic plates, emphasizing durability and energy efficiency in fuel cell environments, while Interplex leverages corrosion-resistant stainless steel formulations with PVD coatings to extend operational lifespan in demanding PEM applications.
On the industrial scaling frontier, companies like Dana Incorporated and EKPO Fuel Cell Technologies bring high-speed forming, conductive coatings, and integrated sealing architectures to metallic bipolar plate production, aligning their output with high-volume PEM fuel cell and electrolyzer requirements. Dana's recent product introduction for high-density electrolyzers, which pairs titanium or steel substrates with advanced forming, conductive coating, and molded elastomer sealing, illustrates how incremental engineering refinements target both power density and cost reduction simultaneously. Schunk Group contributes compression-molded graphite bipolar plates with integrated flow fields, offering single-plate and redox flow cell solutions that support energy storage and fuel cell architectures. Ballard Power Systems continues to advance flexible graphite bipolar plate lines and next-generation manufacturing capacity, supported by policy-aligned funding initiatives that underscore the strategic importance of domestic production readiness.
Worldwide Flow Field Plate Market
The competitive landscape also includes operators scaling proprietary manufacturing technologies. Cell Impact's high-velocity forming approach and large-scale production facilities position it to serve fuel cell and electrolyzer demand at volume, reinforced by partnerships that combine forming with welding technology for high-volume bipolar flow plate production. SITEC and Precision Resource extend the field further by covering coil-to-installation manufacturing pathways and specialized metal forming for zero-emission vehicles and green hydrogen production. Taken together, these players illustrate a market where competitive advantage is increasingly defined by process engineering, coating expertise, integration support, and the ability to move from prototype validation to reliable series production.
Market Dynamics and the Forces Reshaping Supply and Demand
No forward-looking strategy is complete without a clear understanding of the forces that can accelerate, delay, or redirect market growth. Raw material considerations remain foundational. Graphite-based flow field plates depend on high-purity feedstock, while composite variants typically carry substantial graphite loading combined with polymer binders, creating a material architecture that balances conductivity with mechanical and chemical resilience. Metallic plates, by contrast, commonly rely on stainless steel or titanium substrates, with precision steel strip in narrow thickness ranges enabling complex flow field forming. These material realities link the flow field plate market directly to upstream commodity dynamics, specialty coating availability, and precision metallurgy supply chains.
Regulatory and policy frameworks exert equally directional influence. Support for bipolar plate manufacturing advancement continues through government-backed programs that fund next-generation production lines and technology development initiatives. Technical targets for PEM fuel cell bipolar plates increasingly emphasize electrical conductivity, areal specific resistance, and cost-per-kilowatt thresholds at volume. These targets are not abstract benchmarks; they function as design constraints that shape R&D priorities, supplier qualification criteria, and procurement negotiations. Organizations that internalize these performance and cost targets early can align their engineering roadmaps with the standards that will govern future market access.
Trade policy and regional cost dynamics add another layer of strategic complexity. Tariff adjustments affecting metallic feedstocks and specialty coatings have already altered unit input costs for manufacturers operating in affected markets. Such shifts influence supplier selection, regional sourcing strategies, and the economic calculus behind domestic versus imported production. Meanwhile, recent capacity expansions and technology demonstrations signal where the industry is placing its bets. Large-scale production line construction for flow plate and vanadium flow battery-related applications, modular pilot plants for rapid and cost-effective bipolar plate production, and partnership agreements targeting high-volume manufacturing installation all point to an ecosystem moving from fragmented experimentation toward coordinated commercial scaling.
For corporate strategy teams, these dynamics create both risk and optionality. Supply chain diversification, long-term coating and feedstock agreements, localization of critical process steps, and selective vertical integration all become viable responses depending on an organization's risk tolerance, capital position, and customer commitments. The report's value lies in helping leaders evaluate those responses against a structured map of market forces rather than reacting to isolated events after the fact.
Why 2026 Is the Strategic Inflection Point
2026 represents more than another forecast year. It marks the point at which early adoption momentum transitions into industrial scaling, where procurement decisions begin to lock in capabilities for the remainder of the decade, and where competitive positioning becomes increasingly difficult to reverse. The flow field plate market is expanding at a pace that rewards organizations with clear technology roadmaps, disciplined supplier strategies, and a realistic understanding of where manufacturing complexity can be absorbed internally versus where it should be managed through partnerships.
The research does not merely project growth; it structures the decision environment around the variables that actually determine outcomes. Which material class aligns with your performance requirements and cost targets? Where does your application mix concentrate, and how does that shape volume commitments? Which manufacturing processes offer the best path to precision, throughput, and scalability for your specific product architecture? How do recent product launches, capacity expansions, and partnership announcements change the competitive baseline you are operating against? These are the questions our study is designed to answer with analytical rigor rather than directional intuition.
Executives who engage with this intelligence early gain a measurable advantage in opportunity prioritization, risk mitigation, and capital deployment timing. They can distinguish between temporary demand spikes and durable structural growth, between capability claims and proven production readiness, and between regional opportunities that justify localization investment and those that remain better served through established supply channels. In a market moving at a 28.45 percent compound annual growth rate toward a 2032 revenue trajectory that redefines the scale of hydrogen and electrochemical infrastructure, strategic latency carries real cost.
Closing the Intelligence Gap: Access the Full Study
The macro trajectory, segmentation architecture, competitive mappings, and dynamic force analyses summarized here provide a substantive preview of the strategic landscape. They establish the analytical foundation and demonstrate the depth of methodology embedded in the full publication. Yet the most consequential details, the segment-level dimensions, the regional deployment patterns, the application-specific volume dynamics, and the supplier-level capability comparisons that inform precise go-to-market and procurement decisions, are intentionally held within the complete report.
This is not a limitation of the preview; it is the design of a strategic intelligence product. Executive briefings establish context and credibility. Detailed market data, scenario-ready segmentation, and granular competitive assessments enable execution. Organizations that require precise figures for capacity planning, supplier negotiation, technology investment justification, and market entry evaluation will find the complete Worldwide Flow Field Plate Market research built for exactly that purpose. The full study translates directional confidence into operational precision, giving strategic teams the evidence base required to commit capital, align engineering roadmaps, and position competitively across the 2026 to 2032 horizon.
Access the complete market research to secure the full segmentation data, regional deployment intelligence, application-level demand analysis, and competitive benchmarking required to move from strategic awareness to decisive action. In a market scaling this rapidly, the difference between informed positioning and reactive adaptation is access to the right intelligence at the right time.
For detailed analysis of this topic, please visit the official page: Worldwide Flow Field Plate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Hydrogen Valve Market Hits $154.8M in 2025, 11.85% CAGR to $340.25M by 2032
By pmarketresearch, 2026-09-17
Navigating the Hydrogen Pressure Reduction Landscape: Strategic Insights for 2026 and Beyond
The global transition toward low-carbon energy systems has placed hydrogen at the center of industrial, mobility, and storage infrastructure planning. Within this accelerating ecosystem, the pressure reducing valve for hydrogen bottle market has emerged as a critical enabler of safe, efficient, and compliant gas handling. As organizations align their capital allocation and product development Roadmaps for 2026, understanding the trajectory, competitive architecture, and regulatory undercurrents of this segment is no longer optional. This introduction to our latest Pressure Reducing Valve for Hydrogen Bottle Market research outlines the strategic value decision-makers can extract from a data-rich, forward-looking analysis designed specifically for enterprise planning.
Historical performance through 2025 demonstrates sustained expansion, with market revenue climbing from 82.45 million USD in 2020 to 154.8 million USD at the close of 2025. The momentum carries decisively into the forecast window. Our modeling projects the market to reach 173.27 million USD in 2026, accelerating toward 340.25 million USD by 2032, underpinned by a compound annual growth rate of 11.85 percent. These figures reflect more than incremental demand; they signal a structural shift in how high-pressure hydrogen is stored, transported, and deployed across fuel cell mobility, industrial gas storage, and refueling infrastructure. For executives evaluating market entry, capacity expansion, or technology partnerships in 2026, this trajectory provides a foundational baseline against which investment thresholds and risk parameters can be calibrated.
Yet macro growth alone does not dictate strategy. The real leverage lies in understanding how demand fractures across applications, how regional adoption patterns shape supply chain dynamics, and how product architecture preferences evolve under regulatory and material cost pressures. Our research deliberately maps these intersections without reducing them to static snapshots. Instead, it unpacks the operational implications behind each demand layer, enabling engineering, procurement, and commercial teams to align product specifications, inventory positioning, and go-to-market sequencing with actual deployment cadence.
Market Dynamics Driving 2026 Decision-Making
Several converging forces are reshaping the competitive and operational environment for hydrogen pressure reducing valves. Regulatory frameworks are tightening around high-pressure gas handling, directly influencing design validation, certification pathways, and time-to-market. The ISO 10297:2024 standard for cylinder valves was updated to include additional hydrogen compatibility testing requirements for pressure reducing valves, raising the bar for material selection, sealing integrity, and fatigue performance. Simultaneously, the EU Pressure Equipment Directive mandates that hydrogen pressure reducing valves meet Category III or IV classification for high-pressure service, adding compliance complexity for manufacturers serving European distribution channels.
Material economics introduce another layer of strategic consideration. Nickel alloy and stainless steel 316L prices increased 8 percent year-over-year in the third quarter of 2025, directly raising production costs for hydrogen pressure reducing valves. For original equipment manufacturers and valve suppliers, this shift affects margin structures, pricing architecture, and supplier negotiation strategies. Companies that approach 2026 without a clear view of material cost trajectories risk underpricing critical components or overcommitting to specifications that erode profitability at scale.
Technological differentiation is equally pronounced. The market is not monolithic; demand is distributed across product architectures that vary in complexity, application fit, and value proposition. Single-stage designs continue to hold a substantial share of the market, reflecting their suitability for straightforward pressure reduction in established hydrogen bottle workflows. Two-stage and multi-stage configurations serve more specialized use cases, where staged pressure management, leakage mitigation, or controlled delivery profiles justify additional engineering investment. Understanding which architecture aligns with which deployment scenario is essential for portfolio planning and for avoiding the common trap of over-engineering solutions that customers do not require.
Application-side demand further complicates the picture. Fuel cell vehicles, hydrogen refueling stations, industrial gas storage, and other emerging use cases each impose distinct operating conditions, certification expectations, and procurement rhythms. Refueling infrastructure, for example, often prioritizes durability under frequent cycling and rapid response, while industrial gas storage may emphasize purity, long-duration stability, and compatibility with batch handling protocols. Our research dissects these application drivers to help organizations map product capability to the precise operational demands that will shape procurement decisions in 2026.
Competitive Architecture and Strategic Positioning
The competitive landscape is populated by established industrial valve manufacturers and specialized gas-handling suppliers, each leveraging distinct footholds in engineering heritage, geographic reach, and application expertise. Emerson Electric Co. offers pressure reducing valves for high-pressure hydrogen cylinders used in industrial and energy applications, with its Tescom division specializing in high-pressure hydrogen pressure reducing valves for cylinder and bottle service. Parker Hannifin Corporation supplies hydrogen-compatible pressure reducing valves for cylinder and bottle applications in mobility and energy sectors, reinforcing its cross-industry fluid control presence. Swagelok Company manufactures high-purity pressure reducing valves for hydrogen bottle systems in laboratory and industrial gas handling, appealing to environments where contamination control and repeatability are paramount.
Rotarex S.A. provides cylinder pressure regulators and reducing valves specifically engineered for hydrogen storage and distribution, and in October 2025 it released a hydrogen-specific cylinder pressure reducing valve series for fuel cell and industrial gas applications, signaling targeted product expansion. GCE Group develops pressure reducing valves for hydrogen cylinders used in welding, industrial, and fuel cell applications; in September 2025, the company updated its hydrogen cylinder valve and regulator catalog with new pressure reducing models for high-pressure service. Swagelok also gained visibility in August 2025 by showcasing hydrogen pressure reducing valves at ACHEMA 2025 for industrial gas and energy markets, reinforcing its engagement with European industrial buyers. Ham-Let Group offers hydrogen-compatible pressure reducing valves for high-pressure gas cylinder applications, while Circor International, Inc. produces pressure regulators and reducing valves for hydrogen cylinder and bottle markets.
Market concentration reflects a moderately consolidated environment. The combined share of the top three competitors stands at 42.5 percent, while the top five reach 58.7 percent. This structure suggests that scale, brand trust, and compliance documentation carry substantial weight in procurement decisions, particularly among larger infrastructure projects and regulated industrial end users. At the same time, the remaining share dispersion leaves room for specialized entrants, regional suppliers, and application-focused innovators to compete on performance, lead time, and tailored technical support. For 2026 planning, this means competitive strategy cannot rely solely on incumbency; it must respond to differentiation vectors that matter to specific buyer segments.
What This Research Delivers for Enterprise Planning
Our Pressure Reducing Valve for Hydrogen Bottle Market research is built to translate market complexity into executable intelligence. Rather than offering a high-level overview, the report is structured around operational decision points that engineering, sales, supply chain, and corporate development teams confront when preparing for 2026 and the years that follow.
Bottle Valve Market
- Historical baseline and forecast trajectory with a detailed view of revenue progression from 2020 through 2032, enabling scenario planning around demand pacing and investment timing.
- Product architecture segmentation that clarifies how single-stage, two-stage, and multi-stage solutions are distributed across the market, helping teams align product roadmaps with real demand concentration.
- Application-driven demand analysis covering fuel cell vehicles, hydrogen refueling stations, industrial gas storage, and other use cases, supporting targeted positioning and channel strategy.
- Regional market structure insights that frame where demand is developing, how procurement patterns differ, and what localization or distribution considerations may influence execution.
- Competitive profiling of leading manufacturers, including headquarters, core offerings, and market focus, to inform benchmarking, partnership evaluation, and threat assessment.
- Recent corporate developments, such as new product launches, catalog updates, and trade show showcases, to track how competitors are reshaping their portfolios in near-real time.
- Regulatory and standards context, including hydrogen compatibility testing updates and pressure equipment classification requirements, to help teams anticipate compliance workload and design constraints.
- Material cost sensitivity analysis that connects alloy and stainless steel pricing movements to production economics, supporting margin planning and supplier strategy.
The report is designed for practical use. It helps product managers determine which performance specifications are genuinely differentiating versus merely table stakes. It assists procurement leaders in anticipating cost drivers and lead-time vulnerabilities tied to material markets and certification pipelines. It supports commercial teams in prioritizing geographies and applications where demand intensity and buyer readiness are most aligned with existing capabilities. And it gives corporate strategists a defensible basis for partnering, acquiring, or expanding into adjacent hydrogen handling components without relying on assumptions.
Why 2026 Is the Pivotal Year for Strategic Clarity
2026 represents a convergence point for several structural drivers. Hydrogen deployment is moving from pilot and early-commercial phases into more standardized operational environments, which means procurement criteria are becoming more rigorous, repeat ordering patterns are beginning to form, and compliance documentation is increasingly decisive in supplier selection. At the same time, product development cycles for pressure reducing valves are being tested by tighter standards, material cost volatility, and the need to serve multiple application archetypes without diluting manufacturing efficiency.
Organizations that enter 2026 with a clear view of demand distribution, competitive positioning, and regulatory exposure will be better equipped to sequence investments, manage risk, and capture share in a market that is expanding steadily but not uniformly. Those that rely on partial data or generic growth narratives risk misaligning product capabilities with buyer expectations, overcommitting to regions or applications with limited near-term pull, or underestimating the compliance and cost pressures that shape final procurement decisions.
The strategic value of this research lies in its ability to connect market scale with market mechanics. The headline trajectory, an 11.85 percent CAGR extending from 173.27 million USD in 2026 to 340.25 million USD by 2032, provides the macro signal. The segmentation, competitive profiles, regulatory frameworks, and recent product activity provide the operational context required to act on that signal. Together, they form a decision-ready foundation for evaluating where to compete, how to differentiate, and which execution risks deserve priority attention.
Turning Market Intelligence into Execution Advantage
For manufacturers, the immediate question is not whether hydrogen bottle pressure reduction demand is growing, but how to position product architecture, compliance readiness, and supply chain resilience to capture that growth profitably. For infrastructure developers and industrial end users, the question is how to specify valves that meet safety, purity, and durability expectations without overpaying for unnecessary complexity. For investors and corporate development teams, the question is where consolidation, specialization, or geographic expansion is most likely to create durable advantage in a market that is still maturing.
Answering these questions requires more than a top-line number. It requires a granular, structured view of how the market is composed, how competitors are moving, and how external factors are reshaping cost and compliance. Our research is built to supply that view, while preserving the detailed breakdowns that matter most when teams move from strategy to execution.
Begin the Strategic Deep Dive
This overview has outlined the market trajectory, the competitive and regulatory forces shaping 2026, and the operational content embedded in our full Pressure Reducing Valve for Hydrogen Bottle Market research. To access the complete segmentation detail, regional and application-level intelligence, competitive benchmarking, and scenario-ready forecast tables, download the full report. The macro story sets the direction; the full dataset equips your team to act on it with precision.
Pressure Reducing Valve for Hydrogen Bottle Market
For detailed analysis of this topic, please visit the official page: Pressure Reducing Valve for Hydrogen Bottle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Automotive Warehouse Logistics to Reach USD 171.25 Billion in 2025, Growing at 6.72% CAGR
By pmarketresearch, 2026-09-17
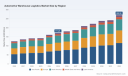
Global Automotive Warehouse Logistics Market: Strategic Intelligence for 2026 and Beyond
The automotive supply chain is currently navigating a period of unprecedented transformation. As manufacturers shift toward electric vehicle production, face evolving regulatory landscapes, and grapple with persistent labor constraints, the role of warehouse logistics has evolved from a backend support function to a critical strategic lever. Understanding the dynamics of this sector is no longer optional for stakeholders aiming to maintain competitiveness. PW Consulting presents this deep dive into the Worldwide Automotive Warehouse Logistics Market, designed to equip decision-makers with the foresight needed for the 2026 fiscal year and the decade ahead.
This analysis synthesizes comprehensive data spanning historical performance from 2020 through 2025 and extends robust forecasts through 2032. The objective is not merely to report numbers but to interpret the underlying forces driving value creation, risk mitigation, and operational efficiency within the global automotive logistics network.
Market Trajectory and Growth Projections
The financial arc of the automotive warehouse logistics sector demonstrates resilience and steady expansion despite macroeconomic volatility. Historical data indicates a consistent upward trend in revenue generation across the industry. Starting from a baseline in 2020, the market has navigated supply chain disruptions and recovery phases, culminating in a significant valuation by 2025. The momentum carried into the forecast period suggests sustained growth rather than a temporary spike.
Our research models project the market value to continue its ascent through 2032. The compound annual growth rate observed over the forecast horizon underscores the structural demand for specialized logistics services. This growth is not uniform; it is driven by specific shifts in manufacturing geography, vehicle complexity, and the increasing need for just-in-sequence delivery models. For enterprise leaders, this trajectory signals that investment in logistics infrastructure is aligned with long-term market expansion, offering a hedge against stagnation in other operational areas.
Segmentation Dynamics: Service Types and Component Categories
A superficial glance at market size misses the nuanced opportunities hidden within service segments. The revenue split across service types reveals where the industry's heavy lifting occurs. Inventory management and storage remain the dominant value drivers, reflecting the critical need for secure, organized holding spaces for high-value automotive assets. However, value-added services represent a substantial portion of the ecosystem, indicating a market trend toward partners who do more than store; they integrate, kit, and prepare components for immediate line-side consumption.
Distribution center operations also constitute a major pillar of the market, facilitating the movement of goods from central hubs to regional destinations. When examining component categories, the data highlights the primacy of spare parts logistics. The sheer volume and variety of parts required for maintenance and repair streams necessitate sophisticated warehousing strategies. Finished vehicle logistics form another critical segment, requiring specialized handling and transport coordination. Raw materials and components round out the triad, linking upstream manufacturing needs with downstream distribution capabilities.
Strategic allocation of resources should reflect these proportions. Organizations that prioritize capabilities in high-value segments while maintaining flexibility for component-specific requirements are better positioned to capture margin improvements. The disparity in segment sizes suggests that while volume lies in certain areas, value differentiation often comes from specialized handling and integration services.
Regional Distribution of Logistics Activity
Geography plays a defining role in logistics strategy. The Asia Pacific region stands out as a dominant hub of activity, reflecting the concentration of manufacturing capacity and vehicle production in this zone. This regional weight implies that logistics networks must be optimized for high-density throughput and cross-border coherence. Europe maintains a significant presence, driven by established OEM bases and stringent regulatory environments that shape logistics operations.
North America continues to represent a substantial share of the market, supported by a robust domestic vehicle production ecosystem and extensive distribution networks. Emerging regions, including the Middle East and Africa as well as Latin America, contribute to the global tally, offering growth potential for companies willing to invest in infrastructure development and local partnership models. Understanding the regional weight is essential for capacity planning. A logistics strategy that overlooks the dominance of certain regions may find itself misaligned with where the actual volume and value generation are occurring.
Competitive Landscape and Key Players
The market structure is characterized by a mix of global integrators and specialized logistics providers. The competitive landscape shows a concentration that suggests room for consolidation but also intense rivalry among top-tier players. Our analysis identifies the share held by the top three and top five companies, indicating that while large players dominate, a significant portion of the market remains distributed among specialized partners who compete on niche capabilities and regional expertise.
Intelligent Automatic Warehouse And Logistic Equipment Market
Leading Enterprise Profiles
Several key companies define the current operational standards and strategic directions of the sector. DHL Supply Chain, headquartered in Bonn, Germany, provides comprehensive contract warehousing and distribution solutions tailored for automotive parts and finished vehicles. Their portfolio includes specialized handling for EV components and just-in-sequence delivery, positioning them at the forefront of modern logistics requirements.
Kuehne + Nagel, based in Schindellegi, Switzerland, offers integrated automotive warehouse logistics with a strong focus on contract logistics and visibility platforms. Their emphasis on automation for OEMs and Tier suppliers highlights the industry shift toward digital transparency and automated handling. CEVA Logistics, operating from Marseille, France, specializes in customized contract warehousing and value-added services. Their strong expertise in finished vehicle logistics and parts distribution underscores the importance of end-to-end solutions that cover both new production and aftermarket flows.
DB Schenker, located in Essen, Germany, delivers land, air, ocean freight, and contract logistics services focused on automotive supply chains. Their ability to integrate warehousing with broader freight movements offers a holistic view of supply chain management. Ryder System, Inc., from Miami, USA, provides dedicated transportation, warehousing, and supply chain solutions with a significant automotive sector focus. Their capabilities in fleet management and parts distribution complement warehousing needs with transportation efficiency.
XPO Logistics, headquartered in Greenwich, USA, offers flexible warehousing, fulfillment, and less-than-truckload services supporting high-volume automotive parts and component logistics. Their flexibility appeals to manufacturers with fluctuating production schedules. DSV, based in Hedehusene, Denmark, provides global freight forwarding and contract logistics with automotive-specific warehousing and distribution capabilities, leveraging a massive network to serve complex requirements.
BLG LOGISTICS GROUP AG & Co. KG, in Bremen, Germany, acts as a specialist in automotive logistics including warehousing, vehicle processing, and technical services for OEMs. Their specialization allows for deep integration with manufacturer processes. Nippon Express Holdings, from Tokyo, Japan, offers integrated logistics solutions for automotive with an emphasis on Asia-Pacific warehousing and global parts supply chain management, crucial for bridging Eastern manufacturing with global markets. Finally, Penske Logistics, based in Reading, USA, delivers supply chain management and warehousing services optimized for automotive manufacturers and suppliers, focusing on operational excellence.
Recent Strategic Developments
Competitive moves in recent months signal where the industry is heading. In March 2026, DHL Supply Chain announced the rollout of the SVT Robotics SOFTBOT platform across its global warehouse network. This deployment aims for faster multi-robot integration supporting automotive and other sectors, demonstrating a clear commitment to accelerating automation adoption to overcome labor constraints.
Earlier, in July 2025, Nippon Yusen Kabushiki Kaisha (NYK) engaged in the joint development and full-scale implementation of an AI system with MTI and Grid. This system automates and optimizes car carrier allocation in vehicle logistics, highlighting how artificial intelligence is being deployed to solve specific allocation and efficiency problems in vehicle transport and warehousing coordination.
Worldwide Automotive Warehouse Logistics Market
Industry Dynamics Shaping 2026
Several external forces are compressing the timeline for logistics transformation. Regulatory changes are reshaping the fundamental economics of vehicle production and movement. In February 2026, the EPA finalized a rulemaking eliminating greenhouse gas standards for light-, medium-, and heavy-duty vehicles and engines. This shift alters the compliance landscape for manufacturers and, by extension, the logistics requirements for moving vehicles and parts that may have different certification profiles. Additionally, the NHTSA proposed revisions to CAFE standards on December 5, 2025, reducing the estimated light-duty fleet-wide fuel economy requirement. These regulatory adjustments influence vehicle mix and production volumes, directly impacting warehouse throughput needs.
Labor market conditions remain a critical pressure point. Labor and skills shortages rank as the second-biggest challenge in automotive manufacturing. This scarcity drives automation investment while constraining operations. For warehouse logistics providers, this means that solutions must increasingly rely on technology to mitigate headcount risks. The divide in automation adoption is stark: OEMs and Tier 1 suppliers are operating at adoption rates between 51% and 62%, while Tier 2 stands at 31% and Tier 3 at 23%. This gap suggests that downstream and upstream suppliers may face efficiency disparities that logistics partners must navigate through flexible handling and support services.
Supply chain pressures also persist. Ongoing issues include rising raw material costs and component shortages impacting automotive parts warehousing and distribution. These factors require logistics providers to maintain higher safety stocks or implement more sophisticated inventory turnover strategies to buffer against volatility. Infrastructure constraints and the need for smoother integration between physical storage and digital planning systems are becoming table stakes for service providers.
Strategic Implications for Decision Makers
For executives planning for 2026, the data points toward several actionable imperatives. First, the growth trajectory confirms that logistics is a value-creation center, not just a cost center. Investment in warehousing capabilities should be viewed through the lens of enabling production continuity and market responsiveness. Second, the segmentation data suggests that diversification of service offerings, particularly in value-added services, can insulate revenue streams from volatility in pure storage demand.
Third, the competitive landscape indicates that partnerships with providers who have proven automation roadmaps are essential. With labor shortages persisting and automation adoption varying by tier, logistics partners who can bridge this gap offer significant strategic advantage. The recent technology deployments by major players serve as benchmarks for what is achievable in terms of speed and integration.
Fourth, regional allocation of logistics resources should mirror the production geography. The heavy concentration in Asia Pacific requires dedicated attention to network resilience there, while North American and European operations must navigate specific regulatory and labor environments. Finally, the regulatory shifts regarding emissions and fuel economy standards will likely alter vehicle mix over time. Logistics strategies must remain agile enough to accommodate changes in vehicle type, size, and component composition as manufacturing priorities shift.
Conclusion and Research Utility
The Worldwide Automotive Warehouse Logistics Market is at an inflection point where scale meets sophistication. The projected growth through 2032 offers a backdrop of opportunity, but realizing value requires navigating a complex web of regional dynamics, technological adoption gaps, and regulatory changes. This report serves as a foundational tool for validating strategic assumptions and identifying high-potential areas for investment.
By integrating historical performance data with forward-looking analysis and competitor intelligence, stakeholders can move beyond generic market observations to precise, actionable strategies. The insights contained within this study are designed to support capital allocation, partnership selection, and operational planning in a volatile environment.
To access the complete dataset, detailed segmentation breakdowns, full competitor profiles, and the comprehensive forecast models referenced in this overview, please visit the PW Consulting report page. The full intelligence package provides the granular data necessary to finalize your 2026 strategic roadmap.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Warehouse Logistics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Epoxy Resin Market in Wind Energy to Hit $6,656.8M by 2032 at 7.45% CAGR
By pmarketresearch, 2026-09-17
Navigating Material Innovation and Market Volatility: The Strategic Imperative for Epoxy Resins in Wind Energy
The global transition toward renewable energy infrastructure is no longer a question of if, but how fast and at what material cost. As wind turbine blades grow larger and operational environments become more demanding, the performance requirements for structural adhesives, infusion systems, and protective coatings have intensified. For strategic decision-makers in the wind energy value chain, understanding the epoxy resin landscape is not merely a procurement exercise; it is a critical lever for managing risk, optimizing lifecycle costs, and securing supply chain resilience in a rapidly fragmenting trade environment.
Our latest publication, Worldwide Epoxy Resins in Wind Energy Market, offers a comprehensive, data-driven examination of this specialized segment. Drawing on historical performance from 2020 through 2025 and projecting market trajectories through 2032, this research translates macroeconomic shifts, regulatory interventions, and technological advancements into actionable intelligence. What follows is a strategic preview of the forces shaping this market and why a thorough, granular analysis is essential for enterprise planning in 2026 and beyond.
Worldwide Epoxy Resins in Wind Energy Market
A Market Defined by Scale, Steady Growth, and Structural Complexity
The aerospace-grade precision and marine-grade durability required in modern wind turbine blades place epoxy resins at the center of composite manufacturing. Over the past half-decade, the sector has demonstrated remarkable resilience, weathering raw material volatility, shifting trade policies, and evolving engineering specifications. Historical revenue tracking reveals a market that has consistently expanded in absolute terms, recovering swiftly from cyclical dips and accelerating as turbine manufacturers push toward longer rotor diameters and offshore deployments. Current baseline valuations place the market in the low billions of USD, with a forecast period extending to 2032 that outlines a compound annual growth rate in the mid-single digits.
This trajectory is not uniform. Growth is being pulled forward by blade manufacturing applications, where resin infusion, hand lay-up, and vacuum-assisted processes dominate. Secondary demand streams from structural bonding and surface protective coatings contribute meaningfully but operate under different pricing dynamics, regulatory exposures, and formulation constraints. The concentration of revenue among top-tier suppliers further shapes pricing power, negotiation leverage, and innovation pacing across the supply chain. With the top three players capturing a substantial share and the top five commanding a majority of market activity, competitive positioning requires more than benchmarking. It demands an understanding of how formulation leadership, geographic footprint, and OEM partnerships translate into sustained market share.
The report dissects these dynamics without reducing them to oversimplified aggregates. Readers gain access to base-year valuations, year-over-year growth patterns, and forward-looking revenue projections that map the pace of expansion across the forecast horizon. Critically, the analysis preserves the integrity of each revenue stream, allowing strategists to evaluate how material substitution cycles, turbine upsizing trends, and regional manufacturing shifts will redistribute demand rather than simply expand it.
Segmentation That Matters: Where Formulations, Geography, and End-Use Intersect
Epoxy resins deployed in wind energy are not interchangeable inputs. They vary in viscosity, curing kinetics, glass transition temperatures, toughness modifiers, and environmental resistance profiles. The market reflects this specialization through a clear stratification by resin type, spanning conventional liquid systems favored for their processing flexibility, higher-solid variants that cater to weight and curing efficiency targets, and an emerging cohort of bio-based and specialty resins designed to address sustainability mandates and end-of-life considerations. Each category carries distinct cost structures, performance trade-offs, and adoption timelines that directly influence procurement strategy and product roadmap decisions.
Geographic distribution of demand adds another layer of strategic complexity. Wind energy manufacturing and installation pipelines differ markedly by region, shaped by policy incentives, port infrastructure, OEM localization efforts, and the maturity of domestic composite material ecosystems. Asia Pacific, Europe, and North America each present unique thresholds for pricing sensitivity, supply reliability, and formulation customization. A nuanced reading of regional consumption patterns reveals where import dependency intersects with local production capacity, and where tariff exposure or logistical constraints could alter total landed costs over the next several years.
On the application side, blade manufacturing commands the largest share of resin expenditure because it represents the most material-intensive and performance-critical step in turbine assembly. Structural adhesives and surface protective coatings serve essential but more specialized roles, often requiring tailored formulations that balance mechanical strength with weatherability, chemical resistance, and ease of maintenance. The report maps these application channels in detail, highlighting how design specifications, blade length trajectories, and offshore servicing requirements continuously redefine material specifications and purchasing priorities.
Special Epoxy Resin for Wind Power Blades Market
Rather than presenting segmentation as static snapshots, the analysis tracks how these splits evolve under pressure from feedstock costs, recycling initiatives, and process innovations such as faster-curing resin systems and hybrid thermoplastic-epoxy architectures. This progression-oriented view is vital for companies that need to anticipate substitution risks, evaluate supplier diversification options, or align internal R&D pipelines with shifts in OEM specifications.
Competitive Arena: Formulation Leadership, Geopolitical Exposure, and Pace of Innovation
The competitive field in wind energy epoxy resins is concentrated among large, globally integrated chemical manufacturers and a complement of regional specialists with strong technical reputations in composite processing. Several North American incumbents have built deep account relationships through long-standing supply of infusion systems, hand lay-up materials, and tooling solutions tailored for large-scale rotor blades. Their competitive advantage rests on proven performance heritage, process compatibility across filament winding, resin transfer molding, and vacuum infusion, and the ability to support turbine OEMs through iterative blade design changes.
European participants bring differentiated technical narratives centered on weather resilience, mechanical stress tolerance, and specialized epoxy-hardener combinations engineered for fiber-reinforced composite structures. Switzerland-based suppliers contribute composite epoxy systems optimized for vacuum infusion, structural bonding, and post-manufacture repair or surface finishing, reinforcing the importance of total lifecycle support beyond initial blade fabrication. Meanwhile, producers across East and South Asia have expanded their relevance by supplying cost-competitive resin grades and, increasingly, specialty formulations that address regional demand patterns and recycling-oriented material development.
Recent corporate activity underscores how rapidly the competitive landscape can shift. One major North American supplier introduced a low-viscosity epoxy resin system aimed at accelerating curing cycles for very large blades, signaling a focus on throughput and production economics that directly resonates with blade manufacturers under pressure to scale output. Another prominent player advanced a thermoplastic-epoxy hybrid resin tailored for improved recyclability, aligning with growing OEM interest in circularity and end-of-life blade management. At the same time, pricing actions have reflected the reality of evolving trade policy: announcements of double-digit increases on epoxy resins followed the removal of certain imports from tariff exemption lists, altering supply cost expectations for downstream applications.
These developments illustrate a broader truth: competitive positioning in this market is not determined by resin volume alone. It is shaped by formulation leadership, speed of process adaptation, regulatory navigation, and the ability to partner with OEMs on both performance and sustainability goals. The report profiles the core companies shaping this arena, examining how their technical portfolios, geographic reach, and recent strategic moves position them relative to shifting demand patterns. Rather than provide a static roster, the analysis connects product launches, pricing actions, and partnership activity to the underlying market forces that will determine which suppliers retain or expand influence through 2032.
Trade Policy, Feedstock Economics, and the New Calculus of Cost Management
No strategic assessment of epoxy resins in wind energy can ignore the regulatory and input-cost environment that has redefined procurement risk in recent years. Raw material economics remain a dominant driver of production costs, with key feedstocks such as bisphenol A and epichlorohydrin accounting for a substantial portion of manufacturing expense. Price movements in these inputs can quickly cascade into resin pricing, particularly when coupled with regional supply imbalances or demand surges from wind energy composites.
The trade policy landscape has amplified this sensitivity. Regulatory decisions in major end markets have altered exemption statuses and exposed imports to reciprocal tariff structures, prompting domestic price adjustments and forcing supply chain reevaluations. Anti-dumping duties imposed by the European Union on epoxy resin imports from several Asian sourcing countries have created a distinctly uneven competitive field, while other sourcing origins have faced different duty treatments. In parallel, feedstock price dynamics have shown quarter-to-quarter volatility, with notable declines in North American bisphenol A pricing driven by ample Asian supply, juxtaposed against firm demand and elevated feedstock costs that lifted regional resin prices in Northeast Asia.
These factors make clear that cost management in wind energy epoxy procurement is no longer a matter of negotiating quarterly rates. It requires scenario planning around duty exposure, feedstock trajectory, and supplier concentration risk, as well as an understanding of how formulation adjustments might mitigate total cost of ownership even when per-kilogram prices rise. The report integrates these external pressures into its market outlook, enabling readers to interpret growth projections through the lens of real-world cost drivers rather than abstract demand curves.
What the Report Delivers for 2026 Decision-Making
Strategic planning in 2026 demands intelligence that connects market size with market mechanics. The Worldwide Epoxy Resins in Wind Energy Market study is structured to provide precisely that connection. Beyond headline valuations and growth rates, the report provides a detailed operational map of the segment, including the interplay between resin type, application channel, and regional demand patterns, all contextualized within the evolving tariff, feedstock, and sustainability environment.
Key deliverables designed to support executive and operational decision-making include:
- A forward-looking revenue model spanning the forecast horizon, anchored by historical baselines and calibrated to reflect the influence of turbine upsizing, offshore expansion, and material substitution trends.
- Segment-level analysis that separates resin categories, application types, and geographic markets without relying on overly simplified aggregates, allowing leaders to identify where growth concentration, pricing pressure, or substitution risk is most acute.
- Competitive profiling of core suppliers, examining formulation capabilities, process compatibility, geographic footprints, and recent product or pricing actions that signal shifting competitive strength.
- Market context on feedstock economics, regulatory changes, and trade policy that directly affect landed cost, procurement flexibility, and near-term pricing expectations.
- Critical concentration metrics that quantify how revenue is distributed among leading suppliers, helping organizations assess dependency risk, negotiation leverage, and supplier diversification priorities.
By weaving these components together, the report enables organizations to move beyond reactive procurement and toward proactive portfolio strategy. Whether the objective is to secure reliable supply for blade manufacturing programs, evaluate alternative resin architectures, anticipate the impact of duty regimes on sourcing decisions, or align R&D investments with OEM sustainability targets, the analysis is designed to reduce uncertainty and sharpen execution.
Conclusion: Turning Market Intelligence into Competitive Advantage
The epoxy resin segment serving wind energy is at an inflection point. Demand continues to be pulled upward by larger turbines, broader offshore deployment, and the relentless pursuit of composite performance. At the same time, the operating environment is increasingly defined by feedstock volatility, trade policy recalibration, and a competitive field in which formulation speed and circularity credentials are becoming as important as volume capacity. In such a landscape, decisions made without granular, forward-looking insight carry heightened risk of margin erosion, supply disruption, or missed innovation windows.
This research study provides the depth required to navigate that complexity. It offers a structured, evidence-based view of how the market has evolved, how it is likely to progress, and where the most consequential opportunities and vulnerabilities lie. For organizations seeking to convert market knowledge into competitive advantage in 2026, the complete analysis offers the granularity, scenario context, and strategic framing needed to act with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Epoxy Resins in Wind Energy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Recruitment Market Hits $38.1B in 2025, Projected 7.34% CAGR to $62.5B by 2032
By pmarketresearch, 2026-09-17
Global Talent Mobility: Strategic Imperatives in the International Recruitment Services Market Through 2032
The global talent landscape is undergoing a structural shift defined by cross-border mobility, regulatory tightening, and an accelerating demand for specialized human capital. As organizations scale operations internationally, the function of international recruitment has evolved from a transactional hiring support service to a strategic capability that directly influences market entry velocity, operational resilience, and long-term competitiveness. Our latest Worldwide International Recruitment Services Market research provides a comprehensive intelligence framework designed to help enterprise leaders navigate these intersecting forces with precision. This article outlines the strategic value of the study for 2026 decision-making, highlights the analytical architecture of the report, and maps the competitive and regulatory terrain that will shape procurement, partnership, and expansion strategies in the years ahead.
Macro Trajectory: Scale, Growth, and the Strategic Window of 2026-2032
The international recruitment services industry has demonstrated remarkable resilience and consistent expansion over the past half-decade. Evaluating the historical trajectory from 2020 through 2025 reveals a market that navigated macroeconomic volatility, shifting immigration policies, and supply chain disruptions without losing its fundamental growth momentum. Building on that foundation, the forecast period extending to 2032 points to a sustained upward curve, underpinned by structural labor imbalances, digital transformation across industries, and the continued globalization of high-value talent pools.
At the base year of 2025, the global market for international recruitment services reached an estimated valuation of approximately 38.1 billion USD, a notable increase from the 34.3 billion USD recorded in 2024 and a steady climb from the 33.1 billion USD registered in 2022. This progression reflects not only organic demand but also the maturation of compliance-driven recruitment models, the expansion of remote and hybrid cross-border work arrangements, and the strategic outsourcing of talent acquisition functions by multinational enterprises. The forecast period beginning in 2026 projects the market to advance to roughly 40.2 billion USD in the immediate year ahead, before accelerating toward the mid-40 billion USD range by 2027 and 2028. Over the full forecast horizon, the market is expected to reach approximately 62.5 billion USD by 2032, supported by a compound annual growth rate of 7.34 percent.
For enterprise strategists, this trajectory carries several implications. First, the scale of growth confirms that international recruitment is no longer a peripheral HR function but a substantial, independently viable market with its own pricing dynamics, supplier ecosystems, and contract structures. Second, the projected acceleration underscores the importance of proactive supplier evaluation and partnership architecture: organizations that enter the market with clearly defined talent requirements, compliance standards, and geographic priorities will be positioned to secure preferred access to high-demand talent segments. Third, the breadth of the forecast window provides ample horizon for long-cycle workforce planning, allowing executive teams to align capital allocation, geographic expansion roadmaps, and capability-building investments with a credible market growth baseline.
Analytical Architecture: What the Research Delivers to Decision-Makers
A robust market intelligence study must do more than report headline figures; it must translate quantitative baselines into actionable decision frameworks. This research is structured to give procurement leaders, HR executives, corporate development teams, and investment analysts a multi-dimensional view of the international recruitment landscape. The study is organized around several interconnected analytical pillars, each designed to surface practical insights rather than abstract observations.
- Market sizing and growth mapping: The report establishes a rigorous baseline for total market value across the historical window and projects forward through the forecast period. These figures are contextualized within demand drivers, supply-side capacity constraints, and the evolving pricing environment for cross-border talent placement.
- Service-type segmentation: The analysis disaggregates market activity across permanent placement, contractual and temporary staffing, executive search, and recruitment process outsourcing. By examining the structural preferences, contract lengths, and operational models associated with each service category, the study helps organizations match procurement strategies to their specific workforce needs and risk tolerance.
- Industry vertical mapping: Demand patterns are evaluated across key sectors, including information technology and telecommunications, healthcare and life sciences, manufacturing and engineering, financial services, and other verticals. The research highlights where talent scarcity is most acute, where compliance complexity is highest, and how vertical-specific hiring cycles influence supplier capacity and service design.
- Competitive and supplier evaluation: Profiles of leading international recruitment providers are presented with attention to geographic reach, service specialization, operational footprint, and strategic positioning. These assessments support vendor benchmarking, partnership due diligence, and the identification of suppliers capable of supporting multi-jurisdiction deployment.
- Regulatory and compliance environment: The report tracks policy shifts affecting international recruitment, including fee-charging restrictions, cross-border data handling requirements, and labor protection frameworks that influence engagement models, candidate experience, and contractual risk allocation.
- Strategic recommendations and scenario frameworks: Rather than leaving the data as a static snapshot, the study translates findings into guidance for market entry planning, supplier diversification, compliance readiness, and capability investments that align with anticipated demand curves.
Within these pillars, the research provides granular segmentation data, supplier-level benchmarking, and operational indicators that are essential for building defensible sourcing strategies. Because the full spectrum of segment-level estimates, regional intensity breakdowns, and supplier scoring matrices is detailed in the complete report, we encourage strategy and procurement teams to consult the full publication for the precise figures required to calibrate internal models and negotiation frameworks.
Competitive Landscape: The Leaders Shaping the Market
The international recruitment services market is characterized by a mix of global workforce giants, specialist recruitment firms, and consultative talent organizations that blend placement capabilities with leadership assessment and organizational advisory services. Market concentration remains moderate, with the top three providers collectively accounting for a share that reflects a competitive, fragmented landscape rather than a consolidated monopoly. This structure creates both opportunity and complexity for buyers: there is ample supplier choice and specialized expertise available, but it also demands disciplined evaluation to ensure alignment with compliance standards, geographic coverage, and service-level expectations.
Adecco Group, headquartered in Switzerland, operates across more than 60 countries and provides temporary, permanent, and contract staffing solutions with a pronounced focus on international placements spanning IT, engineering, finance, and healthcare. Its scale and cross-industry reach make it a central reference point for organizations seeking broad geographic coverage and multi-vertical capacity. Randstad, based in the Netherlands, delivers global recruitment, staffing, and HR services with emphasis on international talent acquisition, temporary agency work, and workforce solutions across more than 39 countries. Its model underscores the importance of integrated workforce services that extend beyond individual placements to broader labor market participation.
ManpowerGroup, rooted in the United States, delivers workforce solutions including international recruitment, staffing, and talent management for permanent, temporary, and project-based roles in over 80 countries. Its breadth of operational presence supports enterprises with complex, multi-region staffing requirements and project-driven mobilization needs. Hays plc, a United Kingdom-based specialist, focuses on permanent and temporary specialist recruitment with international reach in sectors such as IT, construction, finance, and engineering across 33 countries. Its specialization-oriented model is relevant for organizations that prioritize domain expertise and sector-specific candidate pipelines.
Robert Half, also headquartered in the United States, concentrates on international recruitment for finance, accounting, IT, and administrative roles across numerous countries. Its vertical focus illustrates how specialized recruitment can command premium positioning when candidate profiles, credential verification, and regulatory compliance intersect. Korn Ferry, based in the United States, provides executive search and international talent acquisition services integrated with organizational consulting and leadership assessment, positioning the firm at the intersection of human capital strategy and senior-level mobility.
Additional players reinforce the competitive diversity of the market. Allegis Group, headquartered in the United States, offers staffing and recruitment solutions with significant international capabilities, particularly in engineering, IT, and professional services. Kelly Services, also United States-based, delivers temporary, permanent, and outsourced staffing with international recruitment support across various industries, reflecting the enduring relevance of flexible staffing models in global operations. Michael Page, headquartered in the United Kingdom, specializes in mid-to-senior level international recruitment in finance, marketing, engineering, and other professional sectors, highlighting the demand for experienced talent that can drive operational and strategic execution across borders.
Worldwide Job Search Recruitment Services Market
For enterprise buyers, this competitive mosaic is not merely a list of vendors; it is a sourcing architecture to be navigated strategically. The right supplier mix depends on the organization's geographic footprint, the seniority mix of required talent, the degree of compliance sensitivity in target markets, and the need for integrated workforce solutions versus discrete placement engagements. The full report provides a comparative evaluation framework that supports supplier selection, contract structuring, and partnership governance.
Regulatory and Operational Dynamics: Compliance as a Strategic Differentiator
The international recruitment market does not operate in a policy vacuum. Regulatory developments in recent years have reshaped how talent is sourced, engaged, and transferred across borders, making compliance capability a core dimension of supplier evaluation and internal process design. These shifts are particularly salient for organizations that rely on third-party recruitment partners or plan to scale hiring in jurisdictions with evolving labor protections.
A significant regulatory theme centers on recruitment fees and related costs. International standards increasingly prohibit charging workers for fees associated with international recruitment, reflecting a broader effort to protect migrant workers and reduce exploitation risk. In Europe and Central Asia, policy frameworks in a substantial majority of reviewed countries prohibit fee-charging for both national and international recruitment, signaling a compliance environment where transparent cost structures and employer-covered relocation expenses are becoming baseline expectations rather than optional best practices. In parts of Africa, legislation on recruitment fees often applies specifically to international recruitment, with many laws requiring employers to cover transportation costs for relocated workers. These provisions have direct implications for budgeting, supplier contracting, and the design of candidate experience workflows.
Beyond fee regulation, the ethical dimensions of international recruitment have gained prominence. Research has highlighted how recruitment fees and related costs can contribute to debt bondage, with a meaningful share of forced labor cases linked to such practices and a substantial annual extraction of resources from migrants in vulnerable situations. This reality elevates the importance of due diligence, ethical recruitment standards, and supplier accountability. For enterprises, compliance is no longer a legal checkbox; it is a reputational and operational imperative that affects brand trust, talent retention, and the sustainability of international hiring programs.
Data privacy regulation further complicates the recruitment operating environment. Requirements for transparency, consent, and accountability in handling candidate data are increasingly enforced, with ongoing guidance updates influencing cross-border data transfers and the use of automated decision-making in hiring. Organizations that deploy international recruitment at scale must ensure that candidate data flows, screening tools, and reporting mechanisms are designed to meet jurisdictional expectations without compromising speed or candidate experience.
Labor regulation and sector-specific visa frameworks also shape recruitment dynamics. In markets where specialized visa routes have been used to meet care and health workforce needs, reports of exploitation have prompted government responses, including rematching funds and renewed emphasis on ethical recruitment practices. These developments illustrate that international recruitment is subject to continuous policy recalibration, and that suppliers and enterprise buyers alike must maintain adaptive compliance processes, monitoring mechanisms, and escalation pathways.
Taken together, the regulatory environment reinforces a central theme of this research: international recruitment is a governance-intensive market. Organizations that treat compliance, data handling, and ethical sourcing as core design parameters—rather than after-the-fact controls—will be better positioned to manage risk, negotiate favorable terms, and build durable supplier relationships. The complete report details how these regulatory currents interact with market demand, supplier capabilities, and contract models across the forecast period.
Strategic Value for 2026 Decision-Making
The 2026 planning cycle presents a decisive moment for organizations that depend on international talent. The market's projected growth trajectory, combined with evolving regulatory expectations and a competitive supplier landscape, creates both expansion opportunities and execution risks. The strategic value of this research lies in its ability to convert macro trends into decision-ready intelligence across several core areas.
First, the study supports market-entry and geographic expansion planning. By connecting demand intensity with service-type preferences and vertical-specific hiring patterns, it helps leaders prioritize regions, sectors, and talent categories where recruitment partnerships can accelerate operational ramp-up and reduce time-to-productivity. Second, it strengthens procurement and vendor management. The competitive profiles and structural analysis enable more precise benchmarking, clearer service-level expectations, and better-aligned contracting strategies, particularly when organizations need to balance scale, specialization, and compliance assurance.
Third, the research informs compliance and risk frameworks. The integration of regulatory developments into the market analysis helps organizations anticipate changes in fee structures, data handling requirements, and ethical sourcing expectations, allowing procurement and legal teams to build forward-looking controls rather than react to incidents. Fourth, it supports workforce planning and capital allocation. With a credible growth baseline and an extended forecast horizon, executive teams can align hiring budgets, partnership investments, and capability-building initiatives with a market trajectory that reflects both demand continuity and structural change.
Finally, the study provides a foundation for scenario-based strategy. Because international recruitment is influenced by policy shifts, economic cycles, and sector-specific labor dynamics, organizations benefit from understanding how different demand patterns, supplier capacities, and compliance regimes could reshape sourcing outcomes over time. The full report offers the detailed segmentation, benchmarking, and scenario insights needed to construct these scenarios with specificity.
Worldwide International Recruitment Services Market
Closing Perspective
The Worldwide International Recruitment Services Market is entering a phase in which scale, specialization, and governance converge. Growth is sustained, competition is diverse, and regulatory expectations are tightening across multiple jurisdictions. For leaders responsible for talent acquisition, global operations, procurement, and corporate strategy, the ability to interpret these forces with precision is a competitive advantage. This research is designed to provide that precision: a comprehensive, analytically rigorous, and operationally relevant intelligence asset that supports informed decision-making throughout the 2026-2032 horizon.
The complete report delivers the full market sizing, segment-level analysis, regional and vertical breakdowns, supplier benchmarking, and compliance-informed strategic guidance necessary to translate high-level trends into concrete action plans. We invite strategy, HR, procurement, and investment teams to access the full publication to obtain the detailed figures and frameworks required to calibrate sourcing strategies, evaluate supplier portfolios, and prepare for the next phase of international talent mobility.
For detailed analysis of this topic, please visit the official page: Worldwide International Recruitment Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com