

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Flow Field Plate Market to Hit $15.9B by 2032, 28.45% CAGR

Beyond the Hydrogen Horizon: Strategic Intelligence in the Global Flow Field Plate Market through 2032
The global energy transition has entered a phase of decisive industrial scaling. Nowhere is this trajectory more evident than in the flow field plate sector, a critical subsystem governing fluid distribution, electrical conductivity, and mechanical durability across fuel cell stacks, electrolyzers, and stationary power installations. As capital allocation shifts from laboratory validation to gigawatt-scale manufacturing, decision-makers require more than directional trends. They need granular, forward-looking intelligence that maps technology roadmaps, supply chain inflection points, and competitive positioning against a rapidly compressing investment window. Our newly released Worldwide Flow Field Plate Market research delivers precisely that. Built on a rigorous methodology spanning historical tracking from 2020 through the base year of 2025, and projecting forward across a 2026 to 2032 forecast horizon, this study equips executives, procurement leaders, and strategic planners with the analytical leverage required to navigate a market undergoing structural acceleration.
In 2026, the operational landscape for hydrogen technologies and electrochemical power systems is no longer defined by theoretical potential. It is defined by cost curves, manufacturing throughput, and supply chain resilience. The flow field plate has evolved from a passive component into a performance bottleneck and a differentiation lever. Material selection, surface engineering, coating architectures, and production tolerances directly dictate stack longevity, power density, and levelized cost of energy. Companies that treat this segment as a commodity procurement category are rapidly ceding ground to competitors who recognize it as a strategic capability node. Our research is structured to close that awareness gap, translating macroeconomic momentum into actionable market architecture.
The Macro Trajectory: Decoding the Growth Inflection
The market's historical trajectory tells a story of compounding adoption. Over the past half-decade, revenue generation has escalated from a foundational baseline in 2020 to a substantially expanded operational footprint by 2025. That momentum does not plateau; it compounds. Our forecast model projects the global market to surpass the mid-three-billion-dollar threshold in 2026, followed by sustained expansion that pushes total industry revenue well beyond the fifteen-billion-dollar mark by the close of the 2032 projection window. At the core of this expansion sits a compound annual growth rate of 28.45 percent, a figure that reflects not merely cyclical demand but a structural realignment in how clean energy infrastructure is manufactured, deployed, and scaled.
Such growth is not distributed uniformly across time, geography, or application. It concentrates in segments where performance requirements intersect with manufacturing readiness, regulatory tailwinds, and capital deployment velocity. For strategic planners, the implication is clear: headline figures are useful for boardroom context, but segment-level dynamics dictate where capacity should be allocated, where supplier partnerships should be forged, and where technical roadmaps should be prioritized. Our report dissects these dynamics without reducing them to static snapshots, instead presenting them as interdependent variables that shift as technology maturation curves cross commercial adoption thresholds.
The strategic value of this market intelligence lies in its ability to separate signal from noise. Raw material constraints, coating specifications, throughput limitations, and regional trade policy adjustments all exert measurable pressure on cost structures and delivery timelines. By mapping these pressures against demand trajectories, the study enables organizations to anticipate supply-demand mismatches before they become operational liabilities. Executives can evaluate whether to lock in long-term feedstock agreements, diversify supplier bases, or invest in proprietary forming and etching capabilities. The data does not prescribe a single path; it illuminates the trade-offs embedded in each strategic choice.
What the Report Delivers: Operational Intelligence, Not Just Forecasts
A market study earns its place on an executive dashboard only when it translates into operational decision-making. Our Worldwide Flow Field Plate Market research is engineered around that standard. The publication moves systematically through the architecture of the industry, beginning with a comprehensive segmentation framework that isolates material type, application domain, and regional deployment patterns. Rather than presenting these splits as isolated tables, the analysis contextualizes them within technology adoption lifecycles, manufacturing scalability constraints, and end-use performance requirements.
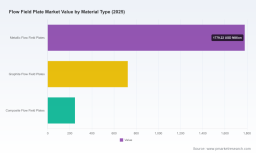
The material segment analysis examines how metallic, graphite, and composite flow field plates compete across different performance and cost envelopes. Each category carries distinct implications for conductivity, corrosion resistance, manufacturing complexity, and supply chain dependencies. The application analysis traces how demand differentiates across fuel cell electric vehicles, stationary power generation, and electrolyzer deployments, highlighting where volume scaling, durability thresholds, and integration requirements diverge. Regional analysis maps where manufacturing capacity, end-market demand, and policy support converge, enabling readers to assess localization strategies, tariff exposure, and logistics optimization opportunities without relying on superficial geographic generalizations.
Beyond segmentation, the report delivers a deep operational review of production methodologies and technology roadmaps. Photochemical etching, progressive die forming, compression molding, high-velocity forming, and advanced coating architectures are evaluated against throughput, precision, capital intensity, and scalability. This technical grounding matters because manufacturing process selection directly influences unit economics, quality consistency, and the ability to meet emerging performance targets set by government research programs and industry consortia. Decision-makers gain a structured basis for evaluating whether to outsource, co-develop, or internalize critical production capabilities.
The study also integrates competitive benchmarking, supplier capability mapping, and recent market movements that signal shifting industry momentum. New product introductions, capacity expansions, strategic partnerships, and technology demonstrations are analyzed not as isolated headlines but as indicators of where capital and engineering effort are being concentrated. By connecting these developments to broader supply chain and regulatory dynamics, the report provides a living map of competitive positioning that remains relevant as the market matures.
Competitive Architecture: Navigating a Fragmented but Consolidating Field
The flow field plate ecosystem is characterized by a blend of specialized manufacturers, integrated fuel cell developers, and industrial players expanding into hydrogen-adjacent production. Market concentration metrics indicate that the top three players account for 38.4 percent of industry revenue, while the top five collectively capture 52.65 percent. This concentration profile signals a market that is broad enough to accommodate diverse entrants yet structured enough that scale, process know-how, and customer integration relationships confer meaningful defensive advantages.
Worldwide Bipolar Plate Fuel Cell Market
Players such as Switzer and Precision Micro have built reputations around photochemical machining and chemical etching, offering high-precision metallic bipolar and flow field plates that serve electrolyzer, hydrogen generation, and fuel cell applications across prototyping and high-volume production. Their capabilities emphasize design flexibility and tight geometric control, attributes that matter when flow distribution and pressure drop management directly influence stack efficiency. Fuel Cell Store and Ensinger address the graphite segment with customizable plate designs and scalable production pathways, supporting electrochemical devices that prioritize different trade-offs between weight, conductivity, and corrosion behavior. In China, TMNetch focuses on photochemical etching for metallic plates, emphasizing durability and energy efficiency in fuel cell environments, while Interplex leverages corrosion-resistant stainless steel formulations with PVD coatings to extend operational lifespan in demanding PEM applications.
On the industrial scaling frontier, companies like Dana Incorporated and EKPO Fuel Cell Technologies bring high-speed forming, conductive coatings, and integrated sealing architectures to metallic bipolar plate production, aligning their output with high-volume PEM fuel cell and electrolyzer requirements. Dana's recent product introduction for high-density electrolyzers, which pairs titanium or steel substrates with advanced forming, conductive coating, and molded elastomer sealing, illustrates how incremental engineering refinements target both power density and cost reduction simultaneously. Schunk Group contributes compression-molded graphite bipolar plates with integrated flow fields, offering single-plate and redox flow cell solutions that support energy storage and fuel cell architectures. Ballard Power Systems continues to advance flexible graphite bipolar plate lines and next-generation manufacturing capacity, supported by policy-aligned funding initiatives that underscore the strategic importance of domestic production readiness.
Worldwide Flow Field Plate Market
The competitive landscape also includes operators scaling proprietary manufacturing technologies. Cell Impact's high-velocity forming approach and large-scale production facilities position it to serve fuel cell and electrolyzer demand at volume, reinforced by partnerships that combine forming with welding technology for high-volume bipolar flow plate production. SITEC and Precision Resource extend the field further by covering coil-to-installation manufacturing pathways and specialized metal forming for zero-emission vehicles and green hydrogen production. Taken together, these players illustrate a market where competitive advantage is increasingly defined by process engineering, coating expertise, integration support, and the ability to move from prototype validation to reliable series production.
Market Dynamics and the Forces Reshaping Supply and Demand
No forward-looking strategy is complete without a clear understanding of the forces that can accelerate, delay, or redirect market growth. Raw material considerations remain foundational. Graphite-based flow field plates depend on high-purity feedstock, while composite variants typically carry substantial graphite loading combined with polymer binders, creating a material architecture that balances conductivity with mechanical and chemical resilience. Metallic plates, by contrast, commonly rely on stainless steel or titanium substrates, with precision steel strip in narrow thickness ranges enabling complex flow field forming. These material realities link the flow field plate market directly to upstream commodity dynamics, specialty coating availability, and precision metallurgy supply chains.
Regulatory and policy frameworks exert equally directional influence. Support for bipolar plate manufacturing advancement continues through government-backed programs that fund next-generation production lines and technology development initiatives. Technical targets for PEM fuel cell bipolar plates increasingly emphasize electrical conductivity, areal specific resistance, and cost-per-kilowatt thresholds at volume. These targets are not abstract benchmarks; they function as design constraints that shape R&D priorities, supplier qualification criteria, and procurement negotiations. Organizations that internalize these performance and cost targets early can align their engineering roadmaps with the standards that will govern future market access.
Trade policy and regional cost dynamics add another layer of strategic complexity. Tariff adjustments affecting metallic feedstocks and specialty coatings have already altered unit input costs for manufacturers operating in affected markets. Such shifts influence supplier selection, regional sourcing strategies, and the economic calculus behind domestic versus imported production. Meanwhile, recent capacity expansions and technology demonstrations signal where the industry is placing its bets. Large-scale production line construction for flow plate and vanadium flow battery-related applications, modular pilot plants for rapid and cost-effective bipolar plate production, and partnership agreements targeting high-volume manufacturing installation all point to an ecosystem moving from fragmented experimentation toward coordinated commercial scaling.
For corporate strategy teams, these dynamics create both risk and optionality. Supply chain diversification, long-term coating and feedstock agreements, localization of critical process steps, and selective vertical integration all become viable responses depending on an organization's risk tolerance, capital position, and customer commitments. The report's value lies in helping leaders evaluate those responses against a structured map of market forces rather than reacting to isolated events after the fact.
Why 2026 Is the Strategic Inflection Point
2026 represents more than another forecast year. It marks the point at which early adoption momentum transitions into industrial scaling, where procurement decisions begin to lock in capabilities for the remainder of the decade, and where competitive positioning becomes increasingly difficult to reverse. The flow field plate market is expanding at a pace that rewards organizations with clear technology roadmaps, disciplined supplier strategies, and a realistic understanding of where manufacturing complexity can be absorbed internally versus where it should be managed through partnerships.
The research does not merely project growth; it structures the decision environment around the variables that actually determine outcomes. Which material class aligns with your performance requirements and cost targets? Where does your application mix concentrate, and how does that shape volume commitments? Which manufacturing processes offer the best path to precision, throughput, and scalability for your specific product architecture? How do recent product launches, capacity expansions, and partnership announcements change the competitive baseline you are operating against? These are the questions our study is designed to answer with analytical rigor rather than directional intuition.
Executives who engage with this intelligence early gain a measurable advantage in opportunity prioritization, risk mitigation, and capital deployment timing. They can distinguish between temporary demand spikes and durable structural growth, between capability claims and proven production readiness, and between regional opportunities that justify localization investment and those that remain better served through established supply channels. In a market moving at a 28.45 percent compound annual growth rate toward a 2032 revenue trajectory that redefines the scale of hydrogen and electrochemical infrastructure, strategic latency carries real cost.
Closing the Intelligence Gap: Access the Full Study
The macro trajectory, segmentation architecture, competitive mappings, and dynamic force analyses summarized here provide a substantive preview of the strategic landscape. They establish the analytical foundation and demonstrate the depth of methodology embedded in the full publication. Yet the most consequential details, the segment-level dimensions, the regional deployment patterns, the application-specific volume dynamics, and the supplier-level capability comparisons that inform precise go-to-market and procurement decisions, are intentionally held within the complete report.
This is not a limitation of the preview; it is the design of a strategic intelligence product. Executive briefings establish context and credibility. Detailed market data, scenario-ready segmentation, and granular competitive assessments enable execution. Organizations that require precise figures for capacity planning, supplier negotiation, technology investment justification, and market entry evaluation will find the complete Worldwide Flow Field Plate Market research built for exactly that purpose. The full study translates directional confidence into operational precision, giving strategic teams the evidence base required to commit capital, align engineering roadmaps, and position competitively across the 2026 to 2032 horizon.
Access the complete market research to secure the full segmentation data, regional deployment intelligence, application-level demand analysis, and competitive benchmarking required to move from strategic awareness to decisive action. In a market scaling this rapidly, the difference between informed positioning and reactive adaptation is access to the right intelligence at the right time.
For detailed analysis of this topic, please visit the official page: Worldwide Flow Field Plate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com