

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Cancel for Any Reason Travel Insurance Market to Hit $2.04B by 2032 at 13.23% CAGR

Worldwide Cancel for Any Reason Travel Insurance Market: Strategic Intelligence for 2026 Decision-Making
The global travel insurance landscape has entered a period of structural transformation, driven by heightened traveler sensitivity to uncertainty and the rapid commercialization of flexible coverage products. At the center of this shift is the Cancel for Any Reason (CFAR) Travel Insurance market, a niche segment that has evolved from a marginal rider into a strategic differentiator for insurers, aggregators, and travel service providers. Our newly released Worldwide Cancel for Any Reason Travel Insurance Market study maps the segment across a 2020-2025 historical baseline and a 2026-2032 forecast horizon, translating complex demand signals, distribution realignments, and competitive maneuvers into an executive-ready intelligence framework. For leadership teams navigating product positioning, channel partnerships, or capital allocation in 2026, this research offers a disciplined lens on where value is concentrating and how the segment is likely to mature.
The macroeconomic trajectory captured in the study underscores why CFAR has moved from a peripheral insurance feature to a core strategic consideration. The overall market reached an estimated valuation of USD 852.4 Million in 2025, reflecting a compound trajectory from USD 280.45 Million in 2020. Over the forecast period extending to 2032, the segment is projected to follow a CAGR of 13.23%, with revenue scaling toward a multi-billion-dollar threshold as traveler expectations for granularity and flexibility continue to reshape purchase behavior. The analytical architecture of the study captures this expansion through layered segmentation by region, distribution channel, and traveler type, while also examining market concentration indicators that reveal how competitive power is distributed across leading providers. Crucially, the research goes beyond top-line sizing. It dissects the operational mechanics of CFAR adoption, the structural constraints imposed by regulatory environments, and the strategic implications for insurers balancing underwriting discipline against the growing appetite for unparalleled cancellation flexibility.
Report Scope and Operational Content
A market study earns its stature not through headline figures but through its capacity to inform real-world decisions. This research is structured to serve product strategists, distribution leaders, and competitive intelligence teams who require more than surface-level sizing. The report integrates historical progression analysis with forward-looking scenario modeling, allowing readers to assess momentum vectors rather than static snapshots. Coverage includes a detailed segmentation review that isolates how CFAR demand behaves across geographic markets, how it flows through distinct commercial channels, and how it maps to traveler personas ranging from individual leisure buyers to corporate travel programs and group travel arrangements.
The study is built around actionable analytical modules designed to support planning cycles in 2026. These include baseline market estimation, growth-rate derivation, and segmentation-level performance mapping that identifies where volume and value are accumulating. It also examines the structural factors that shape adoption, such as purchase-timing sensitivity, reimbursement design, and the interaction between standard trip cancellation benefits and CFAR upgrades. By tracing these mechanics, the report provides a practical foundation for assessing product design choices, pricing architecture, and channel strategy without reducing the segment to a single aggregate number.
Travel Insurance Market
Equally important is the report’s treatment of market structure and competitive behavior. Rather than presenting a simple roster of participants, the analysis situates each major provider within the broader ecosystem, highlighting how reimbursement ratios, add-on design, waiting period configurations, and regional eligibility rules shape competitive positioning. This allows executives to evaluate not just who is active in the market, but how different players are attempting to convert flexibility into durable share. For teams assessing partnership opportunities, benchmarking exercises, or entry strategies, this framing provides the kind of comparative clarity that supports informed judgment rather than speculative positioning.
Macro Trajectory and Demand Signals
The strength of the CFAR market is best understood as a function of both structural demand and episodic volatility. Over the historical period, the segment expanded through a combination of broader travel insurance penetration and a measurable shift toward coverage that gives travelers a discretionary exit option. That momentum accelerated in early 2026, when interest in Cancel for Any Reason coverage rose sharply in response to geopolitical instability and operational uncertainty. Industry reporting from March 2026 noted a significant uptick in buyer attention, reinforcing the pattern that CFAR demand often intensifies when travelers perceive higher unpredictability in itineraries, booking conditions, or broader travel environments.
This dynamic creates a strategic paradox for insurers and distributors. CFAR is not merely a product feature; it is a behavioral hedge that travelers increasingly value when plan certainty declines. At the same time, its design introduces complexity around timing, eligibility, and reimbursement structure. Most plans require purchase within a limited window after the initial trip deposit, require that the policyholder insure 100% of nonrefundable trip costs, and generally mandate cancellation at least 48 hours before departure. Reimbursement levels typically range from 50% to 75% of prepaid nonrefundable trip costs, with select offerings offering higher reimbursement ceilings. These parameters make CFAR highly attractive to risk-aware travelers, but they also mean that product design, communication clarity, and distribution timing become decisive factors in conversion.
Industry data suggests that approximately 10% of travel insurance plans purchased include CFAR coverage, a figure that reflects both the segment’s specialized appeal and its still-niche status within the broader travel insurance purchase base. That proportion matters because it signals room for expansion while also indicating that CFAR remains sensitive to price perception, plan bundling, and traveler awareness. The study interprets this trajectory not as a simple growth story, but as a demand curve shaped by consumer preference for flexibility, the influence of external disruption, and the way distribution channels translate that preference into completed purchases.
Segmentation Architecture and Strategic Implications
One of the most valuable contributions of the research is its segmentation logic. CFAR performance cannot be understood in isolation; it is mediated by where travelers buy coverage, who they are, and how regional market conditions influence product acceptance. The study maps these dimensions to reveal where demand is concentrated and where commercial opportunity may be underleveraged.
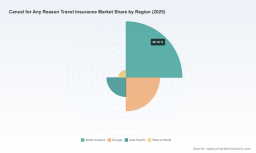
From a regional perspective, the analysis examines how mature versus emerging markets differ in their appetite for flexibility-driven coverage. Mature markets tend to exhibit higher baseline insurance penetration and more developed consumer familiarity with ancillary travel protections, while other regions may show faster relative growth as travel activity expands and buyers become more intentional about cancellation risk. The report avoids oversimplified regional generalizations. Instead, it evaluates market structure in a way that helps strategists determine whether CFAR should be positioned as a premium differentiator, a conversion enhancer, or a bundled protection element depending on local demand characteristics.
Distribution channel analysis is equally critical. The way CFAR is sold shapes both visibility and trust. Direct online channels and insurtech platforms play an outsized role in making flexible coverage discoverable, while travel agencies and online travel agencies contribute volume through trip-linked purchase pathways. Traditional insurance brokers continue to serve segments where personalized advisory interaction influences product selection. The study evaluates how these channels differ in their ability to educate buyers on CFAR’s terms, manage purchase timing, and position reimbursement expectations. For operators, this analysis supports decisions about where to invest in consumer-facing explanation, where to optimize embedment into booking flows, and where broker-led guidance may create premiumization opportunities.
Traveler type segmentation further sharpens the strategic view. Individual and leisure travelers often drive discretionary CFAR purchases because they are more directly exposed to personal trip disruption risk. Business and corporate travelers represent a distinct value pool, where cancellation flexibility may intersect with policy administration, duty-of-care considerations, and travel program compliance. Group and family travelers introduce different purchasing dynamics, often balancing total trip cost coverage against the convenience of a shared policy. By separating these personas, the research enables more precise messaging, channel targeting, and product configuration decisions.
Competitive Landscape and Product Differentiation
CFAR is a segment where differentiation is often subtle but commercially decisive. The study profiles leading participants and evaluates how each uses reimbursement design, add-on structure, waiting periods, and eligibility rules to create competitive posture. Several U.S.-based providers anchor the market, and each illustrates a different approach to converting flexibility into perceived value.
Allianz Travel Insurance offers CFAR or a Cancel Anytime upgrade on select plans such as OneTrip Prime and OneTrip Premier, with reimbursement reaching up to 80% of prepaid nonrefundable trip costs and the ability to cancel as late as the day of departure under certain configurations. That positioning reflects a strategy centered on premium reimbursement ceilings and late-window flexibility. Seven Corners provides CFAR as an optional add-on on plans including Trip Protection Basic, with reimbursement up to 75% and a reputation for short waiting periods, which can be an important conversion factor for time-sensitive buyers. Travel Insured International includes optional CFAR benefits on its Worldwide Trip Protector plans, reimbursing up to 75% for cancellations not otherwise covered and emphasizing broad trip protection integration.
IMG offers CFAR as an optional add-on on iTravelInsured plans such as Travel LX, Travel SE, and Choice, with reimbursement up to 75%, though availability is not uniform across all states. Trawick International has pursued a distinct product-led strategy by embedding CFAR within its Safe Travels plan family, including the Safe Travels AnyReason plan, which provides 75% reimbursement without an additional fee. That design is notable because it reduces the friction typically associated with add-on pricing and reframes CFAR as an integrated plan attribute rather than a separate purchase decision. WorldTrips offers CFAR coverage on its Atlas Journey series, aiming to give travelers a path to recover nonrefundable trip costs for any reason, while Travelex Insurance Services incorporates CFAR options and positions them around value and emergency coverage breadth.
Travel Guard, part of AIG, offers an optional Cancel for Any Reason add-on that reimburses a percentage of nonrefundable trip costs, reflecting the scale and brand visibility that large travel insurance franchises bring to the segment. World Nomads provides an optional CFAR upgrade on Explorer and Epic plans for U.S. residents, with eligibility limitations in certain jurisdictions. Generali Global Assistance offers optional CFAR on Premium plans with reimbursement up to 75% of nonrefundable trip costs, aligning flexibility with higher-tier plan positioning. Tin Leg has been identified among competitive CFAR providers for 2026, suggesting ongoing entry and repositioning activity in the market. Faye is noted for CFAR coverage linked to non-medical evacuation benefits, illustrating how some providers associate flexible cancellation with broader protection narratives.
These profiles are not presented as isolated product summaries. They are used to interpret how reimbursement ceilings, fee structures, timing rules, and regional eligibility constraints influence competitive advantage. The report also tracks structural developments that alter market expectations, including product launches that reset baseline assumptions. For example, Trawick International’s 2024 launch of Safe Travels AnyReason introduced an industry-first plan with embedded CFAR offering 75% reimbursement without an additional fee, a move that signaled how product architecture could be used to lower purchase friction. More recently, industry attention to rising CFAR interest in early 2026 has reinforced the idea that demand for flexible cancellation is responsive to broader uncertainty cycles.
Regulatory and Structural Dynamics
Any credible CFAR strategy must contend with the regulatory and operational constraints that shape offerable terms. The study dedicates significant attention to the forces that determine what can be sold, how it can be presented, and where limitations apply. CFAR coverage is subject to time-sensitive purchase windows, requirements that 100% of nonrefundable trip costs be insured, and cancellation thresholds that commonly require action at least 48 hours before departure. These operational rules influence both consumer behavior and product design, making them essential considerations for anyone evaluating conversion pathways or underwriting exposure.
Regulatory nuance is equally important. In certain jurisdictions, CFAR benefits are treated with specific interpretive guidance rather than as standard insurance coverage. For instance, New York DFS Insurance Circular Letter No. 4 from 2020 clarified that CFAR benefits do not technically qualify as insurance in the traditional sense and provided guidelines for offering them as incidental benefits or within standalone contracts. As a result, CFAR may not be available under standard policy configurations in some environments, and in practical terms, certain providers do not offer CFAR to New York residents under specific plans. These state-level and jurisdictional distinctions create fragmented availability and can affect both market sizing and competitive reach.
From a market structure standpoint, the study also examines concentration indicators that reveal how consolidated the competitive base is. The research captures market concentration metrics including a CR3 of 38.45% and a CR5 of 52.3%, signaling that a limited group of leading participants accounts for a substantial share of the segment while still leaving meaningful space for specialty providers, insurtech entrants, and distribution-led differentiation. This concentration picture matters because it helps leaders gauge how crowded the core is, where differentiation is most needed, and whether share gains are likely to come from product innovation, channel leverage, or brand trust.
Strategic Takeaways for 2026 Decision-Making
For executives planning around 2026, the report’s central value lies in converting market momentum into decision-grade insight. The CFAR segment is expanding in a context where traveler demand for flexibility is no longer marginal, but it remains sensitive to purchase timing, reimbursement framing, and regulatory boundaries. That combination means the winners are unlikely to be determined solely by who offers CFAR, but by who can make it understandable, accessible, and commercially coherent within the purchase journey.
Several strategic implications emerge from the analysis. First, product design and communication clarity are becoming competitive levers in their own right. Because CFAR depends on narrow purchase windows and specific eligibility conditions, providers and distributors that can reduce confusion and align messaging with real traveler decision points may capture disproportionate conversion advantage. Second, channel strategy deserves deliberate attention. Online direct and insurtech pathways can strengthen visibility and speed to purchase, while agency and OTA touchpoints can reinforce trust and trip-linked relevance. The optimal mix depends on the target traveler type and the regional market being addressed.
Third, reimbursement architecture is not merely a marketing feature; it is a structural differentiator. Higher reimbursement ceilings, waived add-on fees, and short waiting periods each address different sources of buyer resistance. Providers that align these elements with their broader plan portfolio can shape perceived value in ways that extend beyond price competition. Fourth, regulatory heterogeneity must be managed carefully. Jurisdiction-specific availability and treatment of CFAR create both constraints and opportunities, especially for organizations operating across multiple states or planning multi-market expansion. Understanding where CFAR can be offered, how it can be presented, and which configurations are permissible is essential to avoiding compliance friction and identifying under-served pockets of demand.
Finally, the report is intended to help leadership teams look beyond cyclical spikes and assess the durability of demand. The recent rise in interest is consistent with the pattern that CFAR becomes more attractive when uncertainty increases, but the longer-term opportunity depends on whether flexible cancellation can be normalized as an expected element of travel protection rather than a crisis-driven purchase. The study provides the context to evaluate that transition, including how market concentration, distribution dynamics, and product innovation interact to determine whether CFAR remains a premium add-on or becomes a more widely embedded purchase expectation.
Worldwide Cancel for Any Reason Travel Insurance Market
Why This Research Matters Now
Market intelligence is most valuable when it enables decisions that are both timely and precise. The Worldwide Cancel for Any Reason Travel Insurance Market study is designed to support that standard by combining historical context, forward-looking growth modeling, segmentation analysis, and competitive profiling in a single analytical framework. It gives decision-makers a structured view of how the segment has evolved, how it is currently contested, and where strategic attention is likely to produce the greatest return in 2026 and beyond.
At the same time, the study intentionally preserves depth that cannot be fully captured in a summary format. Segmentation-level performance, regional market behavior, channel-specific flow patterns, and the full competitive comparison across providers are developed in detail within the complete report. These components are essential for teams that need to benchmark against specific peers, evaluate channel investments, or build product strategies with a clear view of where value is concentrating. The overview presented here is intended to establish the strategic contours and demonstrate the research’s analytical rigor, while inviting a deeper engagement with the full dataset and interpretive commentary.
For organizations seeking to act on the CFAR opportunity with discipline rather than speculation, this research provides the foundation. It clarifies the market’s growth logic, identifies the forces shaping demand, and frames the competitive and regulatory realities that will influence execution. The complete report extends that foundation into the level of detail required for operational planning, making it a strategic reference for executives, product leaders, and market analysts who need to navigate a segment that is expanding quickly, differentiating sharply, and becoming increasingly central to the future of travel insurance.
For detailed analysis of this topic, please visit the official page: Worldwide Cancel for Any Reason Travel Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com