

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
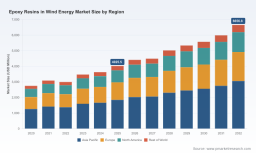
PW Consulting: Global Epoxy Resin Market in Wind Energy to Hit $6,656.8M by 2032 at 7.45% CAGR

Navigating Material Innovation and Market Volatility: The Strategic Imperative for Epoxy Resins in Wind Energy
The global transition toward renewable energy infrastructure is no longer a question of if, but how fast and at what material cost. As wind turbine blades grow larger and operational environments become more demanding, the performance requirements for structural adhesives, infusion systems, and protective coatings have intensified. For strategic decision-makers in the wind energy value chain, understanding the epoxy resin landscape is not merely a procurement exercise; it is a critical lever for managing risk, optimizing lifecycle costs, and securing supply chain resilience in a rapidly fragmenting trade environment.
Our latest publication, Worldwide Epoxy Resins in Wind Energy Market, offers a comprehensive, data-driven examination of this specialized segment. Drawing on historical performance from 2020 through 2025 and projecting market trajectories through 2032, this research translates macroeconomic shifts, regulatory interventions, and technological advancements into actionable intelligence. What follows is a strategic preview of the forces shaping this market and why a thorough, granular analysis is essential for enterprise planning in 2026 and beyond.
Worldwide Epoxy Resins in Wind Energy Market
A Market Defined by Scale, Steady Growth, and Structural Complexity
The aerospace-grade precision and marine-grade durability required in modern wind turbine blades place epoxy resins at the center of composite manufacturing. Over the past half-decade, the sector has demonstrated remarkable resilience, weathering raw material volatility, shifting trade policies, and evolving engineering specifications. Historical revenue tracking reveals a market that has consistently expanded in absolute terms, recovering swiftly from cyclical dips and accelerating as turbine manufacturers push toward longer rotor diameters and offshore deployments. Current baseline valuations place the market in the low billions of USD, with a forecast period extending to 2032 that outlines a compound annual growth rate in the mid-single digits.
This trajectory is not uniform. Growth is being pulled forward by blade manufacturing applications, where resin infusion, hand lay-up, and vacuum-assisted processes dominate. Secondary demand streams from structural bonding and surface protective coatings contribute meaningfully but operate under different pricing dynamics, regulatory exposures, and formulation constraints. The concentration of revenue among top-tier suppliers further shapes pricing power, negotiation leverage, and innovation pacing across the supply chain. With the top three players capturing a substantial share and the top five commanding a majority of market activity, competitive positioning requires more than benchmarking. It demands an understanding of how formulation leadership, geographic footprint, and OEM partnerships translate into sustained market share.
The report dissects these dynamics without reducing them to oversimplified aggregates. Readers gain access to base-year valuations, year-over-year growth patterns, and forward-looking revenue projections that map the pace of expansion across the forecast horizon. Critically, the analysis preserves the integrity of each revenue stream, allowing strategists to evaluate how material substitution cycles, turbine upsizing trends, and regional manufacturing shifts will redistribute demand rather than simply expand it.
Segmentation That Matters: Where Formulations, Geography, and End-Use Intersect
Epoxy resins deployed in wind energy are not interchangeable inputs. They vary in viscosity, curing kinetics, glass transition temperatures, toughness modifiers, and environmental resistance profiles. The market reflects this specialization through a clear stratification by resin type, spanning conventional liquid systems favored for their processing flexibility, higher-solid variants that cater to weight and curing efficiency targets, and an emerging cohort of bio-based and specialty resins designed to address sustainability mandates and end-of-life considerations. Each category carries distinct cost structures, performance trade-offs, and adoption timelines that directly influence procurement strategy and product roadmap decisions.
Geographic distribution of demand adds another layer of strategic complexity. Wind energy manufacturing and installation pipelines differ markedly by region, shaped by policy incentives, port infrastructure, OEM localization efforts, and the maturity of domestic composite material ecosystems. Asia Pacific, Europe, and North America each present unique thresholds for pricing sensitivity, supply reliability, and formulation customization. A nuanced reading of regional consumption patterns reveals where import dependency intersects with local production capacity, and where tariff exposure or logistical constraints could alter total landed costs over the next several years.
On the application side, blade manufacturing commands the largest share of resin expenditure because it represents the most material-intensive and performance-critical step in turbine assembly. Structural adhesives and surface protective coatings serve essential but more specialized roles, often requiring tailored formulations that balance mechanical strength with weatherability, chemical resistance, and ease of maintenance. The report maps these application channels in detail, highlighting how design specifications, blade length trajectories, and offshore servicing requirements continuously redefine material specifications and purchasing priorities.
Special Epoxy Resin for Wind Power Blades Market
Rather than presenting segmentation as static snapshots, the analysis tracks how these splits evolve under pressure from feedstock costs, recycling initiatives, and process innovations such as faster-curing resin systems and hybrid thermoplastic-epoxy architectures. This progression-oriented view is vital for companies that need to anticipate substitution risks, evaluate supplier diversification options, or align internal R&D pipelines with shifts in OEM specifications.
Competitive Arena: Formulation Leadership, Geopolitical Exposure, and Pace of Innovation
The competitive field in wind energy epoxy resins is concentrated among large, globally integrated chemical manufacturers and a complement of regional specialists with strong technical reputations in composite processing. Several North American incumbents have built deep account relationships through long-standing supply of infusion systems, hand lay-up materials, and tooling solutions tailored for large-scale rotor blades. Their competitive advantage rests on proven performance heritage, process compatibility across filament winding, resin transfer molding, and vacuum infusion, and the ability to support turbine OEMs through iterative blade design changes.
European participants bring differentiated technical narratives centered on weather resilience, mechanical stress tolerance, and specialized epoxy-hardener combinations engineered for fiber-reinforced composite structures. Switzerland-based suppliers contribute composite epoxy systems optimized for vacuum infusion, structural bonding, and post-manufacture repair or surface finishing, reinforcing the importance of total lifecycle support beyond initial blade fabrication. Meanwhile, producers across East and South Asia have expanded their relevance by supplying cost-competitive resin grades and, increasingly, specialty formulations that address regional demand patterns and recycling-oriented material development.
Recent corporate activity underscores how rapidly the competitive landscape can shift. One major North American supplier introduced a low-viscosity epoxy resin system aimed at accelerating curing cycles for very large blades, signaling a focus on throughput and production economics that directly resonates with blade manufacturers under pressure to scale output. Another prominent player advanced a thermoplastic-epoxy hybrid resin tailored for improved recyclability, aligning with growing OEM interest in circularity and end-of-life blade management. At the same time, pricing actions have reflected the reality of evolving trade policy: announcements of double-digit increases on epoxy resins followed the removal of certain imports from tariff exemption lists, altering supply cost expectations for downstream applications.
These developments illustrate a broader truth: competitive positioning in this market is not determined by resin volume alone. It is shaped by formulation leadership, speed of process adaptation, regulatory navigation, and the ability to partner with OEMs on both performance and sustainability goals. The report profiles the core companies shaping this arena, examining how their technical portfolios, geographic reach, and recent strategic moves position them relative to shifting demand patterns. Rather than provide a static roster, the analysis connects product launches, pricing actions, and partnership activity to the underlying market forces that will determine which suppliers retain or expand influence through 2032.
Trade Policy, Feedstock Economics, and the New Calculus of Cost Management
No strategic assessment of epoxy resins in wind energy can ignore the regulatory and input-cost environment that has redefined procurement risk in recent years. Raw material economics remain a dominant driver of production costs, with key feedstocks such as bisphenol A and epichlorohydrin accounting for a substantial portion of manufacturing expense. Price movements in these inputs can quickly cascade into resin pricing, particularly when coupled with regional supply imbalances or demand surges from wind energy composites.
The trade policy landscape has amplified this sensitivity. Regulatory decisions in major end markets have altered exemption statuses and exposed imports to reciprocal tariff structures, prompting domestic price adjustments and forcing supply chain reevaluations. Anti-dumping duties imposed by the European Union on epoxy resin imports from several Asian sourcing countries have created a distinctly uneven competitive field, while other sourcing origins have faced different duty treatments. In parallel, feedstock price dynamics have shown quarter-to-quarter volatility, with notable declines in North American bisphenol A pricing driven by ample Asian supply, juxtaposed against firm demand and elevated feedstock costs that lifted regional resin prices in Northeast Asia.
These factors make clear that cost management in wind energy epoxy procurement is no longer a matter of negotiating quarterly rates. It requires scenario planning around duty exposure, feedstock trajectory, and supplier concentration risk, as well as an understanding of how formulation adjustments might mitigate total cost of ownership even when per-kilogram prices rise. The report integrates these external pressures into its market outlook, enabling readers to interpret growth projections through the lens of real-world cost drivers rather than abstract demand curves.
What the Report Delivers for 2026 Decision-Making
Strategic planning in 2026 demands intelligence that connects market size with market mechanics. The Worldwide Epoxy Resins in Wind Energy Market study is structured to provide precisely that connection. Beyond headline valuations and growth rates, the report provides a detailed operational map of the segment, including the interplay between resin type, application channel, and regional demand patterns, all contextualized within the evolving tariff, feedstock, and sustainability environment.
Key deliverables designed to support executive and operational decision-making include:
- A forward-looking revenue model spanning the forecast horizon, anchored by historical baselines and calibrated to reflect the influence of turbine upsizing, offshore expansion, and material substitution trends.
- Segment-level analysis that separates resin categories, application types, and geographic markets without relying on overly simplified aggregates, allowing leaders to identify where growth concentration, pricing pressure, or substitution risk is most acute.
- Competitive profiling of core suppliers, examining formulation capabilities, process compatibility, geographic footprints, and recent product or pricing actions that signal shifting competitive strength.
- Market context on feedstock economics, regulatory changes, and trade policy that directly affect landed cost, procurement flexibility, and near-term pricing expectations.
- Critical concentration metrics that quantify how revenue is distributed among leading suppliers, helping organizations assess dependency risk, negotiation leverage, and supplier diversification priorities.
By weaving these components together, the report enables organizations to move beyond reactive procurement and toward proactive portfolio strategy. Whether the objective is to secure reliable supply for blade manufacturing programs, evaluate alternative resin architectures, anticipate the impact of duty regimes on sourcing decisions, or align R&D investments with OEM sustainability targets, the analysis is designed to reduce uncertainty and sharpen execution.
Conclusion: Turning Market Intelligence into Competitive Advantage
The epoxy resin segment serving wind energy is at an inflection point. Demand continues to be pulled upward by larger turbines, broader offshore deployment, and the relentless pursuit of composite performance. At the same time, the operating environment is increasingly defined by feedstock volatility, trade policy recalibration, and a competitive field in which formulation speed and circularity credentials are becoming as important as volume capacity. In such a landscape, decisions made without granular, forward-looking insight carry heightened risk of margin erosion, supply disruption, or missed innovation windows.
This research study provides the depth required to navigate that complexity. It offers a structured, evidence-based view of how the market has evolved, how it is likely to progress, and where the most consequential opportunities and vulnerabilities lie. For organizations seeking to convert market knowledge into competitive advantage in 2026, the complete analysis offers the granularity, scenario context, and strategic framing needed to act with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Epoxy Resins in Wind Energy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com