

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Global Automotive Warehouse Logistics to Reach USD 171.25 Billion in 2025, Growing at 6.72% CAGR

Global Automotive Warehouse Logistics Market: Strategic Intelligence for 2026 and Beyond
The automotive supply chain is currently navigating a period of unprecedented transformation. As manufacturers shift toward electric vehicle production, face evolving regulatory landscapes, and grapple with persistent labor constraints, the role of warehouse logistics has evolved from a backend support function to a critical strategic lever. Understanding the dynamics of this sector is no longer optional for stakeholders aiming to maintain competitiveness. PW Consulting presents this deep dive into the Worldwide Automotive Warehouse Logistics Market, designed to equip decision-makers with the foresight needed for the 2026 fiscal year and the decade ahead.
This analysis synthesizes comprehensive data spanning historical performance from 2020 through 2025 and extends robust forecasts through 2032. The objective is not merely to report numbers but to interpret the underlying forces driving value creation, risk mitigation, and operational efficiency within the global automotive logistics network.
Market Trajectory and Growth Projections
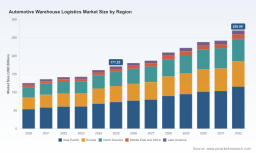
The financial arc of the automotive warehouse logistics sector demonstrates resilience and steady expansion despite macroeconomic volatility. Historical data indicates a consistent upward trend in revenue generation across the industry. Starting from a baseline in 2020, the market has navigated supply chain disruptions and recovery phases, culminating in a significant valuation by 2025. The momentum carried into the forecast period suggests sustained growth rather than a temporary spike.
Our research models project the market value to continue its ascent through 2032. The compound annual growth rate observed over the forecast horizon underscores the structural demand for specialized logistics services. This growth is not uniform; it is driven by specific shifts in manufacturing geography, vehicle complexity, and the increasing need for just-in-sequence delivery models. For enterprise leaders, this trajectory signals that investment in logistics infrastructure is aligned with long-term market expansion, offering a hedge against stagnation in other operational areas.
Segmentation Dynamics: Service Types and Component Categories
A superficial glance at market size misses the nuanced opportunities hidden within service segments. The revenue split across service types reveals where the industry's heavy lifting occurs. Inventory management and storage remain the dominant value drivers, reflecting the critical need for secure, organized holding spaces for high-value automotive assets. However, value-added services represent a substantial portion of the ecosystem, indicating a market trend toward partners who do more than store; they integrate, kit, and prepare components for immediate line-side consumption.
Distribution center operations also constitute a major pillar of the market, facilitating the movement of goods from central hubs to regional destinations. When examining component categories, the data highlights the primacy of spare parts logistics. The sheer volume and variety of parts required for maintenance and repair streams necessitate sophisticated warehousing strategies. Finished vehicle logistics form another critical segment, requiring specialized handling and transport coordination. Raw materials and components round out the triad, linking upstream manufacturing needs with downstream distribution capabilities.
Strategic allocation of resources should reflect these proportions. Organizations that prioritize capabilities in high-value segments while maintaining flexibility for component-specific requirements are better positioned to capture margin improvements. The disparity in segment sizes suggests that while volume lies in certain areas, value differentiation often comes from specialized handling and integration services.
Regional Distribution of Logistics Activity
Geography plays a defining role in logistics strategy. The Asia Pacific region stands out as a dominant hub of activity, reflecting the concentration of manufacturing capacity and vehicle production in this zone. This regional weight implies that logistics networks must be optimized for high-density throughput and cross-border coherence. Europe maintains a significant presence, driven by established OEM bases and stringent regulatory environments that shape logistics operations.
North America continues to represent a substantial share of the market, supported by a robust domestic vehicle production ecosystem and extensive distribution networks. Emerging regions, including the Middle East and Africa as well as Latin America, contribute to the global tally, offering growth potential for companies willing to invest in infrastructure development and local partnership models. Understanding the regional weight is essential for capacity planning. A logistics strategy that overlooks the dominance of certain regions may find itself misaligned with where the actual volume and value generation are occurring.
Competitive Landscape and Key Players
The market structure is characterized by a mix of global integrators and specialized logistics providers. The competitive landscape shows a concentration that suggests room for consolidation but also intense rivalry among top-tier players. Our analysis identifies the share held by the top three and top five companies, indicating that while large players dominate, a significant portion of the market remains distributed among specialized partners who compete on niche capabilities and regional expertise.
Intelligent Automatic Warehouse And Logistic Equipment Market
Leading Enterprise Profiles
Several key companies define the current operational standards and strategic directions of the sector. DHL Supply Chain, headquartered in Bonn, Germany, provides comprehensive contract warehousing and distribution solutions tailored for automotive parts and finished vehicles. Their portfolio includes specialized handling for EV components and just-in-sequence delivery, positioning them at the forefront of modern logistics requirements.
Kuehne + Nagel, based in Schindellegi, Switzerland, offers integrated automotive warehouse logistics with a strong focus on contract logistics and visibility platforms. Their emphasis on automation for OEMs and Tier suppliers highlights the industry shift toward digital transparency and automated handling. CEVA Logistics, operating from Marseille, France, specializes in customized contract warehousing and value-added services. Their strong expertise in finished vehicle logistics and parts distribution underscores the importance of end-to-end solutions that cover both new production and aftermarket flows.
DB Schenker, located in Essen, Germany, delivers land, air, ocean freight, and contract logistics services focused on automotive supply chains. Their ability to integrate warehousing with broader freight movements offers a holistic view of supply chain management. Ryder System, Inc., from Miami, USA, provides dedicated transportation, warehousing, and supply chain solutions with a significant automotive sector focus. Their capabilities in fleet management and parts distribution complement warehousing needs with transportation efficiency.
XPO Logistics, headquartered in Greenwich, USA, offers flexible warehousing, fulfillment, and less-than-truckload services supporting high-volume automotive parts and component logistics. Their flexibility appeals to manufacturers with fluctuating production schedules. DSV, based in Hedehusene, Denmark, provides global freight forwarding and contract logistics with automotive-specific warehousing and distribution capabilities, leveraging a massive network to serve complex requirements.
BLG LOGISTICS GROUP AG & Co. KG, in Bremen, Germany, acts as a specialist in automotive logistics including warehousing, vehicle processing, and technical services for OEMs. Their specialization allows for deep integration with manufacturer processes. Nippon Express Holdings, from Tokyo, Japan, offers integrated logistics solutions for automotive with an emphasis on Asia-Pacific warehousing and global parts supply chain management, crucial for bridging Eastern manufacturing with global markets. Finally, Penske Logistics, based in Reading, USA, delivers supply chain management and warehousing services optimized for automotive manufacturers and suppliers, focusing on operational excellence.
Recent Strategic Developments
Competitive moves in recent months signal where the industry is heading. In March 2026, DHL Supply Chain announced the rollout of the SVT Robotics SOFTBOT platform across its global warehouse network. This deployment aims for faster multi-robot integration supporting automotive and other sectors, demonstrating a clear commitment to accelerating automation adoption to overcome labor constraints.
Earlier, in July 2025, Nippon Yusen Kabushiki Kaisha (NYK) engaged in the joint development and full-scale implementation of an AI system with MTI and Grid. This system automates and optimizes car carrier allocation in vehicle logistics, highlighting how artificial intelligence is being deployed to solve specific allocation and efficiency problems in vehicle transport and warehousing coordination.
Worldwide Automotive Warehouse Logistics Market
Industry Dynamics Shaping 2026
Several external forces are compressing the timeline for logistics transformation. Regulatory changes are reshaping the fundamental economics of vehicle production and movement. In February 2026, the EPA finalized a rulemaking eliminating greenhouse gas standards for light-, medium-, and heavy-duty vehicles and engines. This shift alters the compliance landscape for manufacturers and, by extension, the logistics requirements for moving vehicles and parts that may have different certification profiles. Additionally, the NHTSA proposed revisions to CAFE standards on December 5, 2025, reducing the estimated light-duty fleet-wide fuel economy requirement. These regulatory adjustments influence vehicle mix and production volumes, directly impacting warehouse throughput needs.
Labor market conditions remain a critical pressure point. Labor and skills shortages rank as the second-biggest challenge in automotive manufacturing. This scarcity drives automation investment while constraining operations. For warehouse logistics providers, this means that solutions must increasingly rely on technology to mitigate headcount risks. The divide in automation adoption is stark: OEMs and Tier 1 suppliers are operating at adoption rates between 51% and 62%, while Tier 2 stands at 31% and Tier 3 at 23%. This gap suggests that downstream and upstream suppliers may face efficiency disparities that logistics partners must navigate through flexible handling and support services.
Supply chain pressures also persist. Ongoing issues include rising raw material costs and component shortages impacting automotive parts warehousing and distribution. These factors require logistics providers to maintain higher safety stocks or implement more sophisticated inventory turnover strategies to buffer against volatility. Infrastructure constraints and the need for smoother integration between physical storage and digital planning systems are becoming table stakes for service providers.
Strategic Implications for Decision Makers
For executives planning for 2026, the data points toward several actionable imperatives. First, the growth trajectory confirms that logistics is a value-creation center, not just a cost center. Investment in warehousing capabilities should be viewed through the lens of enabling production continuity and market responsiveness. Second, the segmentation data suggests that diversification of service offerings, particularly in value-added services, can insulate revenue streams from volatility in pure storage demand.
Third, the competitive landscape indicates that partnerships with providers who have proven automation roadmaps are essential. With labor shortages persisting and automation adoption varying by tier, logistics partners who can bridge this gap offer significant strategic advantage. The recent technology deployments by major players serve as benchmarks for what is achievable in terms of speed and integration.
Fourth, regional allocation of logistics resources should mirror the production geography. The heavy concentration in Asia Pacific requires dedicated attention to network resilience there, while North American and European operations must navigate specific regulatory and labor environments. Finally, the regulatory shifts regarding emissions and fuel economy standards will likely alter vehicle mix over time. Logistics strategies must remain agile enough to accommodate changes in vehicle type, size, and component composition as manufacturing priorities shift.
Conclusion and Research Utility
The Worldwide Automotive Warehouse Logistics Market is at an inflection point where scale meets sophistication. The projected growth through 2032 offers a backdrop of opportunity, but realizing value requires navigating a complex web of regional dynamics, technological adoption gaps, and regulatory changes. This report serves as a foundational tool for validating strategic assumptions and identifying high-potential areas for investment.
By integrating historical performance data with forward-looking analysis and competitor intelligence, stakeholders can move beyond generic market observations to precise, actionable strategies. The insights contained within this study are designed to support capital allocation, partnership selection, and operational planning in a volatile environment.
To access the complete dataset, detailed segmentation breakdowns, full competitor profiles, and the comprehensive forecast models referenced in this overview, please visit the PW Consulting report page. The full intelligence package provides the granular data necessary to finalize your 2026 strategic roadmap.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Warehouse Logistics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com