

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hydrogen Valve Market Hits $154.8M in 2025, 11.85% CAGR to $340.25M by 2032

Navigating the Hydrogen Pressure Reduction Landscape: Strategic Insights for 2026 and Beyond
The global transition toward low-carbon energy systems has placed hydrogen at the center of industrial, mobility, and storage infrastructure planning. Within this accelerating ecosystem, the pressure reducing valve for hydrogen bottle market has emerged as a critical enabler of safe, efficient, and compliant gas handling. As organizations align their capital allocation and product development Roadmaps for 2026, understanding the trajectory, competitive architecture, and regulatory undercurrents of this segment is no longer optional. This introduction to our latest Pressure Reducing Valve for Hydrogen Bottle Market research outlines the strategic value decision-makers can extract from a data-rich, forward-looking analysis designed specifically for enterprise planning.
Historical performance through 2025 demonstrates sustained expansion, with market revenue climbing from 82.45 million USD in 2020 to 154.8 million USD at the close of 2025. The momentum carries decisively into the forecast window. Our modeling projects the market to reach 173.27 million USD in 2026, accelerating toward 340.25 million USD by 2032, underpinned by a compound annual growth rate of 11.85 percent. These figures reflect more than incremental demand; they signal a structural shift in how high-pressure hydrogen is stored, transported, and deployed across fuel cell mobility, industrial gas storage, and refueling infrastructure. For executives evaluating market entry, capacity expansion, or technology partnerships in 2026, this trajectory provides a foundational baseline against which investment thresholds and risk parameters can be calibrated.
Yet macro growth alone does not dictate strategy. The real leverage lies in understanding how demand fractures across applications, how regional adoption patterns shape supply chain dynamics, and how product architecture preferences evolve under regulatory and material cost pressures. Our research deliberately maps these intersections without reducing them to static snapshots. Instead, it unpacks the operational implications behind each demand layer, enabling engineering, procurement, and commercial teams to align product specifications, inventory positioning, and go-to-market sequencing with actual deployment cadence.
Market Dynamics Driving 2026 Decision-Making
Several converging forces are reshaping the competitive and operational environment for hydrogen pressure reducing valves. Regulatory frameworks are tightening around high-pressure gas handling, directly influencing design validation, certification pathways, and time-to-market. The ISO 10297:2024 standard for cylinder valves was updated to include additional hydrogen compatibility testing requirements for pressure reducing valves, raising the bar for material selection, sealing integrity, and fatigue performance. Simultaneously, the EU Pressure Equipment Directive mandates that hydrogen pressure reducing valves meet Category III or IV classification for high-pressure service, adding compliance complexity for manufacturers serving European distribution channels.
Material economics introduce another layer of strategic consideration. Nickel alloy and stainless steel 316L prices increased 8 percent year-over-year in the third quarter of 2025, directly raising production costs for hydrogen pressure reducing valves. For original equipment manufacturers and valve suppliers, this shift affects margin structures, pricing architecture, and supplier negotiation strategies. Companies that approach 2026 without a clear view of material cost trajectories risk underpricing critical components or overcommitting to specifications that erode profitability at scale.
Technological differentiation is equally pronounced. The market is not monolithic; demand is distributed across product architectures that vary in complexity, application fit, and value proposition. Single-stage designs continue to hold a substantial share of the market, reflecting their suitability for straightforward pressure reduction in established hydrogen bottle workflows. Two-stage and multi-stage configurations serve more specialized use cases, where staged pressure management, leakage mitigation, or controlled delivery profiles justify additional engineering investment. Understanding which architecture aligns with which deployment scenario is essential for portfolio planning and for avoiding the common trap of over-engineering solutions that customers do not require.
Application-side demand further complicates the picture. Fuel cell vehicles, hydrogen refueling stations, industrial gas storage, and other emerging use cases each impose distinct operating conditions, certification expectations, and procurement rhythms. Refueling infrastructure, for example, often prioritizes durability under frequent cycling and rapid response, while industrial gas storage may emphasize purity, long-duration stability, and compatibility with batch handling protocols. Our research dissects these application drivers to help organizations map product capability to the precise operational demands that will shape procurement decisions in 2026.
Competitive Architecture and Strategic Positioning
The competitive landscape is populated by established industrial valve manufacturers and specialized gas-handling suppliers, each leveraging distinct footholds in engineering heritage, geographic reach, and application expertise. Emerson Electric Co. offers pressure reducing valves for high-pressure hydrogen cylinders used in industrial and energy applications, with its Tescom division specializing in high-pressure hydrogen pressure reducing valves for cylinder and bottle service. Parker Hannifin Corporation supplies hydrogen-compatible pressure reducing valves for cylinder and bottle applications in mobility and energy sectors, reinforcing its cross-industry fluid control presence. Swagelok Company manufactures high-purity pressure reducing valves for hydrogen bottle systems in laboratory and industrial gas handling, appealing to environments where contamination control and repeatability are paramount.
Rotarex S.A. provides cylinder pressure regulators and reducing valves specifically engineered for hydrogen storage and distribution, and in October 2025 it released a hydrogen-specific cylinder pressure reducing valve series for fuel cell and industrial gas applications, signaling targeted product expansion. GCE Group develops pressure reducing valves for hydrogen cylinders used in welding, industrial, and fuel cell applications; in September 2025, the company updated its hydrogen cylinder valve and regulator catalog with new pressure reducing models for high-pressure service. Swagelok also gained visibility in August 2025 by showcasing hydrogen pressure reducing valves at ACHEMA 2025 for industrial gas and energy markets, reinforcing its engagement with European industrial buyers. Ham-Let Group offers hydrogen-compatible pressure reducing valves for high-pressure gas cylinder applications, while Circor International, Inc. produces pressure regulators and reducing valves for hydrogen cylinder and bottle markets.
Market concentration reflects a moderately consolidated environment. The combined share of the top three competitors stands at 42.5 percent, while the top five reach 58.7 percent. This structure suggests that scale, brand trust, and compliance documentation carry substantial weight in procurement decisions, particularly among larger infrastructure projects and regulated industrial end users. At the same time, the remaining share dispersion leaves room for specialized entrants, regional suppliers, and application-focused innovators to compete on performance, lead time, and tailored technical support. For 2026 planning, this means competitive strategy cannot rely solely on incumbency; it must respond to differentiation vectors that matter to specific buyer segments.
What This Research Delivers for Enterprise Planning
Our Pressure Reducing Valve for Hydrogen Bottle Market research is built to translate market complexity into executable intelligence. Rather than offering a high-level overview, the report is structured around operational decision points that engineering, sales, supply chain, and corporate development teams confront when preparing for 2026 and the years that follow.
Bottle Valve Market
- Historical baseline and forecast trajectory with a detailed view of revenue progression from 2020 through 2032, enabling scenario planning around demand pacing and investment timing.
- Product architecture segmentation that clarifies how single-stage, two-stage, and multi-stage solutions are distributed across the market, helping teams align product roadmaps with real demand concentration.
- Application-driven demand analysis covering fuel cell vehicles, hydrogen refueling stations, industrial gas storage, and other use cases, supporting targeted positioning and channel strategy.
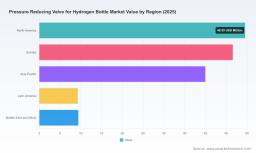
- Regional market structure insights that frame where demand is developing, how procurement patterns differ, and what localization or distribution considerations may influence execution.
- Competitive profiling of leading manufacturers, including headquarters, core offerings, and market focus, to inform benchmarking, partnership evaluation, and threat assessment.
- Recent corporate developments, such as new product launches, catalog updates, and trade show showcases, to track how competitors are reshaping their portfolios in near-real time.
- Regulatory and standards context, including hydrogen compatibility testing updates and pressure equipment classification requirements, to help teams anticipate compliance workload and design constraints.
- Material cost sensitivity analysis that connects alloy and stainless steel pricing movements to production economics, supporting margin planning and supplier strategy.
The report is designed for practical use. It helps product managers determine which performance specifications are genuinely differentiating versus merely table stakes. It assists procurement leaders in anticipating cost drivers and lead-time vulnerabilities tied to material markets and certification pipelines. It supports commercial teams in prioritizing geographies and applications where demand intensity and buyer readiness are most aligned with existing capabilities. And it gives corporate strategists a defensible basis for partnering, acquiring, or expanding into adjacent hydrogen handling components without relying on assumptions.
Why 2026 Is the Pivotal Year for Strategic Clarity
2026 represents a convergence point for several structural drivers. Hydrogen deployment is moving from pilot and early-commercial phases into more standardized operational environments, which means procurement criteria are becoming more rigorous, repeat ordering patterns are beginning to form, and compliance documentation is increasingly decisive in supplier selection. At the same time, product development cycles for pressure reducing valves are being tested by tighter standards, material cost volatility, and the need to serve multiple application archetypes without diluting manufacturing efficiency.
Organizations that enter 2026 with a clear view of demand distribution, competitive positioning, and regulatory exposure will be better equipped to sequence investments, manage risk, and capture share in a market that is expanding steadily but not uniformly. Those that rely on partial data or generic growth narratives risk misaligning product capabilities with buyer expectations, overcommitting to regions or applications with limited near-term pull, or underestimating the compliance and cost pressures that shape final procurement decisions.
The strategic value of this research lies in its ability to connect market scale with market mechanics. The headline trajectory, an 11.85 percent CAGR extending from 173.27 million USD in 2026 to 340.25 million USD by 2032, provides the macro signal. The segmentation, competitive profiles, regulatory frameworks, and recent product activity provide the operational context required to act on that signal. Together, they form a decision-ready foundation for evaluating where to compete, how to differentiate, and which execution risks deserve priority attention.
Turning Market Intelligence into Execution Advantage
For manufacturers, the immediate question is not whether hydrogen bottle pressure reduction demand is growing, but how to position product architecture, compliance readiness, and supply chain resilience to capture that growth profitably. For infrastructure developers and industrial end users, the question is how to specify valves that meet safety, purity, and durability expectations without overpaying for unnecessary complexity. For investors and corporate development teams, the question is where consolidation, specialization, or geographic expansion is most likely to create durable advantage in a market that is still maturing.
Answering these questions requires more than a top-line number. It requires a granular, structured view of how the market is composed, how competitors are moving, and how external factors are reshaping cost and compliance. Our research is built to supply that view, while preserving the detailed breakdowns that matter most when teams move from strategy to execution.
Begin the Strategic Deep Dive
This overview has outlined the market trajectory, the competitive and regulatory forces shaping 2026, and the operational content embedded in our full Pressure Reducing Valve for Hydrogen Bottle Market research. To access the complete segmentation detail, regional and application-level intelligence, competitive benchmarking, and scenario-ready forecast tables, download the full report. The macro story sets the direction; the full dataset equips your team to act on it with precision.
Pressure Reducing Valve for Hydrogen Bottle Market
For detailed analysis of this topic, please visit the official page: Pressure Reducing Valve for Hydrogen Bottle Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com