

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cell Fenders Market to Hit $225.39M in 2025, Projects 4.85% CAGR to 2032

Navigating the Next Wave: Strategic Insights into the Global Cell Fenders Market (2026–2032)
The marine infrastructure sector is at a critical inflection point. As global trade volumes stabilize and offshore energy projects accelerate, the demand for reliable vessel protection systems has never been more pronounced. At PW Consulting, we understand that navigating this landscape requires more than just top-line numbers; it demands a granular understanding of operational shifts, regulatory pressures, and competitive maneuvering. Our latest market research report on the Cell Fenders Market is designed to equip stakeholders with the intelligence needed to make informed decisions throughout the forecast period ending in 2032.
This report serves as a comprehensive navigational chart for industry participants, ranging from port authorities and shipyards to manufacturing leaders and investment analysts. By dissecting the market dynamics between the base year of 2025 and the forecast horizon, we provide a clear picture of where value is being created and where risks are lurking. The following analysis highlights the strategic value proposition of our research, offering a glimpse into the depth of data and qualitative insight available in the full publication.
Market Trajectory and Macro Growth Indicators
Understanding the historical trajectory is essential for validating future projections. Our analysis tracks revenue trends from 2020 through the base year of 2025, establishing a robust baseline for predicting performance over the next seven years. The market has demonstrated resilience, recovering from fluctuations observed in the early 2020s to reach significant momentum by 2025. This historical context allows us to model a compound annual growth rate (CAGR) of 4.85% throughout the forecast period extending to 2032.
Such growth is not merely linear; it reflects underlying shifts in maritime activity and infrastructure investment. The valuation landscape shows a clear upward trend, with market size expanding steadily as operators prioritize asset protection against increasingly larger vessels. Our report details these projections without exposing the specific revenue figures for each year, encouraging stakeholders to access the full dataset for precise budgeting and forecasting models. However, the direction is clear: the sector is poised for sustained expansion, driven by replacement cycles in aging port infrastructure and new installations in emerging maritime hubs.
For strategic planners, this growth rate suggests a compounding opportunity. Companies that position themselves now to capture market share during this growth phase will likely secure stronger footholds before the market matures further towards the end of the decade. The report quantifies this opportunity, helping clients assess whether their current capacity aligns with the projected demand surge.
Worldwide Cell Controller Market
Segmentation Dynamics: Type and Application
The Cell Fenders Market is not monolithic. It is divided by product typology and application environment, each carrying distinct profit margins and growth drivers. Our research breaks down the market into key segments including Standard Cell Fenders, Super Cell Fenders, and other specialized variants. Each segment serves different vessel sizes and operational stresses. For instance, the Super Cell category has gained prominence in high-performance marine applications where energy absorption is critical, while standard variants remain prevalent in routine port operations.
Similarly, the application landscape is diverse. Commercial ports represent a significant portion of demand, but adjacent sectors such as shipyards, docks, and offshore oil and gas platforms contribute substantially to the total revenue pool. Our analysis explores how demand variability across these applications affects manufacturers. For example, while commercial ports may offer volume stability, offshore platforms often command higher specifications and pricing power. Understanding the balance between these segments is crucial for companies deciding where to allocate R&D resources.
We avoid publishing specific percentage splits or revenue amounts for these segments in this summary to protect the proprietary nature of our modeling. Instead, we highlight that the interplay between standard and high-performance fenders is shifting. As vessels grow larger, the mix is tilting toward higher-capacity solutions. Clients accessing the full report will gain access to the specific volume and value breakdowns necessary to identify their most lucrative niche within this segmentation matrix.
Regional Landscape and Market Concentration
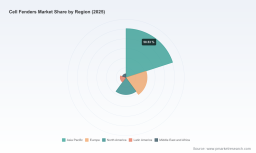
Geographically, the market is distributed across key regions including Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa. Each region presents unique challenges and opportunities. Asia Pacific continues to be a dominant force due to intense port construction and trade activity, while Europe and North America focus heavily on upgrading existing infrastructure to meet higher safety and environmental standards.
Our report examines the regional revenue distribution to highlight where growth is most concentrated. We analyze how local manufacturing capabilities versus import dependencies shape the competitive environment in each geography. For instance, regions with strong local manufacturing bases may see different pricing dynamics compared to those reliant on imported marine infrastructure solutions.
Furthermore, the market exhibits a moderate to high level of concentration among top competitors. Our data indicates that a small group of leading manufacturers controls a significant share of the global revenue stream. This concentration influences pricing power, supply chain stability, and technology adoption rates. Understanding the competitive density in specific regions helps logistics managers and procurement officers anticipate supply constraints or negotiate better terms. The full report provides detailed regional analysis that allows clients to pinpoint growth hotspots without relying on generalized global averages.
Competitive Landscape: Key Players and Strategic Moves
The competitive arena is defined by established marine engineering firms and specialized rubber manufacturers. Our report profiles key companies that are shaping the industry, including ShibataFenderTeam, Trelleborg Marine and Infrastructure, ESC Marine Systems, Lion Rubber Industries, Nanjing Deers Industrial, SunHelm Marine, Qingdao Jier Engineering Rubber, and The Rubber Company.
Each of these players brings distinct capabilities to the table. For example, ShibataFenderTeam is known for its CSS Cell Fenders with hollow cylindrical body designs, catering to high-performance needs with models reaching significant heights. Trelleborg focuses on SCK Cell Fenders, emphasizing simplicity and a long track record in protection infrastructure. ESC Marine Systems offers comprehensive systems manufactured to PIANC guidelines, while manufacturers like Nanjing Deers and SunHelm Marine are prominent in the Asia-Pacific supply chain, with SunHelm recently notable for compliance advancements.
Cell Fenders Market
Strategic moves among these entities are indicative of broader market trends. Recent industry developments highlight this dynamic. In late 2025, ShibataFenderTeam secured a major supply contract for the largest CSS3000 Cell Fenders to an FLNG facility in Malaysia, signaling confidence in large-scale offshore projects. Meanwhile, SunHelm Marine commenced production of EUDR-compliant Fixed Rubber Fenders, marking a first for the industry in China and addressing emerging regulatory requirements. Additionally, Nanjing Deers Industrial successfully delivered fender systems for replacement projects in Southeast Asia, underscoring the ongoing maintenance and upgrade cycle in established ports.
Our analysis goes beyond profiling; it evaluates how these companies are positioning themselves relative to one another. Are they competing on price, quality, or compliance? The report assesses their product portfolios, geographic reach, and recent project wins to help clients identify potential partners or competitors they may face in the marketplace.
Industry Dynamics: Regulation, Materials, and Standards
External factors are exerting significant pressure on the Cell Fenders Market. Three critical dynamics stand out in our analysis: regulatory compliance, raw material volatility, and evolving technical standards.
Regulatory Compliance: The EU Deforestation Regulation (EUDR) is a pivotal development. It requires due diligence for natural rubber products, including marine fenders, to ensure they are deforestation-free. With enforcement scheduled to begin in December 2026, manufacturers and suppliers must adapt their supply chains immediately. This regulation affects not only European operators but also global suppliers wishing to access the EU market. Our report discusses the implications of EUDR compliance costs and the potential for market exclusion for non-compliant entities.
Raw Material Costs: Natural rubber prices have experienced fluctuations, trading approximately between USD 1.40 and 1.70 per kg recently. These movements impact production costs directly. Industry data suggests that manufacturers may pass on potential price increases of around 10% to end-users. For procurement managers, understanding these cost drivers is vital for contract negotiation and budget forecasting. Our research integrates these cost pressures into the financial outlook, helping clients model sensitivity scenarios.
Technical Standards: The PIANC Fender Guidelines 2024 (WG211) update supersedes previous 2002 guidelines, introducing new design approaches. A transition period was allowed until November 2025 for supplier catalogs to adjust. This shift impacts how fenders are specified and tested. Companies that fail to align with the new standards risk obsolescence or liability issues. Our report details the scope of these changes and their impact on product design and certification requirements.
By weaving these dynamics into the market forecast, we provide a realistic view of the headwinds and tailwinds facing the industry. Ignoring these factors can lead to strategic missteps, which is why our report places them at the center of the analysis rather than treating them as footnotes.
Operational Content and Strategic Utility
Beyond market sizing and trend identification, this report is built for operational utility. It contains actionable content designed to support decision-making at various levels of an organization.
- Supplier Evaluation Frameworks: We provide criteria for assessing fender manufacturers based on capacity, compliance, and technical capability. This helps procurement teams shortlist partners who can meet both current specifications and future regulatory requirements.
- Risk Assessment Models: The report includes analysis of supply chain vulnerabilities related to raw material sourcing and geopolitical factors in key manufacturing regions. This enables risk managers to diversify sourcing strategies effectively.
- Investment Guidance: For investors looking at the marine infrastructure sector, the report delineates growth pockets and potential saturation points. It helps in identifying which sub-segments offer the best risk-adjusted returns over the forecast period.
- Strategic Planning Inputs: Executives can use the trend analysis to plan capacity expansions, R&D focus areas, and market entry strategies. The data supports scenario planning for different growth trajectories and regulatory outcomes.
We understand that data without context is merely noise. Therefore, our report integrates qualitative insights with quantitative data to tell a coherent story about the market's evolution. Whether you are a port operator planning a quay replacement or a manufacturer considering a new product line, the insights herein are tailored to reduce uncertainty.
Conclusion: The Value of Complete Intelligence
The Cell Fenders Market is evolving under the influence of stricter regulations, material cost pressures, and shifting maritime traffic patterns. Success in this environment depends on access to accurate, timely, and deep market intelligence. While this overview highlights the scope and strategic relevance of our findings, the true value lies in the specific data points, regional breakdowns, and competitive assessments contained within the full report.
Decisions made in 2026 will set the course for the remainder of the decade. Relying on outdated models or generalized industry knowledge introduces unnecessary risk. PW Consulting's Cell Fenders Market Report offers the granularity required to navigate these complexities with confidence. We invite industry leaders, investors, and strategic planners to access the complete study to unlock the full potential of these insights. The detailed segmentation data, proprietary forecasts, and comprehensive company profiles available in the full document provide the definitive guide for capitalizing on the opportunities ahead.
For detailed analysis of this topic, please visit the official page: Cell Fenders Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com