

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Synthetic Amino Acids Market Eyes USD 35,013.75 Million by 2032, 6.55% CAGR

Navigating the Synthetic Amino Acids Market: Strategic Intelligence for 2026 and Beyond
The global synthetic amino acids market stands at a critical inflection point as the decade progresses. Over the historical period from 2020 to 2025, the industry has demonstrated remarkable resilience and sustained expansion, with total market revenue climbing from approximately USD 16.4 billion to over USD 22.4 billion. Looking ahead through the forecast horizon of 2026 to 2032, the trajectory points toward a robust compound annual growth rate of 6.55 percent, ultimately positioning the market to surpass USD 35 billion by the close of the period. For executive leadership teams, procurement strategists, and R&D directors, this is not merely a macroeconomic statistic. It represents a complex landscape of shifting feedstock economics, evolving regulatory frameworks, and intensifying competitive dynamics that will directly impact margin structures, supply chain resilience, and long-term portfolio positioning.
As organizations prepare their 2026 strategic roadmaps, the ability to discern signal from noise in this sector has never been more vital. Market participants are operating in an environment where raw material price volatility intersects with regional production cost disparities, where consolidation pressure coexists with niche specialization opportunities, and where the balance between synthetic and fermentation-derived pathways continues to reshape competitive advantages. The latest comprehensive market intelligence, synthesized by PW Consulting, is designed to equip decision-makers with the granular analysis, actionable frameworks, and forward-looking scenarios required to navigate these complexities with confidence.
Macro Trajectory and the Imperative for Precision Intelligence
The eight-year forecast window reveals a market defined by steady, compounding growth rather than abrupt disruption. From a baseline of USD 24.34 billion in 2026, the sector is projected to scale progressively, crossing USD 26.60 billion in 2028, exceeding USD 29.85 billion by 2030, and reaching USD 35.01 billion in 2032. This expansion is underpinned by accelerating demand across industrial nutrition, clinical applications, and specialized chemical formulations, yet the underlying drivers vary significantly by region and end-use vertical. Understanding which segments will capture disproportionate value requires more than high-level trend extrapolation. It demands a structured dissection of production economics, pricing mechanisms, capacity utilization patterns, and the strategic responses of incumbent manufacturers.
Synthetic Vitamin E Market
Recent quarters have already highlighted the sensitivity of this market to upstream variables. Raw material inputs, including soybean oilseeds, wheat, and corn, have experienced pronounced price fluctuations driven by competing agricultural demand and logistical bottlenecks. In chemical synthesis pathways, ammonia constitutes an estimated sixty to seventy percent of operating costs for hydrogen cyanide production, making feedstock procurement a decisive factor in overall cost competitiveness. Regional pricing divergences further complicate procurement strategies, with benchmark prices in the United States, China, and Germany reflecting distinct local supply-demand balances and infrastructure constraints. Organizations that lack detailed visibility into these cost architectures risk suboptimal sourcing decisions, squeezed gross margins, and vulnerability to sudden market shifts.
Worldwide Synthetic Amino Acids Market
Regulatory scrutiny adds another layer of complexity. While synthetic amino acids remain indispensable to numerous high-value applications, certain jurisdictions are intensifying evaluations of chemically derived variants, alongside growing consumer and institutional preferences for fermentation-based or plant-sourced alternatives. Navigating this regulatory mosaic requires a nuanced grasp of compliance timelines, certification pathways, and the commercial implications of shifting procurement mandates across different territories. Strategic planning that ignores these dynamics will inevitably fall short.
Competitive Architecture: Consolidation, Specialization, and Strategic Realignment
The competitive landscape is characterized by a concentrated core of globally integrated producers alongside a diverse cohort of regional specialists and emerging capacity players. The top three firms command approximately forty-two percent of total market revenue, while the top five collectively account for just over fifty-eight percent. This concentration reflects the capital intensity of large-scale synthesis and fermentation operations, the importance of established quality certifications, and the value of entrenched customer relationships across feed, food, pharmaceutical, and nutraceutical channels. Yet concentration does not equate to stagnation. The market is actively reshaping itself through portfolio adjustments, targeted partnerships, and strategic divestitures that redefine competitive positioning.
Leading global players such as Ajinomoto Co., Inc. and Evonik Industries AG continue to anchor the industry through extensive production networks and diversified product portfolios. Ajinomoto leverages decades of fermentation and chemical synthesis expertise to supply high-purity synthetic and feed-grade amino acids, including methionine, lysine, threonine, and tryptophan, across animal nutrition, food, and pharmaceutical applications. Evonik, meanwhile, has sharpened its strategic focus on specialty chemicals for precision animal nutrition, offering flagship products like MetAMINO, Biolys, and ThreAMINO while integrating sustainability metrics into its operational framework. Notably, Evonik has recently undertaken a restructuring of its keto and pharmaceutical amino acid business, discontinuing certain legacy operations while simultaneously expanding its GMP-certified portfolio for clinical and pharmaceutical customers in Europe and North America. This dual move illustrates how incumbents are actively pruning legacy exposures to double down on higher-margin, compliance-intensive segments.
In Asia, major integrated producers are scaling capacity to meet both domestic and export demand. CJ CheilJedang Corporation and Daesang Corporation from South Korea, alongside large-scale Chinese manufacturers such as Fufeng Group Limited and Meihua Holdings Group Co., Ltd., have built substantial production footprints for lysine and other feed-grade amino acids. These organizations benefit from proximity to key agricultural feedstocks and increasingly sophisticated manufacturing capabilities. Their growth strategies often hinge on balancing volume-driven feed applications with higher-value food and nutraceutical segments, requiring careful calibration of production allocation and pricing architecture.
Parallel to these volume-oriented players, a distinct tier of high-purity specialists is carving out defensible niches. Amino GmbH, Kyowa Hakko Bio Co., Ltd., and Wacker Chemie AG focus on pharmaceutical, biotech, and specialty-grade synthetic amino acids, where regulatory compliance, batch consistency, and customized formulation capabilities command premium positioning. The strategic alignment between Croda International and Amino GmbH, announced in late 2025, exemplifies the trend toward collaboration between specialty suppliers and broader life sciences portfolios, reinforcing the value of targeted manufacturing partnerships for pharmaceutical-grade supply chains. Sumitomo Chemical Co., Ltd. further contributes to this ecosystem through its chemical synthesis capabilities, supporting industrial and pharmaceutical applications that demand precise intermediate and derivative production. ADM, as a diversified agribusiness, integrates amino acid production into a broader nutrition portfolio, leveraging scale and cross-segment synergies to serve feed and food customers.
For 2026 planning, the critical takeaway is that competitive advantage will not be determined solely by capacity size. It will increasingly depend on portfolio flexibility, regulatory readiness, sourcing resilience in the face of feedstock volatility, and the ability to align product grades with the most attractive margin pools. Organizations that attempt to compete across all segments without clear differentiation risk compression from both consolidated incumbents and agile specialists.
Inside Our Worldwide Synthetic Amino Acids Market Research
The newly released PW Consulting market research report is built to translate these macroeconomic signals and competitive shifts into actionable corporate strategy. Rather than offering surface-level trend summaries, the study provides a comprehensive operational playbook structured around the decision points that matter most to 2026 planning cycles. The analysis begins with a rigorous reconstructed historical baseline spanning 2020 through 2025, establishing a transparent foundation for the forecast model that extends through 2032. This historical reconstruction is not merely a retrospective exercise. It serves as a diagnostic tool to identify inflection points, validate growth assumptions, and isolate the structural factors that have consistently influenced revenue generation across different product grades and end-use channels.
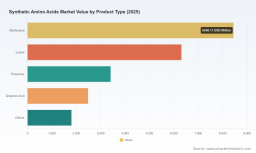
A core strength of the report is its detailed segmentation architecture, which dissects the market across product types, application verticals, and regional demand centers without sacrificing analytical depth. Decision-makers will find focused assessments of methionine, lysine, threonine, glutamic acid, and other amino acid categories, each evaluated through the lens of demand drivers, production technology pathways, pricing behavior, and margin dynamics. The application-side analysis examines how animal feed, food and beverages, pharmaceuticals, and nutraceuticals and cosmetics utilize synthetic amino acids, highlighting the distinct procurement criteria, regulatory hurdles, and value proposition thresholds that define each vertical. By mapping these segments against the broader forecast trajectory, the report enables users to pinpoint where volume growth, value growth, and margin expansion are most likely to converge, and where commoditization pressures may erode returns.
Regional analysis is presented with an emphasis on competitive intensity, production cost structures, and demand localization rather than simplistic market share rankings. The study explores how Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa differ in terms of feedstock access, manufacturing maturity, regulatory environments, and downstream consumption patterns. This geographic granularity is essential for organizations evaluating capacity expansion, export strategies, or supply chain diversification, as it surfaces the relative attractiveness of different operating environments under varying commodity price and trade policy scenarios.
Beyond segmentation, the report delivers a thorough competitive profiling exercise that maps the strategic postures, technological capabilities, and recent operational moves of the leading participants shaping the market. Each profiled company is assessed for its production methodology focus, product grade coverage, geographic reach, and recent portfolio or restructuring actions. This competitive intelligence is contextualized within broader industry dynamics, including capacity utilization trends, innovation pipelines, and alliance activity, enabling readers to anticipate how rival strategies may alter pricing power, channel access, or customer loyalty in the near term. The inclusion of recent developments, such as GMP portfolio expansions, specialized manufacturing partnerships, and targeted business line restructurings, ensures that the analysis reflects the market as it is actively evolving, not as it existed in prior cycles.
The report also tackles the operational and financial variables that frequently determine whether strategic initiatives succeed or stall. Dedicated sections examine the impact of raw material price volatility, ammonia cost exposure in chemical synthesis routes, and regional pricing differentials on procurement optimization and cost management. These insights are paired with practical frameworks for evaluating make-versus-buy decisions, qualifying alternative suppliers, and structuring hedging or long-term contracting strategies that mitigate exposure to unpredictable input markets. Regulatory considerations are addressed with equal rigor, outlining the implications of compliance scrutiny on synthetic variants, the growing relevance of certification standards across pharma and nutraceutical applications, and the strategic trade-offs involved in balancing synthetic efficiency against shifting preferences for fermentation-derived alternatives in certain customer segments.
Finally, the study is designed with scenario flexibility in mind. Recognizing that macroeconomic conditions, trade flows, and regulatory timelines can shift rapidly, the analytical framework supports multiple planning assumptions. Users can stress-test their strategies against variations in feedstock pricing, regional demand acceleration or deceleration, and changes in competitive concentration. This scenario-oriented approach ensures that the intelligence is not static but functions as a living decision-support tool throughout the 2026 planning and execution cycle.
Strategic Imperatives for 2026 Decision-Makers
Translating market intelligence into competitive advantage requires disciplined prioritization. The following strategic considerations emerge as central for organizations positioning themselves in the synthetic amino acids market over the coming year:
- Align product grade portfolios with margin pools rather than volume alone. High-purity pharmaceutical, nutraceutical, and specialty-grade applications increasingly reward compliance readiness, batch consistency, and customization capabilities, while bulk feed-grade segments remain highly price-sensitive and structurally competitive. Evaluating where your organization can credibly compete on quality and where it must compete on cost is essential for resource allocation.
- Build feedstock resilience into procurement and production planning. Given the sensitivity of operating costs to agricultural commodity fluctuations and ammonia price exposure in certain synthesis routes, companies should evaluate diversified sourcing options, regional cost arbitrage opportunities, and contractual structures that reduce vulnerability to sudden input shocks.
- Anticipate regulatory divergence across territories. As scrutiny of synthetic variants and preferences for fermentation-based alternatives continue to evolve, market participants must monitor compliance requirements, certification timelines, and customer procurement mandates by region. Early alignment with regulatory trends can safeguard market access while late reactions risk stranded capacity or lost contracts.
- Assess competitive moves as strategic signals, not just operational events. Portfolio expansions into GMP-certified applications, divestitures of low-margin legacy lines, and targeted partnerships for pharmaceutical-grade manufacturing all indicate where value is migrating within the industry. Tracking these moves enables proactive positioning rather than reactive catch-up.
- Use regionally nuanced analysis to guide capacity and distribution decisions. Demand density, logistics costs, local feedstock advantages, and regulatory climates vary substantially across markets. A one-size-fits-all expansion or sourcing strategy will underperform relative to a geographically calibrated approach that accounts for these differences.
Accessing the Complete Intelligence Architecture
The synthetic amino acids market in 2026 will reward organizations that combine strategic clarity with operational precision. Sustained growth, competitive concentration, feedstock complexity, and evolving regulatory expectations create an environment where high-level summaries are insufficient, and boutique intuition is too risky. Decision-makers require a structured, data-anchored analysis that connects macro forecasts to segment-level dynamics, competitive behavior, and actionable planning frameworks.
This article has provided a strategic preview of the themes, structural forces, and competitive shifts that define the current market landscape. The full dataset, detailed segment assessments, regional breakdowns, competitive profiles, pricing and cost analyses, and scenario-based planning tools are available in the complete PW Consulting Worldwide Synthetic Amino Acids Market research report. Readers seeking to translate these insights into concrete 2026 decisions, including capacity planning, sourcing optimization, portfolio rebalancing, and competitive positioning, are encouraged to access the full study for comprehensive intelligence and granular market data.
For detailed analysis of this topic, please visit the official page: Worldwide Synthetic Amino Acids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com