

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Reports Push-up Paperboard Tube Market to Hit $261.96M by 2032 with 7.36% CAGR

Strategic Intelligence for Sustainable Packaging: Inside the Global Push-up Paperboard Tube Market Forecast 2026-2032
The packaging industry is currently witnessing one of the most significant structural shifts in decades, driven largely by regulatory pressure and consumer sentiment regarding plastic elimination. At the center of this transformation is the push-up paperboard tube, a format that has evolved rapidly from niche alternatives in personal care to a mainstream standard for cosmetics, food, and pharmaceuticals. For executives and supply chain strategists, the 2026 fiscal year represents a critical consolidation point. Whether optimizing procurement or assessing entry into sustainable packaging, understanding the trajectory of push-up paperboard tubes is essential for competitive positioning.
The latest market research released by PW Consulting provides a comprehensive view of this evolving landscape. Drawing on historical data from 2020 through 2025 and projecting forward to 2032, this analysis offers more than surface-level observations. It delivers the analytical rigor required to navigate a market defined by volatility in raw material costs and an increasingly complex regulatory environment. This article outlines the strategic value embedded within the full report, highlighting why immediate access to these insights is necessary for informed 2026 decision-making.
Macro Market Trajectory: Momentum and Valuation
Understanding the scale of opportunity is the first step in strategic planning. The global push-up paperboard tube market has demonstrated a consistent and robust upward trajectory. Over the historical period from 2020 to 2025, the market moved from a valuation of approximately 111.45 million USD to 159.34 million USD. This growth signals more than just a temporary trend; it indicates a structural adoption of paperboard over plastic alternatives across multiple verticals.
Looking ahead, the forecast period from 2026 to 2032 suggests continued expansion. The market is projected to cross 175 million USD in 2026, accelerating toward a valuation of over 261 million USD by 2032. This translates to a compound annual growth rate (CAGR) of 7.36 percent. For strategic planners, this rate underscores the speed at which demand is scaling. It is not merely a linear increase but a momentum driven by fundamental shifts in material preference. The revenue unit remains in millions of USD, providing a clear benchmark for ROI calculations and market entry assessments.
However, raw growth numbers only tell part of the story. The real strategic value lies in understanding where the growth is concentrated and who is capturing value. The full report deconstructs these revenue streams without leaving decision-makers to guess at the drivers behind the headlines.
Segmenting the Opportunity: Material, Application, and Region
Strategic success in the packaging sector depends on precise segmentation. The report provides a granular breakdown of the market by material type, end-use application, and geographic region, allowing firms to identify their specific niche within the broader ecosystem.
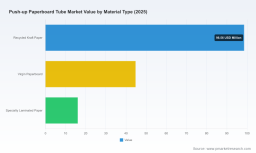
Material type analysis reveals a clear preference hierarchy that dictates supplier selection and procurement strategy. Recycled kraft paper continues to dominate the landscape, reflecting the industry-wide push toward circularity and waste reduction. Virgin paperboard maintains a significant presence, particularly where structural integrity or specific cosmetic finishes are required. Specialty laminated paper rounds out the options, often serving high-performance needs where moisture resistance or barrier properties are critical. Each material type carries different cost implications and sustainability credentials, and the report details the revenue share and dynamics for each, enabling buyers to align material choices with corporate sustainability goals.
End-use application segmentation highlights where the demand is most intense. The cosmetics and personal care sector remains the primary driver of demand for push-up tubes, leveraging the format for lip balms, deodorants, and solid cosmetics. Food and beverage applications represent a distinct and growing segment, often driven by regulatory bans on single-use plastics. Pharmaceuticals and health applications add another layer of complexity, requiring specific certifications and barrier properties. By isolating these application streams, the report helps businesses pinpoint which verticals offer the highest growth potential relative to their existing capabilities.
Regional analysis further refines the strategic picture. The market is distributed across Europe, North America, Asia Pacific, Latin America, and the Middle East and Africa. While aggregate regional figures are available in the full dataset, the key takeaway for planners is the variation in maturity and regulatory pressure across these zones. Europe's strong position reflects its early adoption of extended producer responsibility laws, while North America shows dynamic growth linked to state-level EPR expansions. Asia Pacific presents both a manufacturing hub and a growing consumption market. The full report provides the detailed regional revenue splits necessary to model supply chain logistics, tariff exposures, and local market entry strategies.
Worldwide Push-up Paperboard Tube Market
Competitive Landscape: Navigating a Fragmented Ecosystem
The push-up paperboard tube market is characterized by a moderately concentrated competitive landscape. With a CR3 of 18.45 percent and a CR5 of 27.12 percent, no single entity dominates the entire value chain, suggesting ample opportunity for specialized players and regional leaders to thrive. This fragmentation also means that procurement strategies must be sophisticated, balancing quality, customization, and geographic proximity.
Several key companies define the current competitive dynamics, each bringing distinct strengths to the table. Premier Paper Tube, based in Chicago, USA, has carved out a position by offering 100 percent fiber tubes that are PFAS-free and compostable, with a strong focus on customization for cosmetic applications. Similarly, Visican in the UK provides custom eco-friendly cardboard tubes with brandable finishes, catering to brands seeking aesthetic differentiation alongside sustainability. The Packaging Company and GreenWay Containers in the USA both emphasize biodegradable and plastic-free kraft paper solutions, appealing to the zero-waste consumer segment.
Cross-border players add complexity to the sourcing landscape. UCPACK, operating with UK and China capabilities, offers FDA greaseproof and food-grade options with FSC and ISO 9001 certifications, bridging the gap between compliance and customization. In the manufacturing hub of China, companies like All Paper Tube in Shenzhen, MC Packagings, and Fortress Packaging represent the scale and variety available from Asian suppliers, offering wholesale volumes and extensive custom printing options. Fortress Packaging, in particular, highlights the capacity for large-scale biodegradable kraft paper production. Meanwhile, US-based suppliers like SKS Bottle and Packaging and Paper Tube Co. continue to serve the domestic market with ready-made and flush-fit solutions designed to remove plastic from the supply chain.
The full report goes beyond company profiles to analyze how these players are positioning themselves, their capacity constraints, and the strategic implications of sourcing from different regions. For procurement officers, this competitive intelligence is vital for mitigating supply risk and negotiating favorable terms.
Market Dynamics: Regulations, Costs, and Raw Material Volatility
No strategic forecast is complete without addressing the external forces that can disrupt margins and timelines. The 2026 outlook is heavily influenced by regulatory shifts and raw material price fluctuations, both of which are covered in depth within the research.
Worldwide Skin Care Products Tubes Market
Regulation is perhaps the most powerful driver in this market. In the United States, EPR laws have already been enacted in seven states, including California, Colorado, Maryland, Maine, Minnesota, Oregon, and Washington. These laws require producers to manage the collection, recycling, and end-of-life of packaging materials, with fee schedules and implementation details evolving throughout 2026. Furthermore, additional states such as Wisconsin and New Hampshire have introduced packaging EPR bills in late 2025 and early 2026. This patchwork of legislation creates a complex compliance environment that varies by jurisdiction, directly impacting the cost and feasibility of packaging choices. The report analyzes how these regulations are reshaping demand for paperboard tubes as brands seek to minimize EPR fees and liabilities.
Raw material costs present another layer of uncertainty. Data from the Federal Reserve Economic Data indicates that the US Producer Price Index for folding paperboard boxes and packaging components reached 143.503 in March 2026, signaling persistent inflationary pressure in the packaging sector. Regional price disparities also exist; paper board prices in Northeast Asia were observed at 0.22 USD/Kg, while European prices stood at 0.24 USD/Kg in early 2026. Additionally, packaging paper prices in 2025 rose on average by 2.6 percent compared to 2024 levels, with recovered paper prices up by 4.5 percent in the recent period. These fluctuations affect the bottom line for manufacturers and consumers alike. The full report integrates these cost dynamics into the market valuation, helping buyers forecast procurement budgets and hedge against price volatility.
Report Content and Methodology: Actionable Intelligence for 2026
The Worldwide Push-up Paperboard Tube Market report is designed to be a practical tool for strategic planning, not just a data repository. The document covers the base year of 2025 and historical years from 2020 to 2025, providing a solid foundation for trend analysis. The forecast period extends through 2032, allowing for long-term capital allocation and product lifecycle planning.
Readers of the full report will find detailed breakdowns that are essential for building business cases. This includes precise revenue valuations for each segment, allowing for accurate market sizing and share analysis. The segmentation data covers region, material type, and end-use application, providing the granularity needed to identify high-growth niches. The competitive landscape section offers profiles of key players, their headquarters, and their operational focus, giving context to the CR3 and CR5 concentration metrics.
Moreover, the report contextualizes the data within the broader industry environment. By incorporating recent developments in raw material costs and regulatory frameworks, the analysis helps stakeholders stress-test their strategies. Whether a company is evaluating a supplier switch, launching a new eco-friendly product line, or entering a new geographic market, the report provides the evidence base required to support these initiatives. The methodology ensures that all figures are consistent and comparable, reducing the risk of misinformed decisions based on fragmented data sources.
Strategic Takeaways for Decision Makers
As the market moves toward a valuation exceeding 261 million USD by 2032, the window for strategic positioning is open but narrowing. The combination of a 7.36 percent CAGR, evolving EPR regulations, and raw material inflation means that indecision carries a cost. Brands that lock in sustainable packaging solutions early may benefit from supply security and regulatory compliance, while late movers may face higher costs and capacity constraints.
The insights within this market research enable leaders to answer critical questions: Which material type offers the best balance of cost and sustainability for your specific application? How do regional regulations in the US and Europe impact your total cost of ownership? What is the competitive capacity landscape, and where are the bottlenecks likely to emerge? By accessing the full report, stakeholders gain the granular data necessary to transform these macro trends into micro-level actions.
The push-up paperboard tube market is not just about packaging; it is about aligning product delivery with a rapidly changing expectations of environmental stewardship and regulatory compliance. For those ready to move beyond general market awareness into precise strategic execution, the detailed intelligence contained in this report is indispensable. Accessing the full analysis ensures that your 2026 planning is grounded in the most current and comprehensive data available.
For the complete dataset, including all regional revenue splits, segment valuations, and competitive profiles, we invite you to explore the full Worldwide Push-up Paperboard Tube Market report. Equip your organization with the intelligence needed to lead in the sustainable packaging era.
For detailed analysis of this topic, please visit the official page: Worldwide Push-up Paperboard Tube Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com