

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Regatta Buoys Market to Hit $190.81M by 2032 at 6.54% CAGR
By pmarketresearch, 2026-09-17
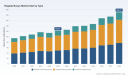
Global Regatta Buoys Market 2026–2032: Strategic Intelligence for Nautical Event Stakeholders
The Worldwide Regatta Buoys Market is entering a decisive growth cycle. As the nautical sports ecosystem expands beyond traditional sailing into rowing, paddle disciplines, and large-scale marine festivals, the infrastructure that defines competitive courses is undergoing a parallel transformation. Our latest market research, Worldwide Regatta Buoys Market, maps this evolution with a forensic lens on technology adoption, supply chain resilience, and competitive positioning. For executives, procurement leaders, and event organizers operating in 2026 and beyond, this report is not a retrospective summary—it is a forward-looking decision architecture.
Worldwide Regatta Buoys Market
Beacon Buoys Market
Between 2020 and 2025, the market demonstrated a clear recovery and expansion trajectory following early disruption cycles, with revenues climbing steadily to an estimated USD 122.45 million in our base year. Looking ahead, the forecast window from 2026 through 2032 projects sustained momentum, anchored by a compound annual growth rate of 6.54 percent. By the close of the outlook period, total market revenue is projected to approach the USD 190 million threshold. These figures are not abstract statistics; they represent a structural shift in how races are marked, managed, and experienced across global waterways. What separates this analysis from conventional industry tallies is the deliberate focus on operational inflection points: the migration from anchor-dependent layouts to autonomous positioning systems, the material science driving longevity in harsh marine environments, and the regulatory pacing that dictates event deployment timelines.
The 2026 Decision Lens: Why Timing Matters
Firms that treat buoy procurement as a commoditized purchasing exercise are increasingly exposed to hidden costs. Traditional deployment models rely on heavy anchor systems, manual course alignment, and reactive replacement cycles. Each of these steps introduces labor premiums, fuel consumption, and positioning drift that erode both budget predictability and race-day reliability. The 2026–2032 forecast window captures a market where these pain points are being systematically addressed through robotic GPS-controlled buoys and higher-durability inflatable architectures. Decision-makers who understand the cadence of this transition can align capital planning, vendor partnerships, and event scheduling before competitor organizations lock in early-mover advantages.
This research is engineered to answer three executive-level questions that generic market sizing cannot resolve. First, where is the revenue gravity shifting as event formats diversify across sailing, rowing, paddling, and festival environments? Second, which sub-segments command the highest strategic relevance for procurement and product development, and how do their relative weightings inform resource allocation? Third, what competitive asymmetries are emerging among manufacturers who are scaling customization, reducing maintenance footprints, and embedding autonomous navigation into routine race operations? By addressing these questions without resorting to superficial percentage breakdowns, the report equips leadership teams to prioritize investments that compound over the forecast horizon rather than deliver a single-season tactical fix.
Report Architecture: Operational Intelligence Over Static Sizing
A robust market study must bridge the gap between high-level revenue projections and the practical realities of on-water deployment. Our Worldwide Regatta Buoys Market report is structured to deliver exactly that bridge. The analysis begins with a diagnostic of market concentration dynamics, revealing how consolidated the competitive field has become and where fragmentation still creates entry opportunities. From there, the research decomposes the ecosystem across three interlocking dimensions: product architecture, geographic demand distribution, and end-use application profiles.
The segmentation framework is deliberately granular in scope but disciplined in delivery. Readers receive a structured assessment of how robotic positioning buoys, inflatable racing marks, and traditional rigid buoys each serve distinct operational requirements, durability expectations, and visibility standards. Rather than reducing these categories to isolated share figures, the report evaluates them through total addressable demand, replacement cycle economics, and performance trade-offs that event organizers and manufacturers face in live conditions. This approach ensures that procurement teams can benchmark specifications against real deployment scenarios, while product leaders can identify which design attributes—UV stabilization, tensile fabric strength, color contrast, inflation reliability, or autonomous holding capability—are driving purchasing preference in each context.
Geographic coverage is treated with equal analytical rigor. The research traces how regional event calendars, regulatory environments, and maritime traditions shape localized demand patterns, without reducing complex territories to static snapshots. Similarly, the application analysis maps how core regatta and yachting competitions interact with secondary growth vectors such as rowing and paddling sports and broader marine events and festivals. By presenting these layers as interconnected demand drivers rather than independent silos, the report helps organizations model scenario-based revenue pathways, anticipate substitution effects, and plan for the burden of multi-sport event programming on buoy fleets.
Competitive Landscape: Scale, Specialization, and Autonomy
The supplier landscape in regatta buoy manufacturing reflects a blend of established marine equipment brands, regional fabricators, and technology-forward entrants redefining course-marking logistics. Leading generalist and specialist players such as Plastimo, Crewsaver, Certec, ETP Race Marks, Osculati, and G.F.N. SRL anchor the traditional and inflatable segments, each bringing distinct strengths in material construction, color visibility, and event-specific form factors. Plastimo, for instance, has built a reputation around large-format inflatable marks in high-visibility PVC with practical field features, while Crewsaver and Certec emphasize cylindrical and conical inflatable designs optimized for sailing and watersport visibility. ETP Race Marks differentiates through custom fabrication capabilities spanning varied shapes, sizes, and print options, supporting event organizers who need tailored marking solutions for yachts, triathlons, and open-water competitions.
Parallel to this established base, a next-generation cohort is reshaping expectations around course precision and labor efficiency. MarkSetBot and WaterSportMarks exemplify the shift toward self-propelled, GPS-controlled sailing marks that maintain position without conventional anchoring. MarkSetBot’s recent product iteration introduced enhancements targeting race-day performance, on-water operation, and lower maintenance requirements—an evolution that directly addresses the operational friction historically associated with anchor deployment and repositioning. WaterSportMarks complements this trajectory with robotic GPS-controlled buoys engineered for effortless anchoring and autonomous positioning, reducing setup time and improving course integrity under variable water conditions. These systems are not merely convenience upgrades; they are becoming strategic assets for events where scheduling precision, environmental stewardship, and repeatable course geometry carry competitive and reputational weight.
The competitive dynamics also feature regional specialists such as Flexitank and TurtlePac, whose inflatable buoy offerings support regattas and water sports events with flexible sizing and material choices, including PVC-free alternatives. This diversification matters because procurement decisions increasingly weigh longevity, environmental compliance, and visibility alongside unit cost. Suppliers capable of harmonizing durability with ecological considerations are gaining traction, particularly as event organizers and regulatory bodies scrutinize waste, degradation, and marine compatibility. In this environment, competitive advantage is shifting from volume alone toward solution reliability, customization responsiveness, and the ability to support event teams through setup, recovery, and maintenance workflows.
Market Dynamics: Materials, Regulation, and Automation
Three intersecting forces are defining the operating environment for regatta buoys through the forecast period. The first is materials engineering. Modern regatta buoys are predominantly constructed from UV-stabilized polyethylene or high-tenancy PVC tarpaulin, with specifications commonly calibrated around durable fabric weights and resistance profiles designed to withstand prolonged sun exposure, abrasion, and saltwater conditions. Inflatable variants increasingly incorporate high-visibility color treatments and, in some product lines, PVC-free formulations to align with environmental expectations and marine stewardship goals. For procurement leaders, these material choices translate directly into service life, replacement frequency, and total cost of ownership, making specification literacy a competitive necessity rather than a back-office detail.
The second force is regulatory pacing. Marine events, including regattas, operate within layered authorization frameworks that can dictate lead times, waterway access, and operational compliance. Requirements such as advance permitting for boat races on state waters illustrate how event planning is gated by procedural timelines that procurement and logistics teams must accommodate well before race week. These regulatory rhythms influence not only when buoy fleets must be provisioned and positioned, but also how standardized, traceable, and reliably deployable those systems need to be. Organizations that integrate permitting calendars into their equipment planning reduce the risk of last-minute substitution, rushed logistics, and course-design compromises.
The third force is automation. The growing adoption of GPS-controlled robotic buoys is reducing dependence on traditional anchoring, with measurable implications for setup speed, fuel usage, and positioning accuracy. By holding position autonomously, these systems allow race committees to adjust courses in near real time, respond to shifting wind or current patterns, and minimize the physical footprint of course-laying operations. The strategic significance extends beyond efficiency metrics: autonomous marking supports more complex course geometries, enables faster recovery and redeployment between race legs, and improves repeatability for multi-day events where course consistency directly affects fairness and spectator experience. As these platforms mature, they are becoming central to event operational models rather than niche add-ons.
2026 and Beyond: Positioning for the Intelligence Gap
The Worldwide Regatta Buoys Market is not merely expanding; it is reconfiguring around autonomy, material durability, custom event integration, and regulatory-aligned planning. For organizations operating in this space, the difference between reactive spending and strategic advantage will come down to the quality of market intelligence available at the point of decision. Our research is built to close that gap. It consolidates demand trajectories, competitive positioning, application-level demand drivers, and operational dynamics into a single analytical framework that can be used for procurement planning, product roadmap prioritization, partnership strategy, and event-operations forecasting.
The full report delivers the segmented breakdowns, regional demand patterns, application weightings, concentration metrics, and company-level competitive profiles necessary to translate macro trends into executable strategy. It also contextualizes recent developments—such as autonomous buoy deployments in high-profile competitive settings and refreshed product generations aimed at race-day performance and maintenance reduction—within the broader forecast narrative. For leaders who need to validate assumptions, benchmark vendor capabilities, and model growth pathways through 2032, this intelligence offers a structured path from observation to action.
To access the complete dataset, detailed segmentation evaluations, competitive profiles, and forward-looking scenario analysis, explore the full Worldwide Regatta Buoys Market research. The executive summary provided here is designed to demonstrate analytical depth and strategic relevance; the complete study is where the numbers, comparisons, and deployment frameworks that support confident 2026 planning are fully realized.
For detailed analysis of this topic, please visit the official page: Worldwide Regatta Buoys Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bioprocessing Data Analytics Market Hits $680M in 2025, Poised for 12.5% CAGR to $1.55B by 2032
By pmarketresearch, 2026-09-17
Bioprocessing Data Analytics Software: Navigating the Next Wave of Market Intelligence
Executive Overview
The bioprocessing industry is undergoing a fundamental shift in how data is captured, analyzed, and acted upon. As biologics development cycles shorten and manufacturing complexity increases, organizations are moving from isolated laboratory systems toward integrated analytics platforms that span the entire value chain. Our latest market research on the Bioprocessing Data Analytics Software Market offers a structured, forward-looking view of this transition, designed specifically to inform capital allocation, technology roadmapping, and partnership strategy through 2032.
This article serves as a strategic preview of the full study. It highlights the macro trajectory, the operational drivers reshaping procurement decisions, the competitive architectures that buyers should monitor, and the regulatory currents that are quietly redefining software requirements. For teams preparing budgets, evaluating vendor shortlists, or building digital manufacturing strategies for 2026, this intelligence provides the context needed to move from reactive spending to deliberate investment.
Bioprocessing Data Analytics Software Market
Market Trajectory: From Steady Growth to Accelerated Scaling
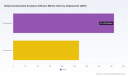
The market has demonstrated consistent expansion over the past half-decade, with revenue climbing from approximately 377 million USD in 2020 to a projected 762.72 million USD in 2026. The base year of 2025 is estimated near 680 million USD, reflecting a sector that has absorbed multiple rounds of technological maturation, broader cloud adoption, and increasing regulatory pressure for data integrity across GxP workflows. Looking forward, our forecast model projects the market to surpass 844 million USD in 2027 and continue upward through 2032, reaching an estimated 1.55 billion USD by the close of the forecast period.
The compound annual growth rate measured across the 2026-2032 window is tracked at 12.5 percent. This pace is not merely a reflection of incremental software adoption; it signals a structural change in how biomanufacturers view analytics as a core operational capability rather than a supportive tool. Early historical years showed steady double-digit movement, and the acceleration in the near-term outlook aligns with the convergence of automation, multivariate analysis, and AI-ready dataset construction. Organizations that treat these platforms as long-term infrastructure investments are positioning themselves for more predictable process performance, faster tech transfer, and stronger compliance posture.
Strategic Drivers Shaping 2026 Decision-Making
Several interlocking forces are converging to reshape procurement priorities for bioprocessing analytics software. Understanding these drivers is essential for any team evaluating purchase timing, scope of deployment, or integration requirements.
-
Regulatory expectations for data integrity are intensifying. Software solutions deployed in bioprocessing environments must align with FDA 21 CFR Part 11 requirements for electronic records, audit trails, and data integrity within GxP settings. At the same time, EU GMP Annex 1 revisions emphasize risk-based approaches and sterile manufacturing controls, increasing demand for validated analytics platforms that can demonstrate traceability, controlled access, and robust dataset governance. These requirements are no longer peripheral compliance concerns; they are becoming central selection criteria that influence architecture, deployment models, and vendor due diligence.
-
Process Analytical Technology frameworks are normalizing real-time monitoring. FDA guidance on PAT encourages real-time monitoring and multivariate analysis in bioprocessing, pushing organizations toward tools that can support continuous measurement, feedback loops, and predictive modeling. Buyers are increasingly evaluating platforms not only for retrospective reporting but also for their ability to feed live process signals into decision workflows and to support QbD-oriented development programs.
-
The clinical and commercial pipeline is demanding faster, more reproducible outcomes. As molecule complexity rises and CDMO collaboration expands, manufacturers need analytics that can span process development, manufacturing, and quality functions without fragmentation. Teams are seeking platforms that reduce manual reconciliation across online, at-line, and offline data streams, while enabling cross-run analysis and structured data handoffs between development and production.
-
AI and natural language interfaces are lowering the barrier to advanced analytics. Recent product launches and software releases indicate an industry-wide push toward more intuitive interaction models, including conversational interfaces and automated insight generation. This trend is broadening the actionable user base beyond dedicated data scientists, allowing process engineers, quality teams, and manufacturing leads to engage directly with analytics outputs.
These dynamics do not operate in isolation. Regulatory pressure raises the compliance floor, PAT frameworks raise the analytical ceiling, and pipeline urgency raises the cost of delay. Together, they create a market environment where the strategic question is no longer whether to invest in analytics software, but how to select, integrate, and scale it in a way that supports both near-term operational wins and long-term data architecture resilience.
What the Full Study Delivers: A Practical Toolkit for Strategy Teams
Our report is constructed to move beyond high-level trends and offer directly usable market intelligence. It is organized to support multiple internal workflows, including technology sourcing, competitive benchmarking, M&A scouting, and regional expansion planning. The study combines macro market sizing with deep operational context so that decision-makers can connect market trajectory to their own execution plans.
Key components of the research include:
-
Historical and forecast market sizing with scenario-aware context. The report maps revenue evolution across the historical window and extends through the full forecast horizon, providing a structured view of growth inflection points and the factors that shape them. Rather than presenting numbers in isolation, the analysis ties sizing to adoption patterns, deployment shifts, and functional demand trends that explain why the market is moving as it does.
-
Segment-level evaluation across deployment and application dimensions. The study breaks the market into meaningful structural categories, including cloud-based and on-premises deployment paths, as well as application areas such as process development, manufacturing and production, and quality and regulatory compliance. This segmentation is used to identify where demand is concentrating, what use cases are accelerating adoption, and how different organizational maturity levels influence purchasing behavior.
-
Deployment and architecture considerations for enterprise buyers. Because bioprocessing data environments often span legacy instruments, LIMS/ELN systems, MES integration points, and cross-site data flows, the report evaluates how platform architecture influences scalability, validation effort, and long-term maintainability. These discussions are intended to help buyers align software selection with their broader digital manufacturing roadmap.
-
Competitive positioning and vendor strategy mapping. The analysis examines how leading providers differentiate through platform scope, compliance readiness, analytics depth, and ecosystem integration. It is designed to support vendor shortlisting, RFP design, and negotiation strategy by clarifying where each player is competing and what tradeoffs buyers should expect.
-
Regulatory and quality alignment mapping. Given the centrality of compliance to purchasing decisions, the study connects market dynamics to the practical implications of GxP data requirements, validated system expectations, and real-time monitoring frameworks. This helps organizations anticipate what vendors should demonstrate during evaluation and what internal validation effort may be required after selection.
For teams responsible for capital planning in 2026, the report is intended to function as a decision-support asset rather than a static industry summary. It provides the structure needed to compare deployment options, weigh integration complexity, and align software strategy with operational priorities across development and manufacturing functions.
Competitive Landscape: Six Players Shaping the Platform Race
The market is characterized by a mix of specialized analytics providers and broader life-science or manufacturing technology companies, with competitive intensity rising as platforms expand from data visualization into integrated workflow orchestration and AI-assisted analysis. Our research tracks the strategic postures of several core organizations that are actively shaping buyer expectations and setting the functional bar for next-generation bioprocessing analytics.
Genedata
Headquartered in Basel, Switzerland, Genedata offers an enterprise platform built around integrated data management, automation, and analytics across bioprocess development and CMC workflows. Its positioning emphasizes QbD support, AI-ready datasets, and compliance-aligned design, making it relevant for organizations seeking a more unified development-to-manufacturing data backbone. Recent activity underscores this trajectory: in August 2025, the company released a new version of Genedata Selector focused on GMP-compliant NGS in biopharma manufacturing and quality control. In March 2026, mAbxience selected Genedata Bioprocess to automate end-to-end CDMO workflows, an indicator of how broader workflow automation is becoming a competitive differentiator.
Invert
Based in San Francisco, Invert provides an infrastructure and AI-powered intelligence platform aimed at bioprocess data unification, real-time monitoring, analysis, and optimization. Its interface strategy has drawn attention with the introduction of Invert Assist, a natural language analysis interface launched in October 2025 to support process modeling, data analysis, and insight generation. This type of interface innovation matters strategically because it expands accessibility to analytics outputs and reduces reliance on highly specialized data teams for routine interpretation tasks.
Körber Pharma
Körber Pharma, based in Lüneburg, Germany, brings PAS-X Savvy, a collaborative real-time bioprocess data analytics and management platform focused on visualization, holistic analysis, PPI, and integration with MES systems. Its strength lies in connecting analytics more tightly to execution and operational systems, which appeals to manufacturers seeking a more continuous link between data insight and production control.
Sartorius
Sartorius, headquartered in Göttingen, Germany, offers SIMCA and MODDE software for multivariate data analysis, DOE, real-time process monitoring through SIMCA-online, predictive analytics, and QbD in bioprocessing. Its long-standing presence in analytical and process-related tooling gives it a strong foundation in multivariate methods and process understanding, which remains central for teams pursuing rigorous experimental design and live monitoring.
BioRaptor
BioRaptor, based in Binyamina, Israel, specializes in a bioprocessing data analytics platform that unifies online, at-line, and offline data, applies machine learning for optimization, supports cross-run analysis, and integrates with LIMS and ELN systems. Its value proposition is particularly relevant for organizations trying to break down data silos and create a more cohesive analytical record across heterogeneous measurement environments.
Merck KGaA / Sigma-Aldrich
Through its offering of Bio4C ProcessPad software, Merck KGaA / Sigma-Aldrich provides a solution focused on bioprocessing data collection, visualization, and analytics. As a player with broad life-science reach, its software entry can be attractive for organizations already embedded in its reagent, material, or service ecosystems, especially when data collection standardization and straightforward visualization are priorities.
Beyond individual profiles, the competitive picture is defined by concentration and consolidation pressure. The market reflects a meaningful share held by a limited number of leading firms, with the top three and top five players collectively representing a substantial portion of market value. This structure matters for buyers because it influences negotiation leverage, integration risk, and the breadth of alternative options available during vendor evaluation. At the same time, continued product launches, deployment wins, and software updates suggest that differentiation is increasingly occurring in areas such as compliance readiness, AI-assisted interaction, MES/LIMS connectivity, and end-to-end workflow automation.
Deployment, Application, and Geographic Context
The market's structure is being shaped not only by vendor competition but also by how organizations choose to deploy and apply analytics software. Cloud-based and on-premises deployment paths each carry distinct tradeoffs around scalability, control, validation effort, and connectivity to existing manufacturing systems. Meanwhile, application demand is distributed across process development, manufacturing and production, and quality and regulatory compliance, with each functional area placing different emphasis on multivariate analysis, real-time monitoring, traceability, and cross-functional data sharing. The full study examines these structural splits in detail so that buyers can assess where their own demand profile aligns with broader market momentum.
Geographic distribution also plays a role in shaping demand intensity, vendor reach, and implementation complexity. Different regions reflect varying levels of biomanufacturing maturity, regulatory interpretation, and digital infrastructure readiness. While our research maps these regional dynamics, the practical implication for 2026 planning is that deployment decisions should be evaluated with local compliance expectations, internal data governance maturity, and integration constraints in mind rather than treated as purely technology-driven choices.
Implications for 2026 Strategy and Beyond
For executives and strategy teams planning the 2026 investment cycle, the market signals point toward a few recurring priorities. First, analytics software is increasingly being treated as a multi-year enabler rather than a point solution, which means selection criteria should weigh scalability, data architecture compatibility, validation readiness, and the ability to support evolving use cases across development and manufacturing. Second, AI-enabled interfaces and natural language interaction are expanding the practical reach of analytics, but they do not remove the need for strong underlying data governance and compliance design. Third, the competitive field is maturing quickly, and vendor differentiation is becoming more subtle; buyers need a structured evaluation framework that goes beyond feature checklists to include workflow fit, integration effort, and long-term maintainability.
Bioprocess Controllers and Automation Systems Market
The broader takeaway is that the market is moving from early-stage adoption to a more demanding phase where performance, compliance, and integration quality determine the value a platform ultimately delivers. Organizations that enter this phase with clear internal requirements, realistic deployment assumptions, and a well-defined analytics strategy are better positioned to capture the operational benefits that fuel continued market growth.
Conclusion: From Signal to Strategic Action
The Bioprocessing Data Analytics Software Market is entering a period of sustained expansion supported by regulatory pressure, PAT-inspired real-time analytics, broader cloud and AI adoption, and increasing demand for unified data workflows across development and manufacturing. Our research provides a detailed map of that trajectory, the competitive structures shaping it, and the practical factors that should guide purchasing and investment decisions in 2026 and beyond.
This preview is intended to demonstrate the depth and orientation of the full study, but the complete report contains the segmentation detail, competitive benchmarking, deployment analysis, and regional context needed to turn market signals into actionable strategy. For teams preparing budgets, evaluating vendor shortlists, or building analytics roadmaps, accessing the full intelligence framework offers a more precise foundation for decision-making and a clearer view of where the market is headed through 2032.
For detailed analysis of this topic, please visit the official page: Bioprocessing Data Analytics Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Domestic Appliances Market to Reach $1,059.51 Billion by 2032, Growing at 4.85% CAGR
By pmarketresearch, 2026-09-17
Navigating the Next Wave: Strategic Intelligence for the Global Domestic Appliances Market
The worldwide domestic appliances sector stands at a critical inflection point. From shifting trade policies and raw material volatility to accelerating smart-home integration and evolving consumer replacement cycles, the operating environment demands more than surface-level market commentary. Decision-makers need a structured, data-grounded view of where value is being created, where margins are under pressure, and which competitive moves will separate leaders from laggards over the coming decade. Our newly released Worldwide Domestic Appliances Market research study delivers exactly that: a comprehensive strategic blueprint designed for executive teams, category managers, and corporate development professionals who must act on evidence rather than intuition.
Home Appliances Market
This article previews the analytical architecture, market sizing framework, competitive dynamics, and real-world industry developments embedded in the full report. It is designed to demonstrate the depth of our methodology and the practical utility of our findings while leaving the granular segmentation, regional breakdowns, and quantified investment modeling for the complete intelligence package. For organizations preparing capital allocation, product roadmap, and go-to-market decisions for 2026 and beyond, the complete dataset is essential reading.
A Market in Motion: Sizing, Trajectory, and Structural Shifts
Understanding the global domestic appliances market requires a disciplined look at both historical performance and forward-looking momentum. Our analysis traces the sector from 2020 through the base year of 2025, then extends a structured forecast window through 2032. Over the historical period, the market demonstrated resilient expansion, driven by post-pandemic housing activity, rising disposable incomes in key emerging economies, and accelerated upgrades in residential appliance fleets. Revenue measurements across this timeframe show a clear upward trajectory, with the global market surpassing the half-trillion mark and continuing to scale toward new highs as household modernization and replacement demand compound across regions.
Looking ahead, the forecast period captures a market expected to grow at a compound annual growth rate of 4.85 percent. This figure is not a blunt average but a synthesized outcome of divergent regional maturity curves, product-category performance, and channel migration patterns. Our modeling reflects how macroeconomic conditions, housing turnover, and consumer willingness to invest in premium or smart-enabled features will interact with supply-side constraints, logistics costs, and trade policy shifts. The result is a nuanced growth path that accounts for periods of acceleration alongside segments where saturation and replacement-cycle lengthening moderate expansion.
Importantly, the report does not treat growth as monolithic. Revenue expansion is being shaped by the interplay of major and small appliances, multi-brand retailing versus direct-to-consumer and online channels, and the geographic weight of Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa. Each of these structural vectors carries different margin profiles, competitive intensity, and risk exposure. The full publication unpacks these layers with quantified contributions, year-by-year projections, and scenario analysis, but the headline takeaway for strategic planning is clear: growth is real, yet it is unevenly distributed and increasingly contingent on how well companies align product portfolios, pricing strategies, and distribution footprints with local demand economics.
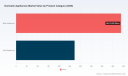
Market structure also informs competitive behavior. Our analysis incorporates market concentration metrics that highlight the share held by leading firms. A CR3 near twenty-eight and a half percent and a CR5 in the low forty-two percent range indicate a landscape where scale players command meaningful presence without fully dominating every sub-segment or geography. This concentration profile has strategic implications: it suggests room for specialist and regional brands to compete effectively in attractive niches, while larger multinationals leverage brand portfolios, manufacturing scale, and global supply networks to defend share and pursue premiumization. For investors and corporate strategists, concentration dynamics are a vital input into M&A screening, partnership evaluation, and offensive or defensive market entry decisions.
Competitive Architecture: Who Sets the Pace and How
The domestic appliances ecosystem is anchored by a set of globally capable manufacturers whose strategies shape pricing, innovation cadence, and consumer expectations. Our report profiles a cross-section of these organizations, capturing their headquarters, brand portfolios, geographic strengths, and strategic emphasis.
Haier Smart Home Co., Ltd., operating from Qingdao, has built a broad global footprint by integrating flagship, acquired, and regional brands across refrigerators, washing machines, air conditioners, and cooking appliances. Its strategy emphasizes smart and energy-efficient solutions, positioning the company to compete across value and premium tiers while leveraging a multi-brand architecture to address distinct market segments. Whirlpool Corporation, based in Benton Harbor, Michigan, remains a leading manufacturer of major domestic appliances with a deep North American footprint and a global brand portfolio that includes Whirlpool, Maytag, and KitchenAid. Its strength in refrigerators, washers, dryers, dishwashers, and ovens makes it a bellwether for major-appliance demand and pricing dynamics in mature markets.
From East Asia, LG Electronics and Samsung Electronics both offer wide-ranging appliance lines that increasingly converge on smart connectivity, AI features, and energy efficiency. LG’s portfolio spans refrigerators, washing machines, dishwashers, and air conditioners, with a clear emphasis on connected functionality and efficiency gains. Samsung complements this with a comprehensive lineup that includes smart refrigerators, washers, dryers, ovens, and air conditioners, differentiating through Bespoke customization and AI-powered technologies that target consumers seeking personalization alongside performance. These two players illustrate how product design, software integration, and brand positioning can be used to capture share in increasingly discerning consumer markets.
Electrolux AB, headquartered in Stockholm, operates as a global producer of both major and small domestic appliances under the Electrolux and Frigidaire brands, with a pronounced emphasis on sustainability across cookers, washing machines, dishwashers, and vacuum cleaners. BSH Hausgeräte GmbH, the Bosch-Siemens home appliance entity based in Munich, anchors European premium demand with Bosch and Siemens brands, covering cooking, laundry, dishwashing, and refrigeration while prioritizing quality and innovation. Midea Group, from Foshan, is a large-scale manufacturer with significant export volume, covering air conditioners, refrigerators, washing machines, and small kitchen appliances, and it continues to expand its international reach. Panasonic, operating from Kadoma, widens the field with refrigerators, washing machines, microwaves, and air conditioners, emphasizing health, wellness, and energy-saving features. Arçelik A.Ş., based in Istanbul, is a major producer of white goods under Beko, Grundig, and other brands, with particular strength in Europe and emerging markets. Hisense, also headquartered in Qingdao, competes on affordability across refrigerators, washing machines, TVs, and air conditioners while growing its global share. Miele & Cie. KG, in Gütersloh, occupies the high-end niche with a reputation for durability and performance in washing machines, dishwashers, ovens, and vacuum cleaners. Finally, Gree Electric Appliances, from Zhuhai, remains a leading producer of air conditioners and other climate-control appliances, wielding substantial worldwide production capacity.
These profiles are not static corporate snapshots. Each organization is navigating a different combination of input cost pressures, regulatory exposure, channel shifts, and technology roadmaps. The report examines how their strategies intersect with market concentration, regional demand profiles, and product-category growth rates, helping readers identify which competitors are likely to gain share in which segments and why. The full document layers in quantified competitive positioning and movement analysis, enabling sharper benchmarking and more credible scenario planning.
Industry Dynamics in Real Time: Regulation, Materials, and Consumer Behavior
A market study gains its value when it connects structural data to the forces actively reshaping operations and demand. Several recent developments illustrate how quickly the domestic appliances landscape can shift and why forward-looking intelligence is indispensable.
Trade policy has become a first-order variable. In June 2025, the United States increased Section 232 tariffs on steel and aluminum imports to 50 percent, with subsequent expansions affecting steel content in imported appliances such as refrigerators, washers, dryers, dishwashers, and ovens. For manufacturers and retailers, this change alters landed costs, sourcing strategies, and end-price positioning. Public statements from major industry participants have indicated that steel tariffs and related measures can materially raise input costs, with estimates that new tariffs could increase retail prices of affected imported appliances by $50 to $70. These dynamics do not simply compress margins; they also influence consumer affordability, cross-border sourcing decisions, and the relative competitiveness of domestic versus imported product lines.
At the same time, regulatory conversations around appliance energy sources are evolving. Ongoing discussions by U.S. municipal, state, and federal regulators regarding potential new regulations or bans on natural gas appliances, citing climate concerns, could reshape product mix and transition costs for manufacturers. Even where final rules remain under debate, the uncertainty alone affects portfolio planning, engineering investments, and go-to-market messaging. Companies that anticipate these shifts can prepare alternative product architectures and channel strategies well ahead of enforceable deadlines, while laggards risk stranded development spend and reactive repositioning.
Consumer behavior is also being redefined by practical considerations rather than abstract trends. In North America, early replacement cycles are expected for dishwashers, refrigerators, and air conditioners amid moderate growth projections, with emphasis on energy savings and convenience features. This pattern signals a market where renewal is being driven by functional payoff—lower operating costs, smarter controls, and improved reliability—rather than by discretionary upgrade alone. Meanwhile, broader market outlooks for 2026 point to flat to modest growth in major domestic appliances and small domestic appliances, underscoring the importance of replacement timing, product mix, and promotional strategy in mature markets.
On the innovation and showcase front, events such as IFA and AWE continue to function as barometers of product direction and brand ambition. Exhibitions have highlighted handheld cleaning devices, robotic mopping and window-cleaning systems, and a broader theme of humanizing technology in household appliances. These showcases reflect an industry moving beyond core mechanical performance toward integrated convenience, automation, and user experience. Preparations for major appliance fairs in 2026 indicate sustained momentum in smart-home appliances and consumer electronics convergence, with new product launches and forums designed to shape consumer expectations and vendor partnerships. For strategists, such events are not merely promotional; they are leading indicators of feature prioritization, design language, and competitive differentiation in the next product cycle.
What the Full Study Delivers: Operational Intelligence for 2026 Decisions
A strategic research report is only as useful as the decisions it enables. Our Worldwide Domestic Appliances Market study is built around actionable outputs rather than retrospective summaries. It provides a detailed segmentation framework that breaks down revenue by region and by product category, allowing users to isolate the markets and categories most relevant to their portfolios. The report maps distribution channels—including multi-brand stores, online retail, and specialty stores—so that commercial teams can evaluate where demand is concentrating and how channel economics differ across product types and geographies.
Beyond segmentation, the study delivers quantified market sizing across historical and forecast periods, scenario-aware growth trajectories, and concentration analysis that grounds competitive benchmarking in measurable share dynamics. It connects these market structures to the strategic profiles of leading manufacturers, giving readers a clear line of sight from macro demand conditions to individual company positioning. This integrated design supports a wide range of decisions: entry and expansion prioritization, pricing and promotional calibration, product roadmap alignment, sourcing and tariff mitigation planning, and M&A or partnership screening.
Critically, the full publication also integrates the operational implications of regulation, raw material costs, and consumer replacement behavior into the analytical framework. Rather than treating these as separate overlays, the report weaves them into the market outlook so that strategic recommendations reflect both opportunity and constraint. This is what transforms data into decision support: a consolidated view that shows not only how large the market is and where it is heading, but also what will determine profitability and share outcomes along the way.
Worldwide Domestic Appliances Market
Why This Research Matters Now
The domestic appliances market in 2026 is not a passive backdrop for corporate strategy. It is a dynamic environment where trade policy, input costs, regulatory trajectories, and consumer replacement behavior interact with product innovation and channel evolution. In such a landscape, organizations that rely on lagged data or fragmented sources risk misjudging demand timing, margin exposure, and competitive threat. A structured, forward-looking research asset reduces that uncertainty and provides a common factual foundation for cross-functional planning.
Our study is designed to serve exactly that function. It offers the scale and rigor required for enterprise-level decisions while preserving the granularity needed for category, regional, and channel-level action. By integrating historical performance, forecast momentum, segmentation splits, concentration metrics, competitor profiles, and current industry developments, it creates a single reference point for market intelligence. For leaders preparing investments, product launches, pricing frameworks, and supply strategies for the 2026 to 2032 horizon, this depth is not optional—it is foundational.
The preview above outlines the strategic logic, market structure, competitive landscape, and live industry forces that define the sector. The complete Worldwide Domestic Appliances Market research report contains the detailed regional and product-category breakdowns, quantified forecast tables, channel-level analysis, concentration calculations, and competitive movement mapping needed to operationalize these insights. To access the full dataset and integrate it directly into your 2026 decision process, review the complete Worldwide Domestic Appliances Market market research study and its accompanying intelligence package.
For detailed analysis of this topic, please visit the official page: Worldwide Domestic Appliances Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Polyolefin Antioxidants Market to Hit $2,298.61 Million by 2032 at 4.85% CAGR
By pmarketresearch, 2026-09-17
Strategic Imperatives in the Global Polyolefin Antioxidants Market: A 2026 Outlook
Introduction: The Critical Role of Stabilization in Polymer Durability
The global polyolefin antioxidants market stands at a pivotal juncture as we enter 2026. As the backbone of modern polymer processing, polyolefins such as polyethylene and polypropylene require robust stabilization to withstand thermal degradation during processing and oxidative stress during service life. For manufacturers, compounders, and end-users, understanding the trajectory of antioxidant demand is not merely an academic exercise—it is a strategic necessity. The ability to anticipate market shifts, regulatory pressures, and competitive moves defines the resilience of supply chains in the plastics industry.
This analysis serves as a precursor to the comprehensive Worldwide Polyolefin Antioxidants Market study released by PW Consulting. Our objective is to outline the macro-environmental forces shaping the sector and demonstrate why actionable intelligence is vital for corporate strategy in 2026 and beyond. The market has shown resilience despite volatile raw material costs and shifting regulatory landscapes, signaling a mature yet evolving ecosystem.
Market Trajectory and Historical Performance
The market size has demonstrated a consistent upward trajectory over the past half-decade, reflecting the insatiable global demand for plastic products across packaging, automotive, and construction sectors. Historical data from 2020 through 2025 indicates a steady recovery and growth pattern following initial pandemic-related disruptions. In 2020, the market valuation stood at approximately 1302.1 million USD. This figure climbed to 1386.8 million USD in 2021 and reached 1449.36 million USD by 2022.
Worldwide Polyolefin Antioxidants Market
A notable acceleration occurred in 2024, with revenue hitting 1593.45 million USD, culminating in a base year 2025 estimate of 1650.0 million USD. This growth underscores the critical integration of antioxidants in high-performance polymer applications. Looking forward, the forecast period from 2026 to 2032 projects continued expansion. The market is expected to begin 2026 at 1723.94 million USD, progressing toward 2298.61 million USD by 2032.
This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 4.85 percent throughout the forecast period. Such a rate suggests steady, moderate expansion rather than explosive volatility, indicating a market where strategic positioning and efficiency gains matter more than sheer volume grabs. However, slight contractions in specific forecast years, such as the dip projected between 2027 and 2028, highlight the sensitivity of the market to external economic and supply chain variables.
Segmentation Dynamics: Types and Applications
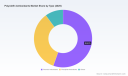
The market is fundamentally divided by chemical type and end-use application, each carrying distinct implications for supply chain management and product development. In terms of chemical composition, phenolic antioxidants and phosphite antioxidants dominate the landscape. Phenolic antioxidants are widely recognized for their ability to scavenge free radicals, making them essential for long-term thermal stability in polyolefins. Phosphite antioxidants, conversely, play a crucial role during the melt processing phase, preventing degradation under high temperatures.
Rubber Antioxidant Market
While specific regional revenue splits and precise percentage breakdowns of these segments are detailed in the full report, it is important to understand the strategic weight of these categories. The balance between phenolic and phosphite usage often depends on the specific processing requirements of the polyolefin compound. For instance, applications requiring high heat resistance during extrusion may lean heavily on phosphite varieties, whereas final product durability might prioritize phenolic stabilizers.
Regarding applications, the packaging sector remains a primary driver of demand. The need for durable films and containers that resist oxidation extends shelf life and maintains integrity. Automotive and construction sectors follow closely, where polymer components must endure harsh environmental conditions over extended lifecycles. The interplay between these application sectors dictates demand fluctuations. For example, a surge in automotive lightweighting initiatives using polypropylene directly ripples through the antioxidants market. Understanding which application segment is driving growth in a specific region is key to targeting sales and production strategies effectively.
Competitive Landscape and Key Players
The industry is characterized by a moderately concentrated competitive structure. The top three players hold a significant market share, while the top five companies consolidate a majority of the revenue. This concentration suggests that scale, technology, and regulatory compliance are significant barriers to entry. Major corporations are actively managing their portfolios through innovation, capacity expansion, and strategic compliance updates.
Key entities shaping this landscape include BASF SE, headquartered in Ludwigshafen, Germany. BASF continues to lead with its Irganox and Irgafos series, tailored for stabilization in films, pipes, and automotive applications. In October 2025, BASF launched Irganox 1135, a high-performance phenolic antioxidant designed for polyolefin masterbatches with improved migration resistance. This product launch signals a focus on high-value specialty grades rather than commoditized volumes.
Songwon Industrial Group, based in Ulsan, South Korea, is another critical player. They provide SONOX primary and secondary antioxidants emphasizing heat and oxidation resistance. In June 2025, Songwon expanded production capacity for phosphite antioxidants in their Ulsan facility by 20 percent to meet rising polyolefin demand. This capacity expansion indicates a bullish outlook on regional manufacturing needs and supply security.
SI Group (SICPA Specialty Chemicals), located in Schenectady, NY, USA, supplies Lowinox and Weston phosphite antioxidants for polyolefin compounding. Notably, in March 2025, SI Group achieved a REACH compliance update for Weston 619F phosphite used in polyolefin stabilization. This regulatory milestone is crucial for maintaining access to the European market. Other significant contributors include Clariant AG in Switzerland with their Hostanox and Hostaphos lines, Sumitomo Chemical Co., Ltd. in Tokyo with Sumilizer series, and Addivant, now part of SI Group, known for Naugard phenolic antioxidants.
Regional players are also gaining traction. Everlight Chemical Industrial Corp. in Taipei supplies Eversorb and Evernox antioxidants, while Rianlon Corporation in Shijiazhuang, China, manufactures Songnox phenolic and phosphite antioxidants, focusing on cost-effective blends for global markets. The presence of cost-focused manufacturers in Asia alongside technology leaders in Europe and North America creates a dynamic competitive environment where pricing pressure meets performance requirements.
Industry Dynamics: Raw Materials and Regulatory Headwinds
Strategic planning in 2026 must account for volatile input costs and stringent regulatory frameworks. Raw material pricing has been a significant variable. Phenol spot prices reached 1450 USD per metric ton in Q4 2025, marking a 12 percent increase year-over-year due to supply tightness from Asian producers. This upward pressure on key feedstock directly impacts the cost structure of phenolic antioxidants. Simultaneously, phosphorous acid prices increased to 1200 USD per metric ton in Asia during Q3 2025 amid raw phosphate disruptions. These cost escalations require manufacturers to optimize formulations or pass costs through the value chain carefully.
Regulatory compliance remains a critical filter for market access. The EU REACH Annex XVII restricts certain phosphite antioxidants in polyolefins if hydrolyzate levels exceed 0.1 percent. This regulation, highlighted by the European Chemicals Agency in February 2024, forces formulators to monitor degradation products closely. Non-compliance can lead to market exclusion, making regulatory intelligence a core competency for suppliers. Additionally, trade policies continue to shape flow patterns. US Section 301 tariffs on Chinese-origin antioxidants remain at 25 percent for polyolefin additives imported post-2024. This tariff structure influences sourcing decisions, encouraging buyers to diversify supply chains away from tariff-exposed origins or absorb the cost margin erosion.
Strategic Implications for 2026 Decision Makers
For executives and strategists navigating the 2026 landscape, several imperatives emerge from this macro analysis. First, supply chain resilience is paramount. Given the tariff structures and raw material volatility, reliance on single-source suppliers from specific regions poses a risk. Diversifying sourcing between established European and North American producers and cost-competitive Asian manufacturers requires a nuanced understanding of total landed cost, including duties and logistics.
Second, innovation must focus on compliance and performance. The regulatory environment, particularly in Europe, is tightening around chemical safety and degradation products. Companies that proactively adapt their formulations to meet REACH standards and invest in migration-resistant technologies, similar to recent launches by major players, will secure a competitive advantage. Third, capacity planning must align with regional demand shifts. The capacity expansion by Songwon suggests strong demand in Asia Pacific, while regulatory pressures may shift some production or formulation activities closer to end markets in North America and Europe.
The market concentration indicates that partnerships with top-tier suppliers can guarantee stability, but niche players offering cost-effective blends may provide flexibility in price-sensitive segments. Decision-makers need to balance the security of established brands with the cost efficiencies offered by emerging competitors.
Conclusion: Unlocking Comprehensive Intelligence
The polyolefin antioxidants market is a complex ecosystem driven by chemical innovation, regulatory compliance, and raw material economics. While the macro trends point to steady growth supported by a 4.85 percent CAGR, the devil lies in the details. Regional disparities, specific application growth rates, and precise competitive market shares require granular analysis to inform accurate forecasting and investment decisions.
This overview highlights the strategic context necessary for high-level planning. However, to truly optimize supply chains, pricing strategies, and product portfolios, stakeholders need access to the full depth of data available in the Worldwide Polyolefin Antioxidants Market report. The complete study provides detailed segmentation analysis, specific regional revenue estimates, comprehensive company profiles, and scenario-based forecasting that goes beyond the macro narrative.
We invite industry leaders to explore the full findings to equip their teams with the precise intelligence needed to thrive in 2026 and beyond. Understanding the nuances of market concentration, regulatory impacts, and specific segment dynamics is the key to transforming uncertainty into strategic opportunity.
For detailed analysis of this topic, please visit the official page: Worldwide Polyolefin Antioxidants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Ice Cubers Market Hits $3.85B in 2025, Projects 6.5% CAGR Through 2032
By pmarketresearch, 2026-09-17
Navigating the Frozen Horizon: Strategic Insights into the Global Ice Cubers Market (2026-2032)
In the modern commercial landscape, ice is no longer merely a commodity; it is a critical component of operational efficiency, customer satisfaction, and regulatory compliance. From high-volume foodservice establishments to precision-driven healthcare facilities, the reliability of ice production systems directly impacts the bottom line. As we move further into 2026, understanding the trajectory of the Ice Cubers Market is essential for stakeholders looking to capitalize on emerging opportunities or mitigate supply chain risks. This article serves as a strategic preamble to our comprehensive market research report, offering a high-level view of the market architecture while reserving the granular intelligence for our full analysis.
Our latest study, Ice Cubers Market Forecast 2026-2032 , leverages historical data from 2020 through 2025 to construct a robust model for the coming seven years. The narrative is one of steady expansion, driven by evolving consumption patterns, technological advancements in refrigeration, and shifts in global manufacturing capacities. For enterprise leaders, the question is no longer whether the market is growing, but where to position assets and partnerships to best ride this wave.
Macro Growth Trajectory and Market Valuation
The historical performance of the ice cuber sector indicates a resilient demand curve. Drawing from our base year analysis in 2025, the global market has demonstrated consistent upward momentum over the past half-decade. The overall market size has traversed from a baseline of approximately 2,550 million USD in 2020 to an estimated 3,850 million USD in 2025. This growth underscores the integral role of commercial ice systems in daily operations across multiple sectors.
Looking forward, the forecast period from 2026 to 2032 projects a continued compound annual growth rate (CAGR) of 6.5 percent. This trajectory suggests that by the end of the forecast window, the market value will approach nearly 6,000 million USD. Such expansion is not uniform; it is punctuated by specific inflection points related to raw material availability, regulatory shifts, and regional economic health.
Key macroeconomic indicators included in our full report highlight the following progression:
- 2026 Valuation: The market is positioned to open the forecast period at over 4,100 million USD, reflecting immediate post-2025 momentum.
- Mid-Decade Outlook: By 2029, valuations are expected to surpass the 5,000 million USD threshold, signaling a mature growth phase.
- Terminal Year 2032: The market is projected to reach approximately 5,982 million USD, reinforcing the long-term viability of ice equipment investments.
These figures represent the aggregate revenue landscape in USD millions. However, understanding the drivers behind these numbers requires a deeper dive into segmentation and regional dynamics, which our full report dissects in detail.
Strategic Segmentation: Product and Application Dynamics
The Ice Cubers Market is not a monolith. It is defined by distinct product technologies and application verticals that respond differently to economic pressures. Our research categorizes the market into key product types, including Cube Ice Machines, Flake Ice Machines, Nugget Ice Machines, and Scale Ice Machines. While cube ice remains a dominant force due to its versatility in foodservice and retail, the demand for specialized ice forms is influencing manufacturing priorities.
On the application front, the sector is diversified across Foodservice, Healthcare, Retail, and Industrial uses. Foodservice continues to be a primary consumption driver, given the reliance on ice for beverages and preservation. However, the healthcare segment represents a critical niche where hygiene and reliability are non-negotiable. Retail and industrial applications further broaden the demand base, creating a buffer against sector-specific downturns.
Our full segmentation analysis explores the revenue contribution of each category without exposing the precise percentage splits publicly. This approach allows us to discuss the weight of each segment strategically. For instance, the interplay between high-volume cube ice production and the growing preference for gourmet clear cubes in premium hospitality settings is a key narrative thread. Similarly, the industrial demand for heavy-duty ice systems influences the type of equipment manufacturers prioritize in their R&D pipelines.
Global Regional Landscape
Geographically, the market spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents unique challenges and opportunities shaped by local infrastructure, climate conditions, and economic development levels.
North America remains a cornerstone of the market, supported by a mature foodservice industry and high standards for commercial equipment. Europe contributes significantly through stringent regulatory environments that drive innovation in energy efficiency. Asia Pacific represents a dynamic growth engine, where expanding hospitality sectors and urbanization are accelerating adoption rates. Latin America and the Middle East and Africa, while smaller in aggregate volume, offer strategic entry points for manufacturers targeting emerging markets.
Our report provides a nuanced view of these regional contributions. Rather than simple rankings, we analyze the velocity of growth in each territory. This helps investors and operational leaders decide where to allocate inventory or establish distribution networks. The detailed regional revenue data, however, is reserved for the full intelligence package to maintain competitive advantage for our clients.
Competitive Landscape and Industry Leadership
The market structure is characterized by a mix of established multinational manufacturers and specialized regional players. Our analysis identifies key companies that define the competitive boundaries. Leaders in this space include Hoshizaki Corporation (Japan), known for its global manufacturing footprint in Japan and the US; Manitowoc Ice (US), a major producer integrated into Pentair; and Scotsman Ice Systems (US), recognized for gourmet clear cube technologies.
Other significant entities shaping the market include Ice-O-Matic (US), Follett Ice (US), Brema Ice Makers (Italy), Cornelius Inc. (US), North Star Ice Equipment (US), and KOLD-DRAFT (US). Each brings distinct technological advantages, from horizontal evaporator technology to specialized dispensing systems. The competitive intensity is reflected in the market concentration metrics, where the top three players hold a notable share of the revenue, and the top five expand that influence further.
Ice Cubers Market
Recent developments indicate an active strategy of visibility and innovation among these players. Throughout 2025 and early 2026, major industry participants have leveraged trade shows to showcase next-generation solutions. For example, ICESTA exhibited ice making solutions at the Canton Fair in April 2026, while Naixer displayed commercial cube ice machines at the NRA Show in Chicago in March 2026. Additionally, Icematic participated in SIGEP World in early 2025 to highlight cube machine capabilities. These exhibitions are not merely promotional; they signal where R&D investments are being directed, particularly in response to changing customer expectations and operational constraints.
Critical Market Dynamics: Materials, Regulation, and Efficiency
Beyond the financials and the players, the underlying dynamics of the Ice Cubers Market are shifting. Three primary forces are currently reshaping the operational environment for manufacturers and buyers alike: raw material costs, regulatory compliance, and energy efficiency mandates.
Ice Maker Market
Raw Material Volatility
Stainless steel remains the primary material for ice cuber construction, chosen for its corrosion resistance and adherence to hygiene standards. However, cost structures are sensitive to commodity price fluctuations. Sector analysis from March 2026 indicated that prices for relevant stainless steel grades showed declines of up to 16 percent in early 2026 across Asia and Europe. While this offers potential margin relief for manufacturers, it introduces volatility into procurement planning. Furthermore, benchmarks such as steel rebar traded around 3,174 CNY/T as of May 20, 2026, with modest monthly increases. Volatility tied to nickel and chromium for stainless variants used in equipment remains a risk factor that requires active supply chain management.
Regulatory Compliance
Commercial ice machines must comply with NSF/ANSI standards for food equipment safety and sanitation. These regulations drive the use of high-grade stainless steel and efficient designs, effectively setting a barrier to entry for lower-quality producers. Compliance is not static; it evolves with health standards, forcing continuous design iterations. Manufacturers who fail to align with these standards risk market exclusion, making regulatory intelligence a critical component of strategic planning.
Energy Efficiency and Refrigerants
Macro trends are increasingly dictating product design. Energy efficiency mandates and R290 refrigerant compliance are influencing new ice cuber model designs to reduce operational costs in hospitality and foodservice. As energy costs rise and sustainability goals become central to corporate strategy, the total cost of ownership (TCO) for ice machines is gaining prominence over initial purchase price. Models that minimize energy consumption while maintaining production capacity are becoming the preferred choice for facility managers.
The Strategic Value of Comprehensive Intelligence
While the overview provided here outlines the structural health and directional trends of the Ice Cubers Market, effective decision-making requires granular data. Enterprise leaders need to know more than just the aggregate growth rate; they need to understand the specific revenue splits across regions to optimize distribution, the precise segmentation shares to tailor product portfolios, and the detailed competitive moves to anticipate market shifts.
Our full market research report delivers this depth. It provides a detailed breakdown of historical and forecast data, allowing for precise scenario planning. It dissects the segmentation splits by region, product type, and application, giving you the clarity to identify high-growth niches. It also includes comprehensive profiles of key companies, analyzing their headquarters, operational focus, and recent strategic developments.
Furthermore, the report contextualizes raw material trends and regulatory shifts within the broader market dynamics, offering actionable recommendations for procurement and product development. Whether you are a manufacturer looking to optimize production capacity, a distributor seeking high-potential regions, or an investor evaluating market entry points, the full intelligence suite is designed to reduce uncertainty and enhance strategic agility.
Conclusion
The Ice Cubers Market is on a stable growth path, underpinned by essential demand across foodservice, healthcare, retail, and industrial sectors. The projected CAGR of 6.5 percent through 2032 indicates a healthy environment for investment and innovation. However, success in this environment depends on navigating the complexities of material costs, regulatory compliance, and competitive differentiation.
This article has provided the strategic framework necessary to understand the market's trajectory. To unlock the specific data points, regional revenue figures, and detailed competitive analysis required to execute your strategy, we invite you to access the full Ice Cubers Market Forecast 2026-2032 report. Equip your organization with the precise intelligence needed to thrive in the frozen horizon of the coming decade.
For detailed analysis of this topic, please visit the official page: Ice Cubers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vet Speculum Market Hits $185M in 2025, Projected 5.2% CAGR Through 2032
By pmarketresearch, 2026-09-17
Navigating the Next Horizon: Strategic Insights into the Veterinary Speculums Market Through 2032
The global veterinary healthcare industry is undergoing a structural transformation driven by rising pet ownership, expanding large animal husbandry practices, and an increasing emphasis on procedural precision. Within this ecosystem, the veterinary speculums market represents a critical yet often under-analyzed segment of surgical and diagnostic instrumentation. For executives, procurement leaders, and clinical product strategists, understanding the trajectory of this market is not merely an academic exercise—it is a prerequisite for capital allocation, supply chain resilience, and competitive positioning.
Our latest market research publication delivers a comprehensive, data-backed examination of this sector, tracing historical performance from 2020 through 2025 and projecting forward across a forecast window extending to 2032. Anchored in a base year of 2025 and denominated in USD millions, the analysis quantifies a market that has demonstrated resilient expansion. Total market revenue grew from 145.0 million in 2020 to 185.0 million in 2025, reflecting sustained demand across both companion animal and production animal segments. The forecast period projects continued momentum, with valuations advancing to 194.16 million in 2026 and reaching 263.8 million by 2032. This trajectory translates to a compound annual growth rate of 5.2 percent, a figure that underscores moderate but predictable upside for stakeholders who can align product portfolios and distribution strategies with emerging clinical workflows.
What separates this study from generic industry summaries is its deliberate focus on operational decision-making. Rather than presenting abstract growth narratives, the report dissects the mechanical, regulatory, and competitive forces that will dictate margin profiles, fulfillment costs, and market access between now and the end of the decade. The following sections outline the analytical architecture of the research and explain why it should be treated as a foundational input for 2026 planning cycles.
Report Architecture: Operational Intelligence for Cross-Functional Teams
The publication is structured to serve multiple internal audiences simultaneously. Clinical product managers, supply chain directors, finance leads, and regional sales heads will each find modules tailored to their decision responsibilities. The core of the report is built around a multi-dimensional segmentation framework that isolates structural demand drivers without obscuring the practical considerations that influence purchasing behavior.
Readers will encounter a detailed examination of product typologies that dominate veterinary diagnostic and surgical procedures. The analysis covers oral speculums, vaginal speculums, and ear speculums paired with otoscope systems, each evaluated through the lens of clinical utility, sterilization compatibility, and practitioner adoption patterns. Rather than merely cataloging product categories, the report connects design variations to real-world usage scenarios. For instance, the prevalence of three-blade Polansky configurations with butterfly screw mechanisms for large animal work, alongside set-screw Killian designs optimized for canine vaginal examinations, is contextualized within the broader demand for durable, sterilizable instrumentation. This product-level granularity enables manufacturers and distributors to identify where specification standardization can reduce inventory complexity and where customization remains a pricing advantage.
The application dimension of the study maps demand across small animal practice and large animal and equine practice. This split is particularly important because procurement cycles, clinician preferences, and facility sterilization capabilities differ materially between these environments. By analyzing how usage intensity, procedure frequency, and replacement cycles vary by practice type, the report equips commercial teams with the insight needed to tailor bundling strategies, reorder scheduling, and field education programs.
Regional coverage is likewise presented through a demand-weighted lens. The research evaluates North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa as distinct operational theaters, each with its own mix of veterinary infrastructure maturity, import dependency, and domestic manufacturing capability. The report does not stop at mapping where demand is concentrated; it investigates the logistical and regulatory friction points that influence time-to-market for imported instruments, the sensitivity of pricing to freight and duty fluctuations, and the extent to which local reprocessing standards shape material selection.
Beyond segmentation, the study incorporates a deep dive into competitive positioning, recent product developments, and the broader industrial context that shapes manufacturing economics. This holistic design ensures that the report can function as both a strategic briefing document for executive committees and a tactical reference for business unit planning.
Competitive Landscape: Concentration, Differentiation, and Strategic Arbitrage
One of the most decision-relevant sections of the research examines the structure of the competitive field. The market is characterized by a moderately fragmented but increasingly disciplined supplier base. Industry concentration metrics indicate that the top three firms command approximately 28.5 percent of total revenue, while the top five account for 35.2 percent. This level of concentration suggests that scale advantages exist, but there is still meaningful room for specialized manufacturers to compete on design fidelity, material quality, and application-specific engineering.
The report profiles the organizations that currently anchor the supply landscape, drawing on product portfolios, geographic footprints, and stated clinical focus areas. GerVetUSA Inc. stands out for its emphasis on German-forged surgical instruments, including vaginal and nasal speculum variants designed for both small and large animals. Jalal Surgical has positioned itself as a manufacturer and supplier of high-quality vaginal speculums built from premium materials intended for repeated veterinary use. Sklar Surgical Instruments contributes to the competitive mix with surgical-grade designs, including Graves and Pederson vaginal speculums adapted for veterinary applications. Jorgensen Laboratories, operating under the JorVet brand, offers specialized instruments such as the Killian K-9 Vaginal Speculum and Polansky Vaginal Speculum, targeting dogs and large animals with configuration-specific engineering. Welch Allyn, now part of Hillrom, provides reusable veterinary specula compatible with otoscopes for ear examinations, including bivalve designs and multiple size options. Surgical Holdings, based in the United Kingdom, focuses on stainless steel obstetrical and vaginal speculums intended for large animal veterinary use. Medline Industries rounds out the profiled set with supplies such as SofSpec reusable veterinary specula and other diagnostic speculums supporting a range of veterinary procedures.
Rather than presenting these companies as static company profiles, the report evaluates them through a strategic lens. It assesses where overlapping product lines create price compression, where differentiated material choices or blade configurations create defensible value, and where distribution partnerships can accelerate adoption in underpenetrated practice types. The analysis also considers the implications of competitive density for private-label and co-branding opportunities, especially in regions where procurement teams prioritize cost predictability without sacrificing sterilizability or mechanical reliability.
Recent innovation activity reinforces the importance of this competitive review. In December 2024, a development effort led by Nail Tekin Önder and colleagues produced and evaluated a novel Onder Speculum designed to improve visualization and retraction of the cervix in small ruminants during transcervical procedures. Documented in the Kafkas University Veterinary Faculty Journal, this work illustrates how targeted procedural challenges can generate new instrumentation concepts with potential downstream commercialization pathways. For incumbent suppliers, such developments signal the need to monitor academic and clinical innovation pipelines, not only to identify potential acquisition or licensing targets, but also to anticipate shifts in procedural standards that may alter demand for conventional configurations.
Market Dynamics and Material Realities: The Forces Shaping Margin and Adoption
Any credible market strategy must account for the underlying industrial and regulatory conditions that determine what can be manufactured, how it can be sterilized, and how it is positioned relative to human-use equivalents. The report integrates these forces explicitly so that readers can distinguish temporary pricing fluctuations from structural cost drivers.
Material composition is a foundational consideration. Veterinary speculums are primarily manufactured from surgical-grade stainless steel chosen for corrosion resistance and compatibility with frequent autoclave sterilization. This material baseline influences not only unit economics but also supplier qualification requirements, reprocessing infrastructure expectations, and lifecycle durability claims. The study examines how variations in steel grade, surface finishing, and mechanical tolerances interact with sterilization cycles to affect total cost of ownership for veterinary practices and, by extension, how suppliers can justify premium positioning when they deliver verifiable durability and consistent tangential performance across repeated reprocessing events.
Regulatory context adds another layer of strategic nuance. Animal-use devices such as veterinary speculums are generally not subject to FDA premarket notification requirements, including the 510(k) pathway, in the same manner as human-use equivalents. This regulatory distinction lowers certain barriers to market entry and can accelerate the commercialization of new designs, but it does not remove scrutiny around quality systems, labeling, and post-market expectations. The report explains how this dynamic shapes competitive speed-to-market on one hand and clinical confidence requirements on the other, and why companies that invest early in robust manufacturing documentation and consistent quality control often gain an advantage in procurement evaluations even when formal device regulation is less prescriptive than in human healthcare.
Product design conventions further influence purchasing decisions. Standard configurations such as Polansky speculums with three blades and butterfly screws for large animals, and Killian speculums with set screws for canine vaginal examinations, are not merely catalog details; they reflect established clinician ergonomics and procedural workflows. The research shows how entrenched design familiarity can slow adoption of alternative geometries unless the replacement clearly improves visualization, reduces tissue trauma, or simplifies handling. For suppliers, this highlights the importance of field education, demonstration programs, and specification sheets that align new designs with existing procedural mental models rather than attempting to displace them without clear clinical justification.
Together, these dynamics create a market environment where growth is neither purely volume-driven nor purely price-driven. Instead, it is shaped by the interaction of material durability, sterilization compatibility, procedural specificity, and procurement behavior across different practice types. Companies that understand these interacting variables are better positioned to set realistic pricing strategies, optimize production planning, and avoid investment in features that add manufacturing cost without translating into procurement preference.
Why This Research Matters for 2026 Decision-Making
The 2026 planning cycle is likely to be defined by procurement recalibration, product portfolio prioritization, and regional expansion decisions. In that environment, decision-makers need more than headline growth figures; they need an integrated view of how demand is distributed, how competitive intensity will affect margin retention, and where product innovation can create durable differentiation.
Veterinary Speculums Market
This study is designed to support those decisions in several concrete ways. First, it provides a consistent historical and forecast baseline that allows finance and operations teams to model revenue scenarios against a 5.2 percent compound annual growth trajectory without relying on anecdotal estimates. Second, it breaks down the market along typological, application, and regional dimensions so that commercial leaders can identify where to concentrate sales effort, where to streamline SKU counts, and where localized manufacturing or distribution partnerships may reduce exposure to freight volatility and import friction. Third, it frames the competitive field in terms of concentration, specialization, and recent innovation signals, enabling strategy teams to assess where head-to-head competition is most likely to compress pricing and where niche engineering or procedural focus can preserve value.
Equally important, the report translates industrial realities into commercial implications. By addressing the role of surgical-grade stainless steel, autoclave compatibility, design conventions such as Polansky and Killian configurations, and the regulatory distinction between animal-use devices and human-use equivalents, it helps product and quality leaders anticipate the operational prerequisites for scale-up, supplier qualification, and market entry. This level of detail is intended to reduce the gap between strategic ambition and execution risk.
For executives evaluating expansion into new practice types or geographies, the research also clarifies where demand is deepening versus where it is merely price-sensitive. Understanding this distinction is essential for deciding whether to compete on throughput and cost efficiency or to invest in clinical value propositions that justify premium positioning. The study does not offer generic advice; it provides a structured foundation for making that choice with greater confidence.
Looking Ahead: Positioning for Sustained, Predictable Growth
The veterinary speculums market is not characterized by sudden disruptive swings, but it is increasingly shaped by procedural refinement, material expectations, and competitive maturation. The forecast window to 2032 suggests a market that will continue to expand in a measured way, with total revenue advancing from approximately 194 million in 2026 toward the mid-260 million range by the end of the decade. Translating that trajectory into a viable corporate strategy requires more than awareness of the growth rate. It requires a working knowledge of the segmentation logic, competitive archetypes, material constraints, and procedural preferences that will determine which companies capture disproportionate value along the way.
Our full report extends far beyond the high-level framework summarized here. It contains the detailed segmentation analysis, competitive profiling, regional demand context, and operational implications that procurement, product, and strategy teams need to build defensible plans for 2026 and beyond. Readers seeking the complete dataset, deeper competitive evaluations, and the full set of market dynamics discussed in this introduction are encouraged to access the source publication for the full intelligence package. In a market where margin protection and product relevance depend on precise market understanding, that deeper view is not a luxury; it is a strategic necessity.
Worldwide Veterinary Endoscopes Market
For detailed analysis of this topic, please visit the official page: Veterinary Speculums Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Candy Displays Market to Hit $666.88M by 2032, Growing at 4.2% CAGR
By pmarketresearch, 2026-09-17
The Candy Displays Market in 2026: Strategic Intelligence for Retail Merchandising Decision-Makers
From Shelf Impact to Supply Chain Resilience: Why the 2026 Landscape Demands Precision Planning
The candy and confectionery aisle has evolved far beyond passive shelving. In 2026, point-of-sale merchandising is a strategic lever for brand differentiation, basket building, and operational efficiency. The candy displays market reflects this transformation, with total industry revenue reaching approximately 500.00 million USD in 2025 and climbing to an estimated 520.38 million USD in 2026. Over the 2026-2032 forecast period, the market is projected to grow at a compound annual growth rate of 4.2 percent, culminating in a valuation that underscores sustained capital deployment across retail fixtures, custom POP solutions, and next-generation display architectures.
For executives navigating procurement, category management, facility design, and brand partnerships, these figures are only the starting point. The real strategic value lies in understanding how material selection, end-user behavior, regional demand patterns, competitive positioning, and regulatory pressures interact to shape total cost of ownership and in-store performance. Our latest Candy Displays Market research report distills this complexity into an actionable decision framework. It is designed not as a static data sheet, but as a working intelligence asset for merchandising directors, supply chain leaders, private-label strategists, and retail expansion teams who must allocate budget with precision while anticipating structural shifts in packaging, sustainability, and consumer engagement.
Candy Displays Market
This article previews the analytical depth of the full study. It highlights the market trajectory, the operational dimensions covered in the report, the competitive forces reshaping supply, and the regulatory and materials dynamics that will influence sourcing strategies through the end of the decade. As always, the detailed segmentation tables, proprietary forecasts, and company-by-company benchmarks remain exclusive to the report, where they are presented in formats built for boardroom discussion and category-level planning.
The Trajectory: Reading the Numbers as a Strategic Signal, Not Just a Trend Line
Market growth is rarely linear, and the candy displays segment is no exception. Historical data from 2020 through 2025 reveals a pattern of recovery, consolidation, and selective acceleration. Total revenue moved from 412.35 million USD in 2020 to 438.27 million USD in 2021, experienced a short-term correction to 431.50 million USD in 2022, and then resumed a steadier climb through 2023, 2024, and 2025. This trajectory signals more than post-pandemic normalization. It reflects structural demand for higher-performing merchandising assets, the expansion of impulse-driven formats, and a broader retail shift toward experiential, visually optimized confectionery zones.
The forecast period from 2026 to 2032 extends this logic. Growth compounds steadily as retailers and manufacturers invest in displays that do more than hold product. They guide purchase decisions, support promotional architecture, and adapt to changing store footprints. The compound annual growth rate of 4.2 percent may appear measured, but in a mature segment it indicates durable demand rather than speculative hype. For decision-makers, the implication is clear: incremental budget increases must be paired with smarter specification choices, because the efficiency of each display asset now matters as much as the total spend.
This report treats the numbers as a foundation for scenario planning. It maps how demand indices connect to material preferences, store formats, and regional expansion priorities, enabling teams to pressure-test assumptions rather than accept headline figures at face value. The goal is to help organizations align display investments with broader commercial objectives, whether those involve premiumization, cost containment, faster seasonal turnarounds, or omnichannel consistency.
What the Report Delivers: A Working Toolkit for Merchandising, Sourcing, and Capital Allocation
The study is built around practical application. Instead of stopping at top-line forecasts, it walks through the operational dimensions that determine how display investments perform in real retail environments. The report examines the market along multiple decision-critical axes, including material choices, end-user adoption patterns, and regional demand variation, while integrating supplier capability profiles and recent industry developments. Each section is structured to support concrete actions: specification benchmarking, sourcing strategy refinement, retail format alignment, and risk assessment.
Material analysis is central to this framework. Different substrates create different tradeoffs across durability, aesthetics, weight, lead time, and sustainability compliance. The report evaluates how acrylic, metal, wood and cardboard, and glass each fit into specific merchandising contexts, without reducing the discussion to simplistic cost comparisons. Instead, it considers where each material performs best in terms of shelf impact, maintenance burden, recyclability pathways, and compatibility with automated or modular fixtures. For procurement teams, this means clearer criteria for selecting display families that align with store conditions, brand guidelines, and total lifecycle cost.
End-user analysis adds another layer of operational relevance. The report assesses how major retail channels approach candy displays, from high-throughput environments where speed, density, and ease of replenishment matter most, to specialty settings where presentation quality, brand storytelling, and tactile customer experience take priority. It also examines convenience-oriented formats and other emerging channels that require compact footprints, flexible merchandising, and rapid seasonal adaptation. By connecting channel behavior to display requirements, the study helps teams avoid the common mistake of applying a single fixture strategy across dissimilar retail settings.
Regional analysis is presented with the same decision-oriented logic. Rather than treating geography as a set of disconnected numbers, the report interprets regional variation as a reflection of retail maturity, store expansion dynamics, local sourcing feasibility, and regulatory exposure. This approach supports more realistic market-entry evaluations, distribution planning, and partner selection for organizations operating across multiple territories or considering cross-border sourcing strategies.
Beyond the structural breakdowns, the report integrates recent market activities that signal where the industry is heading. It references high-visibility events such as the 2026 Sweets & Snacks Expo in Las Vegas, where more than 1,000 exhibitors showcased candy displays, merchandising innovations, and packaging developments. It also tracks product-level observations, including dual-brand display towers seen in retail settings, the release of creative POP strategies aimed at boosting retail sales, and ongoing deployment of modular, robot-built merchandising displays by major manufacturers. These developments are not included as isolated news items. They are used as indicators of broader shifts in customization, automation, co-branding, and retail readiness.
The report also embeds macroeconomic and regulatory context into its analysis. Materials pricing signals, including recent movements in plastics packaging and containerboard costs, are discussed as variables that affect fixture economics and sourcing timing. Regulatory developments, such as extended producer responsibility initiatives across multiple U.S. states and packaging reduction mandates with 2032 targets, are framed as strategic considerations that influence material selection, supplier qualification, and long-term compliance planning. In short, the report treats display purchasing as a decision that sits at the intersection of design, operations, sustainability, and risk management.
Competitive Dynamics: A Fragmented Field Shaped by Specialization and Innovation
The candy displays market remains notably fragmented. Concentration metrics show that the top three firms account for roughly 28.5 percent of market share, while the top five firms reach approximately 35.8 percent. This structure matters for strategy. It indicates that no single participant dominates the category, that regional and functional specialization continue to create viable competitive positions, and that buyers can benefit from diversified sourcing relationships if they evaluate suppliers against the right criteria.
The competitive landscape includes a mix of specialized display manufacturers, packaging-oriented design firms, and major confectionery producers with in-house merchandising capabilities. Several U.S.-based companies emphasize specialized candy retail fixtures, acrylic bins, countertop and floor displays, hinged containers, dispensers, LED-enhanced racks, and custom store solutions. Their positioning often centers on merchandising precision, speed of deployment, and channel-specific design expertise. At the same time, leading Chinese manufacturers contribute strong capabilities in custom display stands, POP structures, cardboard and metal fixtures, multi-tier shelving, and scalable retail interior solutions. Their role in the market highlights the importance of evaluating supplier base geography not only for cost, but also for design flexibility, production capacity, and compliance alignment.
What distinguishes the current competitive environment is the growing overlap between display manufacturing and broader merchandising innovation. Some vendors focus on modular, customizable systems that can be reconfigured for promotional calendars or seasonal assortments. Others emphasize integrated solutions that combine structural design with brand activation, such as dual-brand installations or co-developed fixtures for retail partners. The report examines these differences in detail, mapping company profiles to the capabilities that matter most for procurement and category strategy. Rather than presenting a simple vendor directory, it interprets each participant through the lens of operational fit: what they build well, what channels they serve, where they are likely to add value, and where limitations may arise depending on the buyer’s priorities.
Recent developments reinforce the idea that competition is increasingly expressed through execution speed and design responsiveness. Creative POP strategies, custom display concepts, and robotics-informed merchandising programs all point to a market in which differentiation is tied to adaptability. For retailers and brands, the strategic question is no longer whether to invest in candy displays, but how to select partners and specifications that can keep pace with changing promotional cycles, store layouts, and consumer expectations. The report provides a comparative lens for answering that question without relying on generic vendor claims.
Regulatory and Materials Signals: Why Sourcing Strategy Must Be Forward-Looking
One of the most valuable contributions of the research is its integration of supply-side and regulatory signals into the market narrative. Candy displays do not exist in a vacuum. They are affected by resin pricing, packaging material volatility, state-level sustainability mandates, and evolving expectations around end-of-life responsibility. As of 2026, these forces are becoming more than background conditions; they are increasingly decisive in specification and sourcing decisions.
Materials data offers a clear example. Recent producer price indicators for plastics packaging products and plastics material and resins manufacturing show elevated levels that can influence the cost structure of acrylic and other resin-based display components. At the same time, containerboard price volatility has introduced uncertainty for cardboard-based solutions. For procurement teams, this means that material decisions cannot be optimized solely on upfront unit cost. They must account for price swings, lead-time variability, and the possibility that a seemingly economical choice today may carry higher exposure tomorrow. The report translates these dynamics into procurement-relevant guidance, helping buyers assess which material families offer the best balance of performance and cost stability under different sourcing scenarios.
On the regulatory side, the growing patchwork of extended producer responsibility laws across multiple U.S. states adds complexity to display design and packaging choices. Requirements affecting plastics and paper-based materials are increasingly shaping what can be used, how it is disposed or recycled, and what documentation suppliers must support. In parallel, high-profile packaging mandates with 2032 targets are accelerating attention on recyclability, compostability, and material reduction for single-use applications. For candy displays, these trends have direct implications. They influence substrate selection, supplier qualification, and the durability-versus-sustainability balance that many merchandising teams now need to manage.
The strategic takeaway is that compliance and sourcing strategy should be integrated early, not retrofitted after specifications are finalized. The report addresses this by framing regulatory exposure as part of the decision matrix alongside cost, aesthetics, functionality, and lead time. This is especially important for organizations operating in multiple jurisdictions or considering long-term display programs where regulatory drift could affect total program economics.
Why the Full Study Matters for 2026 Decision-Making
A top-line forecast can confirm that the candy displays market is expanding, but it cannot tell a merchandising director which display family deserves budget priority, nor can it help a sourcing leader evaluate whether a given supplier’s capabilities match a new retail format. That is the gap this research is designed to close. The full study provides the granularity required to make informed choices across material selection, channel alignment, regional planning, and supplier evaluation.
For companies planning 2026 and beyond, the report supports several concrete decisions. It helps teams forecast demand with greater confidence by placing the 2026-2032 trajectory in the context of historical variability and current industry momentum. It aids specification decisions by comparing material families within the operational realities of different retail settings. It informs sourcing strategies by interpreting competitive fragmentation, supplier profiles, and recent innovation signals in a way that supports partner selection rather than ad hoc purchasing. And it strengthens risk planning by embedding materials cost behavior and regulatory developments into the same analysis as demand growth.
The report is also structured to support internal alignment. Because it moves from market structure to competitive dynamics to operational risks, it gives cross-functional teams a shared reference point. Category managers, procurement leaders, finance stakeholders, and sustainability teams can all use the same intelligence base, each through the lens most relevant to their responsibilities. That shared context is often the difference between fragmented purchasing decisions and a coherent display strategy.
Worldwide Home Display Case Market
Conclusion: Turn Market Momentum into Disciplined Execution
The candy displays market is entering a phase in which growth is supported not only by demand, but by continuous innovation in materials, design, and merchandising execution. The combination of steady projection, fragmented competition, and intensifying materials and regulatory pressures makes this a landscape where informed judgment outperforms intuitive procurement. Our upcoming research report is built for that environment. It offers the strategic scaffolding needed to interpret the market, evaluate suppliers, and plan display investments with discipline.
The detailed segmentation analysis, proprietary company assessments, and forward-looking scenario frameworks are reserved for the full report. Readers seeking a complete view of the candy displays market for 2026 decision-making are encouraged to access the source page, where the full intelligence package is available for download and review.
For detailed analysis of this topic, please visit the official page: Candy Displays Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Horizontal Freezer Market Hits $4.8B in 2025 to Reach $6.5B by 2032 at 4.5% CAGR
By pmarketresearch, 2026-09-17
Navigating the Cold Chain: Strategic Imperatives in the Global Horizontal Freezer Market (2026–2032)
The worldwide horizontal freezer market stands at a critical inflection point as we move into 2026. Defined by steady revenue expansion, shifting regulatory frameworks, and an increasingly fragmented competitive landscape, this segment demands precise strategic positioning from manufacturers, distributors, and commercial end-users alike. Our newly released market research, Worldwide Horizontal Freezer Market , dissects the operational, technological, and macroeconomic forces shaping the sector across a seven-year forecast horizon. This introductory briefing outlines the strategic architecture of the study, demonstrates how the data maps to executive decision-making, and previews the competitive and regulatory dynamics that will separate resilient players from those left adjusting after the fact.
Market Trajectory: From Baseline to Forecast Horizon
The sector has established a consistent growth cadence over the past half-decade. Between 2020 and 2025, global revenue expanded from approximately 3,850.5 million USD to a 2025 baseline of 4,800.0 million USD, reflecting cumulative demand pull from both household and commercial refrigeration channels. The trajectory does not plateau at the baseline; instead, the forecast period 2026–2032 positions the market to reach roughly 6,532.1 million USD by the terminal year.
This path translates into a compound annual growth rate of approximately 4.5 percent across the forecast window. For strategic planners, that mid-single-digit rate carries meaningful implications. It signals steady, rather than explosive, expansion—an environment where incremental share gains, product mix optimization, and regional deployment prioritization deliver more reliable returns than broad undifferentiated capacity additions. The report’s time-series modeling decomposes this trajectory into year-by-year revenue estimates, allowing leadership teams to test capex phasing, inventory planning, and channel investment against a quantified demand curve rather than static growth assumptions.
Importantly, the forecast treats the 2025 base year as a calibrated anchor, drawing on historical enumeration from 2020 through 2025 to validate trend continuity before extrapolating forward. Decision-makers can therefore interrogate the data for inflection sensitivity: how regulatory change, raw-material volatility, or regional substitution patterns might bend the curve away from baseline assumptions.
Segmentation Architecture: Where Growth Concentrates and How It Splits
Revenue concentration and end-use balance define the structural shape of the market. The overall landscape reflects meaningful bifurcation across defrost architecture and end-user profiles, while regional deployment patterns reveal where volume and margin strategy must diverge.
The defrost-type segment underscores a mature core alongside a higher-growth alternative. Manual defrost horizontal freezers represented a substantial 2025 revenue base of approximately 3,617.2 million USD, reflecting entrenched demand in cost-sensitive residential channels, bulk storage use cases, and commercial environments where active defrost management is operationally acceptable. Frost-free configurations generated approximately 1,182.8 million USD, indicating a smaller but strategically distinct niche oriented toward convenience-driven applications and retail-facing reliability expectations. The report quantifies how these two streams interact across price tiers, capacity classes, and regional purchasing behavior, giving product planners a precise map of where defrost architecture drives purchase decisions versus where it functions as a compliance or service-feature afterthought.
End-user segmentation further clarifies demand architecture. Residential applications accounted for roughly 2,899.6 million USD in 2025, anchoring the market in household bulk storage, convenience-driven convertible models, and consumer upgrades tied to kitchen-renovation cycles. Commercial applications contributed approximately 1,900.4 million USD, spanning food retail, frozen food merchandising, hospitality back-of-house storage, and light food service environments. The commercial share may be smaller in absolute terms but carries disproportionate strategic weight because it concentrates in higher unit-value deployments, longer replacement cycles, and tighter regulatory exposure. Our study separates these streams to show where channel economics, specification requirements, and service expectations diverge, enabling executives to allocate commercial-team resources and configurator capabilities accordingly.
Regional deployment patterns show Asia Pacific leading in 2025 revenue contribution at approximately 1,901.1 million USD, followed by North America at roughly 1,205.8 million USD and Europe at approximately 1,068.3 million USD, with Latin America and the Middle East and Africa representing smaller but strategically relevant volumes of about 386.8 million USD and 238.0 million USD respectively. These figures are presented not as static rankings but as strategic coordinates. The research uses them to examine how supply-chain geography, trade flows, energy-cost environments, and local regulatory pacing alter the attractiveness of each territory. Readers seeking granular regional breakdowns—including sub-market revenue splits, penetration patterns, and territory-specific growth drivers—will find the full report’s regional chapters structured to support market-entry prioritization and capacity-allocation decisions.
Competitive Landscape: Concentration, Portfolio Strategy, and Differentiation Vectors
Market concentration data provides an early signal of how the competitive structure is evolving. The three-firm concentration ratio stands at approximately 32.5 percent, while the five-firm ratio reaches roughly 48.8 percent. That profile indicates a market with meaningful room for challenger positioning alongside established incumbents, where portfolio breadth, energy-efficiency storytelling, and regional manufacturing footprint can tilt competitive outcomes more than pure scale alone.
The report profiles the organizations shaping this landscape across multiple strategic dimensions. Haier Group Corporation, headquartered in Qingdao, China, occupies a broad horizontal freezer position spanning household and commercial use, with product architectures ranging across multiple capacity tiers and engineering features such as adjustable thermostats, frost-retention design, and dual-condenser configurations aimed at reliable bulk frozen storage. Liebherr Group, based in Bulle, Switzerland, emphasizes commercial merchandising and deep-freezer solutions for food retail, ice cream, and frozen food channels, with a product philosophy centered on durability through high-quality materials, energy efficiency, and R290 refrigerant options that align with low-global-warming-potential requirements.
Electrolux AB, headquartered in Stockholm, Sweden, extends its horizontal chest freezer presence through brands including Frigidaire, focusing on convertible models and professional and commercial refrigeration solutions for food service and retail environments. Whirlpool Corporation, from Benton Harbor, USA, builds differentiation around convertible chest freezers that alternate between freezer and refrigerator modes, alongside standard horizontal designs incorporating fast-freeze functions and multi-level storage for residential and light commercial applications.
On the industrial-production side, Ningbo HICON Industrial Technology Co., Ltd., located in Ningbo, China, specializes in compact and horizontal chest freezer designs within household and commercial refrigeration production, with annual capacity supporting large-scale output of top-open configurations. Guangzhou Wanbao Group Refrigerator Co., Ltd., operating from Guangzhou, China, manufactures chest freezers, commercial freezers, and related refrigeration products across multiple bases, targeting diverse scenarios including large-capacity horizontal units. Shandong Hongsheng Electrical Appliance Co., Ltd. (Shengxue Freezer), based in Binzhou, China, concentrates on commercial chest freezers, island freezers, and deep freezers for supermarkets, hotels, and food retail, with stainless steel and large-capacity horizontal models positioned for high-throughput commercial settings.
In the specialized commercial refrigeration tier, FREOR from Vilnius, Lithuania, develops commercial refrigeration platforms including long horizontal freezer islands such as the NDL HELLA ED series, alongside ENERGY models engineered for enhanced efficiency in supermarket and retail display applications. Panasonic Corporation, headquartered in Osaka, Japan, supplies commercial-grade chest freezers and refrigeration equipment for food service and retail, emphasizing energy-efficient and reliable horizontal storage solutions.
The competitive analysis within the report goes beyond descriptive profiling. It evaluates where each player is most exposed to regulatory shifts, where portfolio breadth creates cross-selling leverage, where geographic manufacturing concentration affects landed-cost competitiveness, and where feature adjacency—convertibility, fast-freeze, island merchandising, energy-labeled efficiency—creates defensible positioning. For executives evaluating partnership, procurement, or competitive response, this structure turns a crowded vendor field into a decision-ready map.
Dynamics and Disruption: Regulation, Materials, and Technology Adoption
The horizontal freezer market does not evolve in a vacuum. Three interconnected force vectors—regulatory tightening, input-cost volatility, and refrigerant/technology migration—are actively reshaping specification standards, total-cost-of-ownership math, and product roadmaps.
Worldwide Walk-In Freezers Market
On the regulatory front, commercial refrigeration equipment faces a defined compliance trajectory in the United States. The U.S. Department of Energy final rule on energy conservation standards for commercial refrigerators, freezers, and refrigerator-freezers became effective in March 2025, with full compliance for new and amended levels required on or after January 2029. This creates a multi-year runway for product redesign, testing, and portfolio re-validation. India’s Bureau of Energy Efficiency has simultaneously implemented revised energy-consumption limits and star-rating bands for chest freezers, effective from early 2026 through the end of 2028. For manufacturers operating across multiple jurisdictions, the practical challenge is not a single standard but a staggered set of requirements that alter specification priorities and test-and-certification pipelines. The report maps these regulatory calendars to product-cycle risk, showing where compliance lead times intersect with model refresh schedules and where early adoption can convert a constraint into a commercial differentiator.
Input-cost dynamics reinforce the importance of build-cost discipline. In the U.S. Midwest, hot-rolled coil steel prices—a key input for freezer cabinet construction—stood at approximately 1,012 USD per short ton in early 2026. Steel and related metal components directly influence unit economics, particularly for horizontal freezers where cabinet volume, insulation integration, and structural durability are core to value propositions. The study incorporates materials-cost sensitivity into the strategic commentary, highlighting how regional sourcing, gauge optimization, and design-for-manufacturing choices can buffer margin exposure when input markets fluctuate.
Technology and refrigerant adoption form the third vector. Commercial refrigeration manufacturers are increasingly adopting R290 propane refrigerant in horizontal chest freezers to meet energy-efficiency expectations and low-GWP requirements under updated standards. This transition is not merely a compliance checkbox; it affects charge limits, safety engineering, component selection, and in some cases product architecture. The research situates R290 adoption within a broader commercial-efficiency trend, showing where it aligns with regulatory pacing, where it enhances total-cost-of-ownership positioning, and where it influences downstream installer and service requirements.
Recent industry activity reinforces the immediacy of these dynamics. In early 2026, FREOR showcased long horizontal freezer islands, including NDL HELLA ED ENERGY models, island combinations, and a reengineered ENERGY series achieving up to 50 percent greater energy efficiency at EuroShop 2026 in Düsseldorf. Demonstrations of that scale matter because they signal where commercial retail display is heading: longer island formats, visible efficiency branding, and engineered performance gains that translate into operating-cost competition. The report connects such exhibition activity to the broader commercial-segment narrative, helping readers distinguish marketing theater from product-direction signals.
What the Study Delivers: Operational Content for Executive and Commercial Teams
The Worldwide Horizontal Freezer Market study is built around actionable decomposition rather than headline aggregation. It provides a structured toolkit for teams tasked with capacity planning, product strategy, competitive intelligence, and market-entry evaluation.
Worldwide Horizontal Freezer Market
At the core is a fully enumerated market model covering the historical window from 2020 through 2025 and the forecast period from 2026 through 2032. The model delivers year-by-year revenue estimates in million USD, anchored to the 2025 base year and extended by a 4.5 percent CAGR trajectory to 2032. This time-series structure allows teams to run scenario overlays—regulatory delay, input-cost pressure, regional demand shift—and see how the curve responds rather than relying on fixed growth narratives.
The segmentation chapters break the market into defrost type, end-user profile, and regional deployment, with a deliberate emphasis on how each axis interacts with pricing, specification, and channel behavior. Readers gain a clear view of where manual defrost stability competes with frost-free convenience, where residential volume supports baseline demand while commercial deployments concentrate higher specification requirements, and where regional market size translates into prioritization inputs for regional business planning.
The competitive section profiles the key players shaping the market, tying each organization’s product philosophy, geographic base, and commercial focus to strategic implications. Rather than presenting flat company summaries, the analysis frames each competitor in terms of portfolio logic, differentiation vectors, and probable response patterns under shifting efficiency and refrigerant standards. Recent developments are integrated where they signal durable change, including trade-show demonstrations that redefine commercial display expectations and regulatory notices that reset compliance timelines.
Beyond the core segmentation and competitive material, the study incorporates industry-context drivers into the strategic narrative. Steel-input cost behavior, U.S. and India energy-efficiency rule trajectories, and the broader shift toward R290 refrigerant are not siloed as side facts; they are woven into the analysis of pricing strategy, product design trade-offs, and region-specific compliance planning. For procurement teams, this means a clearer view of where build-cost exposure concentrates. For product teams, it means a practical map of where redesign timelines should begin. For commercial leaders, it means a structured basis for positioning efficiency claims and compliance readiness in buyer conversations.
The report is also designed for selective use. Executive summaries and trend narratives support board-level and strategy-offsite discussion. Segmentation and time-series tables support forecasting and resource allocation. Competitive profiles and development tracking support sales enablement, partner evaluation, and threat assessment. In each case, the underlying intent is the same: convert macro movement into decision-grade structure.
Strategic Takeaways for 2026 Decision-Making
The horizontal freezer market in 2026 is best approached as a steady-growth, highly structured environment where advantage comes from precision rather than volume alone. Several implications follow directly from the research framework.
First, the mid-single-digit growth path rewards disciplined portfolio management. With revenue moving from a 4,800.0 million USD base toward a 2032 terminal value near 6,532.1 million USD, the largest returns will accrue to organizations that optimize mix across defrost type, capacity class, and end-user channel rather than chase undifferentiated unit volume. The segmentation detail in the study helps leaders identify where convertible residential models, commercial island displays, or bulk storage configurations deserve differentiated roadmaps.
Second, regulatory pacing is a planning variable, not a distant concern. With U.S. commercial refrigeration standards requiring full compliance for new and amended levels from January 2029 and India’s revised chest-freezer energy limits active through 2028, product teams should already be mapping redesign, testing, and certification calendars against current model lifecycles. Early alignment can protect launch timing; late alignment can compress margin and create inventory exposure.
Third, efficiency and refrigerant strategy are becoming purchase criteria in commercial channels. The growing visibility of R290 adoption and the demonstration of substantially improved energy efficiency in commercial island formats indicate that operating-cost positioning increasingly sits alongside storage capacity and durability in buyer evaluations. Commercial teams should treat efficiency as a specification story with measurable total-cost-of-ownership implications, especially where electricity cost and uptime sensitivity are pronounced.
Fourth, competitive positioning will increasingly hinge on how well firms combine geographic manufacturing leverage, portfolio breadth, and targeted efficiency differentiation. With a three-firm concentration ratio around 32.5 percent and a five-firm ratio near 48.8 percent, the market leaves space for challengers that can execute in niche commercial applications, convertible residential segments, or cost-optimized high-volume horizontal designs. The report’s competitive structure helps leadership teams see where incumbents are most exposed and where challenger plays can gain traction.
Finally, input-cost awareness matters for realistic margin planning. Steel-price levels and related materials exposure feed directly into cabinet build economics, and the study places that sensitivity in context so that pricing, sourcing, and design-for-manufacturing decisions can be evaluated against a real market backdrop rather than static assumptions.
Accessing the Full Intelligence
This briefing has outlined the strategic shape of the worldwide horizontal freezer market, the structural segmentation that defines it, the competitive logic now in play, and the regulatory and materials dynamics that will discipline execution through 2032. What it has deliberately not done is reproduce the granular regional sub-splits, detailed defrost-type revenue breakdowns by territory, end-user distribution by country, or the company-by-company strategic scorecards that underpin the study’s decision tools. Those layers are where strategic detail becomes operational advantage.
The full Worldwide Horizontal Freezer Market report delivers that complete architecture: time-series revenue estimation, segmentation-level decomposition, competitive intelligence profiles, regulatory calendars, materials-sensitivity context, and recent-development tracking integrated into a single decision framework. For executives building 2026 investment plans, commercial teams refining positioning, and product leaders scheduling redesign cycles, the report is structured to convert market movement into concrete action.
Access the complete dataset, segmentation matrices, and competitive analysis to turn this high-level trajectory into a calibrated, defensible strategy for the forecast period ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Horizontal Freezer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com