

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Horizontal Freezer Market Hits $4.8B in 2025 to Reach $6.5B by 2032 at 4.5% CAGR

Navigating the Cold Chain: Strategic Imperatives in the Global Horizontal Freezer Market (2026–2032)
The worldwide horizontal freezer market stands at a critical inflection point as we move into 2026. Defined by steady revenue expansion, shifting regulatory frameworks, and an increasingly fragmented competitive landscape, this segment demands precise strategic positioning from manufacturers, distributors, and commercial end-users alike. Our newly released market research, Worldwide Horizontal Freezer Market , dissects the operational, technological, and macroeconomic forces shaping the sector across a seven-year forecast horizon. This introductory briefing outlines the strategic architecture of the study, demonstrates how the data maps to executive decision-making, and previews the competitive and regulatory dynamics that will separate resilient players from those left adjusting after the fact.
Market Trajectory: From Baseline to Forecast Horizon
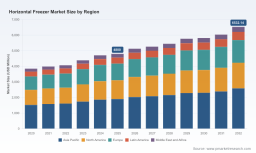
The sector has established a consistent growth cadence over the past half-decade. Between 2020 and 2025, global revenue expanded from approximately 3,850.5 million USD to a 2025 baseline of 4,800.0 million USD, reflecting cumulative demand pull from both household and commercial refrigeration channels. The trajectory does not plateau at the baseline; instead, the forecast period 2026–2032 positions the market to reach roughly 6,532.1 million USD by the terminal year.
This path translates into a compound annual growth rate of approximately 4.5 percent across the forecast window. For strategic planners, that mid-single-digit rate carries meaningful implications. It signals steady, rather than explosive, expansion—an environment where incremental share gains, product mix optimization, and regional deployment prioritization deliver more reliable returns than broad undifferentiated capacity additions. The report’s time-series modeling decomposes this trajectory into year-by-year revenue estimates, allowing leadership teams to test capex phasing, inventory planning, and channel investment against a quantified demand curve rather than static growth assumptions.
Importantly, the forecast treats the 2025 base year as a calibrated anchor, drawing on historical enumeration from 2020 through 2025 to validate trend continuity before extrapolating forward. Decision-makers can therefore interrogate the data for inflection sensitivity: how regulatory change, raw-material volatility, or regional substitution patterns might bend the curve away from baseline assumptions.
Segmentation Architecture: Where Growth Concentrates and How It Splits
Revenue concentration and end-use balance define the structural shape of the market. The overall landscape reflects meaningful bifurcation across defrost architecture and end-user profiles, while regional deployment patterns reveal where volume and margin strategy must diverge.
The defrost-type segment underscores a mature core alongside a higher-growth alternative. Manual defrost horizontal freezers represented a substantial 2025 revenue base of approximately 3,617.2 million USD, reflecting entrenched demand in cost-sensitive residential channels, bulk storage use cases, and commercial environments where active defrost management is operationally acceptable. Frost-free configurations generated approximately 1,182.8 million USD, indicating a smaller but strategically distinct niche oriented toward convenience-driven applications and retail-facing reliability expectations. The report quantifies how these two streams interact across price tiers, capacity classes, and regional purchasing behavior, giving product planners a precise map of where defrost architecture drives purchase decisions versus where it functions as a compliance or service-feature afterthought.
End-user segmentation further clarifies demand architecture. Residential applications accounted for roughly 2,899.6 million USD in 2025, anchoring the market in household bulk storage, convenience-driven convertible models, and consumer upgrades tied to kitchen-renovation cycles. Commercial applications contributed approximately 1,900.4 million USD, spanning food retail, frozen food merchandising, hospitality back-of-house storage, and light food service environments. The commercial share may be smaller in absolute terms but carries disproportionate strategic weight because it concentrates in higher unit-value deployments, longer replacement cycles, and tighter regulatory exposure. Our study separates these streams to show where channel economics, specification requirements, and service expectations diverge, enabling executives to allocate commercial-team resources and configurator capabilities accordingly.
Regional deployment patterns show Asia Pacific leading in 2025 revenue contribution at approximately 1,901.1 million USD, followed by North America at roughly 1,205.8 million USD and Europe at approximately 1,068.3 million USD, with Latin America and the Middle East and Africa representing smaller but strategically relevant volumes of about 386.8 million USD and 238.0 million USD respectively. These figures are presented not as static rankings but as strategic coordinates. The research uses them to examine how supply-chain geography, trade flows, energy-cost environments, and local regulatory pacing alter the attractiveness of each territory. Readers seeking granular regional breakdowns—including sub-market revenue splits, penetration patterns, and territory-specific growth drivers—will find the full report’s regional chapters structured to support market-entry prioritization and capacity-allocation decisions.
Competitive Landscape: Concentration, Portfolio Strategy, and Differentiation Vectors
Market concentration data provides an early signal of how the competitive structure is evolving. The three-firm concentration ratio stands at approximately 32.5 percent, while the five-firm ratio reaches roughly 48.8 percent. That profile indicates a market with meaningful room for challenger positioning alongside established incumbents, where portfolio breadth, energy-efficiency storytelling, and regional manufacturing footprint can tilt competitive outcomes more than pure scale alone.
The report profiles the organizations shaping this landscape across multiple strategic dimensions. Haier Group Corporation, headquartered in Qingdao, China, occupies a broad horizontal freezer position spanning household and commercial use, with product architectures ranging across multiple capacity tiers and engineering features such as adjustable thermostats, frost-retention design, and dual-condenser configurations aimed at reliable bulk frozen storage. Liebherr Group, based in Bulle, Switzerland, emphasizes commercial merchandising and deep-freezer solutions for food retail, ice cream, and frozen food channels, with a product philosophy centered on durability through high-quality materials, energy efficiency, and R290 refrigerant options that align with low-global-warming-potential requirements.
Electrolux AB, headquartered in Stockholm, Sweden, extends its horizontal chest freezer presence through brands including Frigidaire, focusing on convertible models and professional and commercial refrigeration solutions for food service and retail environments. Whirlpool Corporation, from Benton Harbor, USA, builds differentiation around convertible chest freezers that alternate between freezer and refrigerator modes, alongside standard horizontal designs incorporating fast-freeze functions and multi-level storage for residential and light commercial applications.
On the industrial-production side, Ningbo HICON Industrial Technology Co., Ltd., located in Ningbo, China, specializes in compact and horizontal chest freezer designs within household and commercial refrigeration production, with annual capacity supporting large-scale output of top-open configurations. Guangzhou Wanbao Group Refrigerator Co., Ltd., operating from Guangzhou, China, manufactures chest freezers, commercial freezers, and related refrigeration products across multiple bases, targeting diverse scenarios including large-capacity horizontal units. Shandong Hongsheng Electrical Appliance Co., Ltd. (Shengxue Freezer), based in Binzhou, China, concentrates on commercial chest freezers, island freezers, and deep freezers for supermarkets, hotels, and food retail, with stainless steel and large-capacity horizontal models positioned for high-throughput commercial settings.
In the specialized commercial refrigeration tier, FREOR from Vilnius, Lithuania, develops commercial refrigeration platforms including long horizontal freezer islands such as the NDL HELLA ED series, alongside ENERGY models engineered for enhanced efficiency in supermarket and retail display applications. Panasonic Corporation, headquartered in Osaka, Japan, supplies commercial-grade chest freezers and refrigeration equipment for food service and retail, emphasizing energy-efficient and reliable horizontal storage solutions.
The competitive analysis within the report goes beyond descriptive profiling. It evaluates where each player is most exposed to regulatory shifts, where portfolio breadth creates cross-selling leverage, where geographic manufacturing concentration affects landed-cost competitiveness, and where feature adjacency—convertibility, fast-freeze, island merchandising, energy-labeled efficiency—creates defensible positioning. For executives evaluating partnership, procurement, or competitive response, this structure turns a crowded vendor field into a decision-ready map.
Dynamics and Disruption: Regulation, Materials, and Technology Adoption
The horizontal freezer market does not evolve in a vacuum. Three interconnected force vectors—regulatory tightening, input-cost volatility, and refrigerant/technology migration—are actively reshaping specification standards, total-cost-of-ownership math, and product roadmaps.
Worldwide Walk-In Freezers Market
On the regulatory front, commercial refrigeration equipment faces a defined compliance trajectory in the United States. The U.S. Department of Energy final rule on energy conservation standards for commercial refrigerators, freezers, and refrigerator-freezers became effective in March 2025, with full compliance for new and amended levels required on or after January 2029. This creates a multi-year runway for product redesign, testing, and portfolio re-validation. India’s Bureau of Energy Efficiency has simultaneously implemented revised energy-consumption limits and star-rating bands for chest freezers, effective from early 2026 through the end of 2028. For manufacturers operating across multiple jurisdictions, the practical challenge is not a single standard but a staggered set of requirements that alter specification priorities and test-and-certification pipelines. The report maps these regulatory calendars to product-cycle risk, showing where compliance lead times intersect with model refresh schedules and where early adoption can convert a constraint into a commercial differentiator.
Input-cost dynamics reinforce the importance of build-cost discipline. In the U.S. Midwest, hot-rolled coil steel prices—a key input for freezer cabinet construction—stood at approximately 1,012 USD per short ton in early 2026. Steel and related metal components directly influence unit economics, particularly for horizontal freezers where cabinet volume, insulation integration, and structural durability are core to value propositions. The study incorporates materials-cost sensitivity into the strategic commentary, highlighting how regional sourcing, gauge optimization, and design-for-manufacturing choices can buffer margin exposure when input markets fluctuate.
Technology and refrigerant adoption form the third vector. Commercial refrigeration manufacturers are increasingly adopting R290 propane refrigerant in horizontal chest freezers to meet energy-efficiency expectations and low-GWP requirements under updated standards. This transition is not merely a compliance checkbox; it affects charge limits, safety engineering, component selection, and in some cases product architecture. The research situates R290 adoption within a broader commercial-efficiency trend, showing where it aligns with regulatory pacing, where it enhances total-cost-of-ownership positioning, and where it influences downstream installer and service requirements.
Recent industry activity reinforces the immediacy of these dynamics. In early 2026, FREOR showcased long horizontal freezer islands, including NDL HELLA ED ENERGY models, island combinations, and a reengineered ENERGY series achieving up to 50 percent greater energy efficiency at EuroShop 2026 in Düsseldorf. Demonstrations of that scale matter because they signal where commercial retail display is heading: longer island formats, visible efficiency branding, and engineered performance gains that translate into operating-cost competition. The report connects such exhibition activity to the broader commercial-segment narrative, helping readers distinguish marketing theater from product-direction signals.
What the Study Delivers: Operational Content for Executive and Commercial Teams
The Worldwide Horizontal Freezer Market study is built around actionable decomposition rather than headline aggregation. It provides a structured toolkit for teams tasked with capacity planning, product strategy, competitive intelligence, and market-entry evaluation.
Worldwide Horizontal Freezer Market
At the core is a fully enumerated market model covering the historical window from 2020 through 2025 and the forecast period from 2026 through 2032. The model delivers year-by-year revenue estimates in million USD, anchored to the 2025 base year and extended by a 4.5 percent CAGR trajectory to 2032. This time-series structure allows teams to run scenario overlays—regulatory delay, input-cost pressure, regional demand shift—and see how the curve responds rather than relying on fixed growth narratives.
The segmentation chapters break the market into defrost type, end-user profile, and regional deployment, with a deliberate emphasis on how each axis interacts with pricing, specification, and channel behavior. Readers gain a clear view of where manual defrost stability competes with frost-free convenience, where residential volume supports baseline demand while commercial deployments concentrate higher specification requirements, and where regional market size translates into prioritization inputs for regional business planning.
The competitive section profiles the key players shaping the market, tying each organization’s product philosophy, geographic base, and commercial focus to strategic implications. Rather than presenting flat company summaries, the analysis frames each competitor in terms of portfolio logic, differentiation vectors, and probable response patterns under shifting efficiency and refrigerant standards. Recent developments are integrated where they signal durable change, including trade-show demonstrations that redefine commercial display expectations and regulatory notices that reset compliance timelines.
Beyond the core segmentation and competitive material, the study incorporates industry-context drivers into the strategic narrative. Steel-input cost behavior, U.S. and India energy-efficiency rule trajectories, and the broader shift toward R290 refrigerant are not siloed as side facts; they are woven into the analysis of pricing strategy, product design trade-offs, and region-specific compliance planning. For procurement teams, this means a clearer view of where build-cost exposure concentrates. For product teams, it means a practical map of where redesign timelines should begin. For commercial leaders, it means a structured basis for positioning efficiency claims and compliance readiness in buyer conversations.
The report is also designed for selective use. Executive summaries and trend narratives support board-level and strategy-offsite discussion. Segmentation and time-series tables support forecasting and resource allocation. Competitive profiles and development tracking support sales enablement, partner evaluation, and threat assessment. In each case, the underlying intent is the same: convert macro movement into decision-grade structure.
Strategic Takeaways for 2026 Decision-Making
The horizontal freezer market in 2026 is best approached as a steady-growth, highly structured environment where advantage comes from precision rather than volume alone. Several implications follow directly from the research framework.
First, the mid-single-digit growth path rewards disciplined portfolio management. With revenue moving from a 4,800.0 million USD base toward a 2032 terminal value near 6,532.1 million USD, the largest returns will accrue to organizations that optimize mix across defrost type, capacity class, and end-user channel rather than chase undifferentiated unit volume. The segmentation detail in the study helps leaders identify where convertible residential models, commercial island displays, or bulk storage configurations deserve differentiated roadmaps.
Second, regulatory pacing is a planning variable, not a distant concern. With U.S. commercial refrigeration standards requiring full compliance for new and amended levels from January 2029 and India’s revised chest-freezer energy limits active through 2028, product teams should already be mapping redesign, testing, and certification calendars against current model lifecycles. Early alignment can protect launch timing; late alignment can compress margin and create inventory exposure.
Third, efficiency and refrigerant strategy are becoming purchase criteria in commercial channels. The growing visibility of R290 adoption and the demonstration of substantially improved energy efficiency in commercial island formats indicate that operating-cost positioning increasingly sits alongside storage capacity and durability in buyer evaluations. Commercial teams should treat efficiency as a specification story with measurable total-cost-of-ownership implications, especially where electricity cost and uptime sensitivity are pronounced.
Fourth, competitive positioning will increasingly hinge on how well firms combine geographic manufacturing leverage, portfolio breadth, and targeted efficiency differentiation. With a three-firm concentration ratio around 32.5 percent and a five-firm ratio near 48.8 percent, the market leaves space for challengers that can execute in niche commercial applications, convertible residential segments, or cost-optimized high-volume horizontal designs. The report’s competitive structure helps leadership teams see where incumbents are most exposed and where challenger plays can gain traction.
Finally, input-cost awareness matters for realistic margin planning. Steel-price levels and related materials exposure feed directly into cabinet build economics, and the study places that sensitivity in context so that pricing, sourcing, and design-for-manufacturing decisions can be evaluated against a real market backdrop rather than static assumptions.
Accessing the Full Intelligence
This briefing has outlined the strategic shape of the worldwide horizontal freezer market, the structural segmentation that defines it, the competitive logic now in play, and the regulatory and materials dynamics that will discipline execution through 2032. What it has deliberately not done is reproduce the granular regional sub-splits, detailed defrost-type revenue breakdowns by territory, end-user distribution by country, or the company-by-company strategic scorecards that underpin the study’s decision tools. Those layers are where strategic detail becomes operational advantage.
The full Worldwide Horizontal Freezer Market report delivers that complete architecture: time-series revenue estimation, segmentation-level decomposition, competitive intelligence profiles, regulatory calendars, materials-sensitivity context, and recent-development tracking integrated into a single decision framework. For executives building 2026 investment plans, commercial teams refining positioning, and product leaders scheduling redesign cycles, the report is structured to convert market movement into concrete action.
Access the complete dataset, segmentation matrices, and competitive analysis to turn this high-level trajectory into a calibrated, defensible strategy for the forecast period ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Horizontal Freezer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com