

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Digital Insurance Market to Reach $321 Billion By 2032, Growing at 14.25% CAGR
By pmarketresearch, 2026-09-17
Navigating the Digital Insurance Transformation: Strategic Intelligence for 2026 and Beyond
The insurance industry is undergoing a fundamental restructuring, driven by the convergence of cloud infrastructure, artificial intelligence, and evolving regulatory demands. As we enter 2026, the distinction between traditional insurers and digital-native competitors is blurring. The ability to process policies, manage claims, and engage customers through fully digital channels is no longer a differentiator; it is a baseline requirement for survival and growth.
PW Consulting's latest Digital Insurance Market report is designed to provide enterprise leaders with the clarity needed to navigate this complex landscape. This research does not merely track revenue figures; it decodes the operational shifts, technological adoption curves, and competitive maneuvers that are defining the next decade of insurance value chains. By integrating historical performance data with forward-looking forecasts, this analysis offers a strategic compass for C-suite executives, product leaders, and investment analysts.
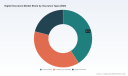
Worldwide Blockchain Insurance Market
Macro Growth Trajectory and Market Scale
The scale of the digital insurance market reflects a sector in hyper-expansion. Building on a robust historical foundation from 2020 through 2025, the market has demonstrated consistent upward momentum. In 2025, the overall market revenue reached 126.36 billion USD, marking a significant increase from 110.6 billion USD in 2024 and 96.5 billion USD in 2023. This trajectory underscores the accelerating digitization of insurance products and services across the global economy.
Looking ahead, the forecast period from 2026 to 2032 projects sustained aggressive growth. The market is expected to climb to 144.37 billion USD in 2026, surpassing 164.94 billion USD by 2027, and reaching 188.45 billion USD by 2028. The long-term outlook remains strong, with revenue projections extending to 321.08 billion USD by 2032. This expansion is underpinned by a compound annual growth rate over the forecast period, signaling that digital transformation is not a temporary trend but a structural shift in how risk is underwritten and managed.
For strategic planners, these figures represent more than just top-line growth. They indicate increasing capital allocation toward digital capabilities, rising customer expectations for seamless digital interactions, and the compounding value of data-driven decision-making. However, capturing this growth requires navigating a fragmented ecosystem of technologies and regional nuances, details of which are fully mapped out in our comprehensive report.
Segmentation Drivers: Technology and Product Dynamics
The market is segmented across multiple dimensions that reveal where value is being created and where competition is most intense. Technological adoption is a primary driver, with cloud computing, AI and machine learning, IoT and telematics, and blockchain solutions forming the backbone of modern insurance operations. The integration of these technologies varies significantly by use case, from core policy administration to real-time claims assessment.
Beyond technology, the composition of insurance types plays a critical role in market dynamics. Life insurance, property and casualty, and health insurance segments each present unique digital challenges and opportunities. The interplay between these segments influences how carriers prioritize investments and how technology vendors tailor their offerings. For instance, the demands of health insurance digitization often diverge sharply from those of property and casualty modernization, requiring distinct strategic approaches.
Our report delves deep into these segmentation splits, providing actionable intelligence on which technologies are gaining traction and how different insurance types are adapting to digital pressures. Rather than presenting static percentages, we analyze the strategic implications of these splits, helping organizations identify where to allocate resources for maximum impact. The full breakdown of these dynamics, including regional influences and application-specific adoption rates, is available in the complete market intelligence package.
Competitive Landscape and Key Players
The competitive environment is characterized by a mix of established platform providers, agile insurtech startups, and traditional insurers undergoing digital transformation. Understanding the positioning of key players is essential for benchmarking and partnership strategies.
Guidewire Software continues to be a pivotal force, providing cloud-based core insurance platforms tailored for property and casualty insurers. Their focus on digital policy administration, claims management, and billing solutions addresses the foundational needs of large carriers modernizing legacy systems. Similarly, Duck Creek Technologies offers a SaaS insurance core platform with low-code tools that enable configurable digital experiences, supporting P&C carriers in achieving flexibility and speed to market.
On the innovation frontier, Shift Technology specializes in AI-driven solutions for fraud detection, claims automation, and decisioning agents. Their tools are used by major insurers globally to enhance accuracy and efficiency in critical operational workflows. Meanwhile, digital-first insurers like Lemonade are redefining customer expectations by using AI and chatbots for renters, homeowners, car, and pet insurance with fully online application and claims processes. These companies demonstrate how technology can be embedded into the core value proposition rather than merely supporting backend operations.
Additional players such as BriteCore and Next Insurance further diversify the landscape. BriteCore provides a cloud-native core platform for P&C insurers featuring AI-embedded tools, while Next Insurance focuses on digital platforms for small business insurance with instant quotes and online purchasing tools. The presence of these varied competitors highlights the multi-front nature of the digital insurance battle, where core system modernization, customer experience innovation, and niche market disruption occur simultaneously.
Recent Developments and Industry Momentum
Recent news cycles highlight the rapid pace of innovation and operational updates within the sector. In early 2026, Aetna launched a simplified, digital-first benefits onboarding experience for members, utilizing RCS-enabled text messaging and self-service tools. This move exemplifies the push toward frictionless member engagement and the adoption of modern communication channels in health benefits administration.
Simultaneously, Shift Technology advanced its agentic AI models in Shift Claims, enhancing capabilities for policy data interpretation, claims assessment, and anomaly detection. These innovations point toward a future where intelligent agents handle increasingly complex decision-making tasks, reducing manual intervention and improving outcomes. Additionally, Duck Creek Technologies saw recognition for core system modernization efforts, with Suncorp leveraging the Duck Creek platform to drive transformation. Such developments signal that core system upgrades remain a top priority for established insurers seeking to compete in a digital-first environment.
These events are not isolated; they are part of a broader pattern of accelerating digital maturity. Our report contextualizes these developments within the wider market trajectory, helping leaders understand which innovations are likely to become industry standards and which represent niche experiments.
Market Dynamics: Regulation, Compliance, and Operational Costs
The digital insurance landscape is heavily influenced by regulatory and operational factors that can dictate strategy and cost structures. In California, CPPA regulations on cybersecurity audits, risk assessments, and automated decision-making technology for insurance companies took effect on January 1, 2026. These rules impose new obligations on insurers deploying digital tools, particularly those involving algorithmic decision-making. Complying with these standards requires robust governance frameworks and transparent data practices.
At the federal and state level in the U.S., additional privacy laws effective January 1, 2026, introduce obligations for opt-out mechanisms and data protection assessments. These measures impact digital insurers that rely on extensive data collection for personalization and risk modeling, necessitating careful attention to user consent and data handling protocols.
Internationally, the EU Digital Operational Resilience Act (DORA) has been fully in effect since January 2025, mandating ICT risk management and third-party oversight for insurance entities. This regulation forces insurers to scrutinize their technology vendors and cloud dependencies, adding a layer of complexity to digital transformation initiatives. Organizations must ensure that their digital ecosystems are resilient against cyber threats and operational disruptions.
Digital Insurance Market
Operational costs also vary significantly based on compliance and infrastructure requirements. Managed HIPAA-compliant cloud hosting for digital health and insurance-related data ranges from 300 to 1,200+ USD per month depending on scale and features. This variable cost structure underscores the importance of right-sizing technology investments and understanding the total cost of ownership for digital insurance platforms.
Our report provides a detailed analysis of these dynamics, helping organizations anticipate regulatory shifts, manage compliance risks, and optimize operational expenditures. The full assessment of regulatory impacts and cost structures is elaborated upon in the complete market study.
Strategic Value for 2026 Decision-Making
For enterprises operating in or adjacent to the insurance sector, the insights contained in this report offer tangible strategic value. The concentration of the market, with CR3 at 18.5 percent and CR5 at 24.2 percent, indicates a landscape that is still relatively fragmented, leaving room for both consolidation and disruptive entry. Understanding where market power lies and how it is shifting is critical for partnership, acquisition, and competitive strategies.
Decision-makers can leverage this research to:
- Align technology roadmaps with emerging adoption trends in cloud, AI, and IoT.
- Evaluate competitive positioning relative to key platform providers and digital-native insurers.
- Anticipate regulatory changes and integrate compliance into product design from the outset.
- Assess market entry opportunities based on segmentation dynamics and regional growth potential.
- Optimize investment decisions by understanding the cost implications of digital infrastructure and data management.
The report is structured to move beyond high-level observations, offering operational insights that can be directly applied to strategic planning processes. From technology selection criteria to risk mitigation frameworks, the analysis covers the spectrum of considerations that leaders face in 2026.
Conclusion: Access the Complete Intelligence
The digital insurance market is at a pivotal juncture where technology, regulation, and customer expectations converge to reshape the industry. The growth trajectory, competitive movements, and regulatory developments outlined above provide a snapshot of the forces at play. However, the full depth of this transformation requires a more granular examination of segmentation data, regional nuances, and detailed company profiles.
PW Consulting's Digital Insurance Market report delivers the comprehensive intelligence needed to make informed, forward-looking decisions. By synthesizing market size forecasts, segmentation analysis, competitive profiling, and dynamic industry factors, this research equips stakeholders with the tools to navigate uncertainty and capitalize on emerging opportunities.
To access the complete dataset, detailed regional breakdowns, and actionable strategic recommendations, we invite you to explore the full report. The complete market intelligence is designed to support your organization's specific goals, whether you are optimizing core operations, launching new digital products, or evaluating investment opportunities in the insurance technology space.
For detailed analysis of this topic, please visit the official page: Digital Insurance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Steam Reformers Market to Hit $1.17 Billion by 2032, 6.12% CAGR
By pmarketresearch, 2026-09-17
Global Steam Reformers Market 2026: Strategic Intelligence for Capital Allocation and Competitive Positioning
The worldwide steam reformers market stands at a critical inflection point as the energy and chemicals industries navigate the dual imperatives of operational efficiency and decarbonization. Steam methane reforming remains the dominant technological pathway for large-scale hydrogen and syngas production, anchoring capital-intensive projects across oil refining, ammonia synthesis, methanol manufacturing, and merchant hydrogen distribution. For executives planning capacity expansions, technology selections, or feedstock procurement strategies in 2026 and beyond, fragmented data and anecdotal market signals are no longer sufficient. PW Consulting's newly released Worldwide Steam Reformers Market study delivers a rigorous, decision-ready intelligence framework that translates historical performance into actionable forward-looking strategy.
This article serves as a strategic preview of the full report. It outlines the structural forces shaping the market, highlights the operational and competitive dimensions covered in depth, and explains why the complete intelligence package is essential for capital allocation, vendor evaluation, and risk management in the coming years.
Market Trajectory and Macro Landscape: Why 2026 Is a Pivotal Year
The steam reformers market has demonstrated steady expansion over the past half-decade, supported by sustained demand from downstream chemical and refining operations. Historical valuations from 2020 through 2025 reflect a market that has consistently scaled as industrial hydrogen consumption, syngas integration, and process optimization initiatives gained momentum. The trajectory continues into the forecast window, with the market projected to reach approximately 790 million USD in 2026 and climb steadily toward the 1.1-billion USD threshold by the early 2030s. Over the full forecast horizon, the compound annual growth rate is estimated at 6.12 percent, indicating a durable upward trend rather than a temporary surge.
This growth profile carries direct implications for 2026 decision-making. First, it signals that demand for reforming capacity is not cyclical in the short term; it is structurally reinforced by longLead industrial projects and the gradual integration of hydrogen-bearing value chains. Second, it underscores the importance of timing. Firms that delay capacity evaluations or technology comparisons risk entering procurement cycles when vendor backlogs are already stretched and customization lead times extend. Third, the steady expansion suggests that pricing dynamics, feedstock cost structures, and equipment availability will increasingly influence project economics, making macro awareness a prerequisite for sound internal rate-of-return modeling.
The complete report anchors these macro movements in a transparent historical series and forward projection, allowing readers to benchmark internal assumptions against independently modeled trajectories. Rather than presenting isolated snapshots, the analysis connects year-over-year patterns to the underlying drivers that will sustain volume growth well beyond the immediate forecast window.
Core Segmentation Dimensions and How They Shape Investment Decisions
Understanding where growth concentrates—and why—requires a disciplined breakdown of feedstock pathways, application end-uses, and geographic deployment profiles. The report deconstructs the market across these axes without isolating narrow percentage splits or nominal sub-values that would oversimplify regional and sectoral dynamics. Instead, it frames each dimension in terms of operational relevance, cost sensitivity, and strategic prioritization.
Feedstock selection remains the foundational variable for reformer design, operating economics, and emissions profiling. Natural gas continues to dominate as the primary input for steam methane reforming, reflecting its widespread availability, established infrastructure, and favorable stoichiometry for hydrogen yield. Naphtha and other hydrocarbon streams, including LPG, represent complementary pathways that gain relevance in regions where natural gas logistics are constrained or where integration with existing petrochemical complexes offers economic advantages. The report evaluates how these feedstock options interact with reformer configuration, catalyst requirements, and downstream purification needs, helping procurement teams align technology choices with local supply realities rather than generic benchmark assumptions.
Application end-uses further differentiate project priorities. Oil refineries continue to represent a major consumption base, driven by hydrogen demand for hydrotreating and hydrocracking operations. Ammonia production remains tightly linked to reforming capacity, given the scale of hydrogen requirements in conventional ammonia synthesis routes. Methanol production and merchant hydrogen output constitute additional demand pillars, each with distinct throughput sensitivities, purity specifications, and operating profiles. The study maps how these application segments influence reformer sizing, thermal design, and integration with ancillary systems such as pressure swing adsorption units, carbon management equipment, and heat recovery trains.
Geographic deployment patterns add another strategic layer. Asia Pacific, North America, Europe, the Middle East and Africa, and Latin America each present different combinations of feedstock cost structures, industrial demand intensity, regulatory expectations, and project development rhythms. The report assesses how these regional contexts shape vendor presence, engineering preferences, and implementation timelines. Decision-makers gain a structured basis for evaluating where to pursue near-term capacity additions, where to monitor emerging demand clusters, and where to anticipate longer development cycles that may affect equipment delivery and commissioning schedules.
Competitive Dynamics: Technology Portfolio Positioning and Strategic Implications
The steam reformers market is characterized by a mix of engineering groups, equipment specialists, catalyst providers, and component manufacturers. Rather than competing on a single performance metric, firms differentiate through design philosophy, thermal efficiency, materials durability, modularization capability, and integration with downstream or emissions-control systems. PW Consulting's analysis profiles the leading players and decodes how their capabilities translate into commercial leverage for buyers and investors.
European and German-headquartered engineering organizations occupy a prominent position in the competitive landscape. Linde Engineering has built a substantial global footprint through multiple reforming furnace deliveries and modular hydrogen plant configurations, offering both top-fired and side-fired approaches and a strong record in hydrogen and syngas projects from varied feedstocks. thyssenkrupp Uhde emphasizes proprietary reforming technology with cold outlet manifold systems, designing reformers that operate across elevated temperature and pressure ranges with a documented deployment history across dozens of plants. Bihl focuses on primary steam-methane reformer design and supply, alongside waste heat recovery sections and fired heaters, extending its relevance to auto-thermal reforming pathways. Mahler AGS develops hydroform-type SMR plants tailored for high-purity hydrogen production, combining top-fired reformer design with purification systems.
In parallel, firms such as Topsoe contribute radiant wall reformer designs backed by a large installed base and a broader offering that spans catalysts and process technology. Schmidt + Clemens specializes in reformer tubes and outlet manifolds, components that directly influence reliability under high-temperature service. MetalTek brings centrifugal casting expertise for reformer tubes engineered to withstand prolonged exposure to creep and stress conditions in demanding petrochemical environments. Clariant complements the equipment ecosystem with nickel-based reforming catalysts designed for tubular primary reformers producing syngas for hydrogen, ammonia, and methanol applications.
Air Liquide Engineering & Construction and Technip Energies further illustrate the breadth of competitive approaches. Air Liquide focuses on steam methane reforming technology across small and large scales, with attention to integration pathways that align reforming operations with carbon capture concepts. Technip Energies supplies high-efficiency top-fired steam reformers for hydrogen production plants, including low-NOx burner integration that reflects growing attention to emissions performance.
This competitive mosaic matters for 2026 strategy because vendor selection increasingly determines not only capital cost but also long-term operability, maintenance burden, and flexibility to adapt to changing feedstock or regulatory conditions. The report does not simply list vendor attributes; it translates them into procurement considerations. Readers gain insight into where design differentiation carries the most weight, how modularization affects project phasing, and what technical trade-offs should be evaluated when comparing reformer tube materials, furnace firing configurations, and catalyst compatibility.
Recent industry activity reinforces the need for up-to-date competitive tracking. In late 2025, Sypox advanced the development of a large-scale electric steam methane reformer concept, using renewable electricity to produce syngas at a substantial daily rate in partnership with a catalyst supplier. While such projects remain indicative of emerging electrification and hybrid pathway exploration rather than immediate market displacement, they signal that technology roadmaps are expanding and that future procurement comparisons will need to account for alternative energy input models, catalyst integration, and process intensification options. The full report situates these developments within the broader competitive landscape so that decision-makers can distinguish near-term commercial reality from longer-term optionality.
Operational Context and External Pressure Points
Market performance does not occur in a vacuum. Feedstock pricing, production availability, and equipment supply constraints all interact to shape project feasibility and timing. The report integrates external context that directly influences reformer economics, including the evolving cost environment for natural gas as a primary feedstock and the trajectory of domestic production that supports feedstock supply continuity. Rising feedstock cost expectations can alter sensitivity analyses, shift the relative attractiveness of alternative hydrocarbon inputs, and affect the payback logic for efficiency upgrades or carbon management add-ons. At the same time, stronger production outlooks may ease some supply concerns while intensifying competition for engineering and fabrication resources.
These dynamics underscore why a static market snapshot is insufficient. Executive teams need a framework that connects external cost signals to internal project assumptions, evaluates how feedstock price movement alters the expected value of different reformer designs, and anticipates where backlogs or component lead times could influence implementation schedules. The study is structured to support that kind of integrated assessment.
What the Full Study Delivers: Analytical Depth and Practical Utility
Beyond the macro outlook and competitive profiling, the Worldwide Steam Reformers Market report is built around decision tools that can be applied directly to capital planning, procurement strategy, and investor communication. The study combines quantitative trajectory modeling with qualitative assessment of technology, applications, feedstocks, and regional deployment patterns to create a cohesive working reference for project evaluation.
Key elements of the report include:
- A transparent historical and forecast series that grounds internal projections in a consistent analytical baseline, enabling readers to test their own growth assumptions against modeled trends.
- Segment-level analysis across feedstock pathways and application end-uses that explains operational implications rather than merely reporting numeric splits, helping teams match reformer configurations to site-specific requirements.
- Geographic assessment that contextualizes regional demand, feedstock logistics, and project development environments so that expansion plans reflect local realities rather than global averages.
- Competitive profiling that maps vendor capabilities, design philosophies, and integration strengths to procurement considerations, supporting more disciplined vendor shortlisting and request-for-proposal preparation.
- Contextual integration of feedstock cost and supply signals, with commentary on how these factors influence project economics, sensitivity ranges, and timing choices.
- Operational and strategic synthesis that connects market momentum to practical implications for capacity planning, technology selection, and risk management in the 2026 to 2032 window.
The emphasis throughout is on usable intelligence. The report is designed for teams that need to justify capital commitments, compare engineering options, assess feedstock exposure, and communicate market logic to internal stakeholders or external partners. By combining market sizing with structural analysis and competitive decoding, it supports both strategic positioning and operational execution.
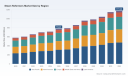
Worldwide Steam Reformers Market
Worldwide Reformer Unit Market
Strategic Read-Through for 2026 Decision Makers
For organizations evaluating hydrogen-related capacity, syngas integration, or reformer technology selection in 2026, the strategic message is clear: the market is expanding on a durable basis, but execution advantage will be determined by how well decision-makers interpret the underlying segmentation, competitive differentiation, and external cost dynamics. The firms that succeed will be those that treat steam reforming not as a commodity equipment purchase but as a long-duration process choice with implications for efficiency, emissions management, uptime, and future flexibility.
PW Consulting's study is designed to support that level of judgment. It provides the analytical grounding needed to separate genuine growth opportunities from noise, align technology and feedstock choices with regional and application realities, and anticipate how competitive and supply-side conditions may influence project outcomes over the forecast period. The complete report contains the detailed segmentation analysis, company evaluations, and forward modeling that turn high-level market awareness into concrete action.
Accessing the Full Intelligence Package
This preview has outlined the strategic rationale behind the Worldwide Steam Reformers Market study and the analytical dimensions it covers. To move from directional understanding to execution-ready intelligence, decision-makers should consult the full report, where detailed market sizing, segmentation breakdowns, competitive analysis, and forecast trajectories are presented in a structured format for direct application to capital planning and procurement strategy. The complete study is available through the source page, where the full dataset, methodology context, and applied insights can be reviewed in depth.
For detailed analysis of this topic, please visit the official page: Worldwide Steam Reformers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Audio Cabinets Market Revenue Hits $1.82B in 2025, Projected 5.85% CAGR Through 2032
By pmarketresearch, 2026-09-17
Strategic Intelligence for the 2026 Audio Cabinets Market: Navigating Growth, Consolidation, and Material Volatility
The global audio equipment ecosystem is undergoing a structural transformation, and audio cabinets remain at the physical and acoustic core of that evolution. As design philosophies shift toward integrated furniture-grade acoustics, professional touring demands intensify, and regional manufacturing footprints realign, enterprise leaders require more than headline revenue projections. They need a disciplined, decision-grade framework that connects material economics, competitive positioning, application-level demand vectors, and regional growth trajectories into a coherent roadmap for 2026 and beyond. Our newly released Audio Cabinets Market research report delivers exactly that: a comprehensive, data-backed intelligence asset engineered to de-risk capital allocation, product strategy, and supply chain planning.
The market has demonstrated resilient expansion across the 2020–2025 historical window, moving from approximately $1,420.45 million to $1,824.50 million. That trajectory reflects more than cyclical recovery; it signals durable demand across consumer, professional, and specialized automotive audio verticals. Looking ahead, the forecast period from 2026 through 2032 maps sustained momentum, with the market projected to reach $1,926.79 million in 2026 and expand to $2,718.95 million by 2032, underpinned by a compound annual growth rate of 5.85%. These figures are not abstract milestones. They represent the growth envelope within which manufacturing capacity, distribution partnerships, and product architectures will be evaluated, contested, and scaled over the next seven years.
For executives, procurement leaders, and strategy teams, the strategic question is no longer whether the market is expanding, but how value will be captured in an environment defined by material cost asymmetry, regional manufacturing realignments, and a moderately concentrated competitive field. This research is purpose-built to convert macro momentum into actionable strategic clarity.
The Strategic Imperative for 2026 Decision-Making
Entering 2026, the audio cabinets sector operates at the intersection of acoustic engineering, material science, and consumer-facing design expectations. The convergence of these forces creates both opportunity and friction. Organizations that rely on legacy cost structures or static product roadmaps will face margin compression, competitive displacement, or both. Conversely, firms that align product development cycles with regional demand patterns, material availability, and application-specific performance requirements will be better positioned to defend share while capturing incremental growth.
The report is structured to surface those alignment opportunities. Rather than treating the market as a single homogeneous category, it decomposes growth drivers by technology architecture, end-use application, and geographic demand centers, enabling decision-makers to identify where strategic focus yields the highest return on investment. The analysis is calibrated for leaders who need to evaluate manufacturing footprint decisions, assess entry or exit viability in specific applications, benchmark competitive positioning, and anticipate how raw material cost differentials will cascade through unit economics over the forecast horizon.
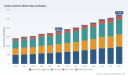
Audio Cabinets Market
Decoding the Research Architecture: What the Report Delivers
The Audio Cabinets Market study is organized as a practical intelligence toolkit rather than an academic survey. Its architecture is designed to support sequential decision-making, from high-level market sizing to granular competitive and operational insights. Key components include:
- Comprehensive historical reconstruction from 2020 through 2025, establishing baseline demand behavior, growth inflection points, and structural shifts that inform forward-looking forecasts.
- An extended forecast model spanning 2026 to 2032, providing a structured view of anticipated revenue expansion, CAGR dynamics, and the progression of market value across the prediction window.
- Segment-level analytical frameworks across product types, application verticals, and regional markets, enabling targeted scenario planning without exposing organizations to one-size-fits-all assumptions.
- Competitive landscape mapping that profiles leading manufacturers, evaluates positioning strategies, and contextualizes market concentration dynamics within the broader industry structure.
- Technology and material considerations, including how enclosure construction choices influence acoustic performance, cost profiles, and sourcing strategy.
- Recent market developments and product launches that signal emerging design directions, partnership models, and category expansion patterns relevant to 2026 planning.
Each section is developed to support operational decision-making. Product managers can use the application and type perspectives to prioritize enclosure designs and driver-integration strategies. Supply chain and procurement leaders can contextualize material selection within cost-performance trade-offs. Executive teams can leverage regional demand insights to anticipate where distribution scale, localization, or partnership structures will matter most. The report is intentionally designed to be referenced across functions, not siloed within a single business unit.
Competitive Landscape: Concentration, Positioning, and Strategic White Space
The competitive structure of the audio cabinets market reflects a moderately consolidated environment, with the top three players collectively representing approximately 38.5% of market share and the top five reaching roughly 52.7%. This concentration pattern suggests that established manufacturers hold meaningful positioning advantages in branding, distribution, and product credibility, while still leaving substantial room for specialized, regional, and application-focused competitors to compete on customization, acoustic tuning, and material execution.
Our competitive profiling examines players across multiple strategic archetypes. In the professional and touring audio segment, organizations such as JBL Professional and Martin Audio anchor demand for high-performance loudspeaker cabinets and enclosures built for live sound and installed systems. In the guitarist and bassist amplifier enclosure space, U.S.-based Avatar Speakers has sustained a factory-direct model centered on premium driver integration since the early 1990s, while U.K.-based Zilla Cabs competes on bespoke, handmade construction aimed at professional musicians seeking tailored tonal and structural characteristics.
On the high-fidelity and furniture-integrated side, the landscape includes premium acoustic furniture specialists and ecosystem-driven hi-fi brands. Spectral Audio Möbel emphasizes acoustic performance and design-led hi-fi cabinet construction for premium systems. Naim Audio integrates speaker enclosures and cabinets within a broader high-fidelity ecosystem, reinforcing system-level coherence rather than standalone component positioning. Quadraspire focuses on performance-oriented audio racks and cabinets engineered to reduce resonance and enhance clarity through material selection and structural design. These players illustrate how cabinet value is increasingly framed not only as acoustic containment, but as part of an integrated listening experience, interior design aesthetic, and system architecture.
The manufacturing dimension adds another strategic layer. Woodsat Audio Technology, operating as an OEM supplier of custom wooden enclosures since 2005, reflects the continued importance of contract manufacturing and white-label capability in serving global audio brands. This OEM dynamic matters because it shapes how quickly brands can scale enclosure programs, manage cost structures, and adapt to design changes without expanding their own fabrication capacity.
Recent 2026 developments reinforce the trend toward integration, customization, and category blending. In March 2026, ADI advanced its portfolio with the launch of more than 120 new Triad amplification, home cinema speaker, and subwoofer solutions, including customizable sound options that underscore demand for configurable audio environments. In April 2026, La-Z-Boy introduced the AudioLuxe premium audio furniture line at High Point Market, integrating Klipsch sound systems into customizable cabinets. These launches are strategically significant because they signal two parallel movements: the expansion of configurable professional and home-cinema audio offerings, and the migration of high-performance audio into furniture-grade, design-conscious enclosures. Both movements influence how cabinet manufacturers and audio brands think about enclosure form factor, finish, acoustic tuning, and channel strategy.
Server Cabinet Market
Material Economics and the Cost-Performance Equation
A critical, often under-modeled dimension of cabinet strategy is raw material economics. Enclosure construction directly affects acoustic behavior, durability, manufacturing complexity, and ultimately unit cost. As of the second quarter of 2025, Baltic birch plywood in 12mm 4x8 sheet format was priced in the range of $89 to $112 across North America and Europe, while standard MDF in 18mm 4x8 sheet format ranged between $42 and $58 in the same markets. That spread is not merely a procurement detail. It is a strategic variable that influences product tiering, margin architecture, and supplier negotiation leverage.
Industry data from early 2026 reinforces why MDF remains the preferred baseline for many speaker cabinet applications. Its consistent density and acoustic damping properties make it attractive for controlled enclosure performance, while its lower material cost, typically 30% to 40% below birch plywood, supports more favorable cost structures at scale. At the same time, premium and design-forward applications continue to justify higher-cost substrate choices when tonal character, furniture-grade aesthetics, or structural rigidity are differentiated value propositions. The strategic implication is clear: material selection is increasingly a portfolio decision rather than a single-specification rule. Companies that map substrate economics to application requirements, target price points, and regional sourcing conditions will have more flexibility to protect margins while meeting performance expectations.
Why This Research Matters for 2026 Planning Cycles
The 2026 planning cycle demands intelligence that can be used, not just read. Market momentum is evident, but momentum alone does not define where to invest, which applications to prioritize, or how to position against concentrated incumbents and agile specialists simultaneously. This report is built to convert growth signals into strategic action by connecting market sizing, segmentation logic, competitive behavior, and material cost dynamics into one coherent analytical environment.
By grounding the narrative in verified historical performance and extending it through a structured 2026–2032 forecast, the research gives leaders a defensible basis for scenario planning. The market’s projected progression from $1,926.79 million in 2026 to $2,718.95 million in 2032 provides a macro frame, while the segmentation, competitive, and material insights provide the executional detail necessary to interpret that frame in operational terms. This is the difference between knowing the market is growing and knowing where the growth is structurally coming from, which players are shaping it, and which cost and design variables will determine whether a company captures value or merely competes in it.
Positioning for informed strategic action
The audio cabinets market is not simply expanding; it is recalibrating around integration, customization, material economics, and application-specific performance demands. In that environment, the organizations that thrive will be those that pair growth awareness with disciplined strategic segmentation, competitive intelligence, and cost-aware design strategy. This research is designed to provide that foundation, giving executives and operational leaders a credible, detailed, and decision-ready view of the market landscape as they plan for 2026 and the years ahead.
To access the full segmentation detail, regional demand analysis, complete competitive profiles, and extended forecasts underpinning this overview, we invite you to explore the complete report on our website. The summary presented here is intended to establish the strategic context and analytical rigor of the study; the full intelligence package provides the comprehensive data architecture required for precise planning, investment evaluation, and competitive positioning across the 2026–2032 forecast period.
For detailed analysis of this topic, please visit the official page: Audio Cabinets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: DevSecOps Tool Market Hits $10.1B in 2025, surging 27.14% CAGR Through 2032
By pmarketresearch, 2026-09-17
The DevSecOps Tool Market in 2026: Strategic Intelligence for Enterprise Decision-Makers
The Imperative of Embedded Security
The software delivery landscape has fundamentally shifted. Security is no longer a final checkpoint before deployment; it is an intrinsic property woven into every stage of the development lifecycle. As organizations accelerate their digital transformation agendas, the DevSecOps tool market has emerged as a critical infrastructure layer that determines both velocity and resilience. Our latest market research provides a rigorous examination of this rapidly evolving sector, offering enterprise leaders the clarity required to make informed technology procurement, partnership, and investment decisions throughout 2026 and beyond.
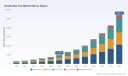
DevSecOps Tool Market
This report is not merely a retrospective analysis of market growth. It is a forward-looking strategic instrument designed to help CISOs, VP of Engineering, procurement leaders, and board-level executives navigate a vendor ecosystem that is consolidating, differentiating through AI capabilities, and responding to an intensifying regulatory environment. The insights contained within are structured to translate raw market dynamics into actionable decision frameworks.
Understanding the Scale and Trajectory of the Market
The DevSecOps tool sector has experienced an extraordinary growth arc over the past half-decade. Between 2020 and 2025, the overall market expanded from a modest base to surpass the one billion dollar threshold, reflecting the compounding impact of cloud migration, regulatory pressure, and the mainstreaming of security-left practices. The momentum does not decelerate. Forecasts extending through 2032 indicate a sustained compound annual growth rate that underscores the structural rather than cyclical nature of this expansion.
For enterprise planners, this trajectory signals more than just vendor opportunity. It indicates that DevSecOps is transitioning from a competitive differentiator to a baseline operational requirement. Organizations that delay foundational investments risk falling behind peers who are already embedding automated scanning, policy enforcement, and continuous compliance into their delivery pipelines. Conversely, enterprises that approach tool selection with strategic discipline can achieve meaningful reductions in technical debt, operational friction, and exposure windows.
Our research models multiple forward scenarios to account for variables such as procurement cycle shifts, platform consolidation trends, and the emergence of AI-assisted security workflows. Rather than presenting a single deterministic forecast, the report equips leaders with a range of plausible outcomes, enabling scenario-based budgeting and vendor negotiation strategies that remain robust under uncertainty.
What the Research Delivers: Operational Content and Decision Frameworks
Deep market intelligence achieves its value only when it is directly applicable to operational decision-making. This study is structured to bridge the gap between high-level market awareness and the granular evaluations that procurement and engineering teams must perform. The following components define the analytical core of the report:
- Comprehensive platform capability mapping that evaluates how leading solutions address static analysis, software composition analysis, dynamic testing, infrastructure-as-code validation, container security, and correlated risk visibility across the full software development lifecycle.
- Deployment architecture analysis contrasting cloud-native delivery models with on-premise and hybrid patterns, including considerations around data residency, integration complexity, and total cost of ownership over multi-year horizons.
- Industry vertical applicability assessments that identify which solution categories align best with the regulatory and operational profiles of sectors such as financial services, healthcare, government and defense, telecommunications, and retail.
- Vendor consolidation and platformization evaluation, helping enterprises determine when to pursue integrated suites versus specialized point tools, based on organizational maturity, existing technology debt, and internal skill distribution.
- Procurement and negotiation intelligence that translates market positioning trends into practical guidance for license structuring, multi-year commitments, and service-level expectations.
- Operational efficiency benchmarking that quantifies the impact of automation maturity on developer workflows, including the hidden labor costs associated with manual approvals and redundant scanning processes.
These components are designed to be referenced during tool evaluation, architecture planning, and budgeting cycles. Each section is grounded in observable market signals, vendor behavior, and procurement patterns, allowing leaders to use the report not as a one-time read but as an ongoing reference during strategic planning.
Competitive Landscape: Platform Strategy, Differentiation, and Consolidation Signals
The vendor ecosystem in the DevSecOps space is characterized by a mix of established platform players, specialized security innovators, and large enterprise software vendors extending into developer-centric security workflows. With a moderately concentrated market structure, competitive dynamics are shaped by portfolio breadth, integration depth, and the ability to reduce tool sprawl for enterprise customers.
Several platform leaders define the current strategic conversation. Checkmarx continues to advance its unified DevSecOps platform approach, emphasizing correlated risk views and broad integration points across CI/CD and development environments. Snyk has positioned itself around a developer-first philosophy, extending its software composition and container scanning capabilities into secure AI software development through its AI Trust Platform. GitLab remains a powerful all-in-one delivery and security model for organizations seeking tightly integrated pipelines with built-in testing and compliance functionality.
On the cloud-native side, Aqua Security has built a strong reputation in container, Kubernetes, and serverless protection, while increasingly expanding into supply chain security for delivery pipelines. Palo Alto Networks, through its Prisma Cloud offering, provides a code-to-cloud perspective with compliance automation and broad multi-cloud visibility, appealing to organizations seeking centralized governance. Veracode maintains a strong enterprise footprint in application security testing, integrating static, composition, and dynamic capabilities into large-scale DevSecOps workflows. OpenText focuses on connecting tools, data, and teams across the full delivery lifecycle, emphasizing integration and lifecycle orchestration. Wiz has gained traction with a cloud-native platform that supports infrastructure-as-code scanning and runtime protection, reinforcing the code-to-cloud movement.
Recent activity illustrates how quickly strategic positioning evolves. Snyk expanded its AI security capabilities through acquisition, reinforcing its focus on secure AI software development. Aqua Security introduced new protections targeting AI workloads, reflecting the broader industry effort to secure next-generation application patterns. Partnerships are also reshaping workflow dynamics, with cloud platform providers and DevSecOps vendors collaborating to accelerate developer productivity and security integration. Together, these developments highlight a market where differentiation is increasingly tied to AI readiness, pipeline integration, and lifecycle coverage.
Market Dynamics: Regulation, Workflow Friction, and Architectural Pressure
DevSecOps adoption does not occur in a vacuum. Regulatory intervention, government guidance, and internal operational constraints are actively reshaping procurement priorities and architectural expectations.
In the public sector and regulated industries, guidance from national standards bodies and defense organizations has become more explicit about the expectations for secure software development and continuous operations. Recent publications have emphasized risk-based approaches aligned with established secure software development frameworks, reinforcing the need for traceable controls and repeatable security practices. Updates to defense enterprise guidance have further highlighted platform capability expectations and compliance program alignment, signaling that procurement in sensitive sectors will increasingly favor solutions with demonstrated governance integration. At the same time, cybersecurity risk management constructs are shifting toward continuous monitoring models that fit naturally into DevSecOps pipelines, requiring tools that can support ongoing compliance evidence rather than point-in-time assessments.
On the operational side, workflow efficiency is emerging as a decisive adoption factor. Engineers and security professionals are reporting significant time losses to manual approvals, duplicate scanning, and poor tool coordination. These inefficiencies do not merely slow delivery; they erode the business case for security tooling by increasing friction without reducing risk. Organizations that select platforms solely on feature checklists, without considering workflow integration and developer experience, often find themselves paying for capability they cannot operationalize effectively. Our research addresses this reality by incorporating assessment criteria that reflect integration smoothness, automation depth, and the practical burden placed on delivery teams.
Worldwide Database Testing Tool Market
Strategic Recommendations for 2026 Enterprise Planning
Enterprise decision-makers evaluating DevSecOps investments in 2026 should approach the market with a structured lens that balances security outcomes, delivery efficiency, and long-term platform viability. The following strategic priorities emerge from the research:
- Treat DevSecOps procurement as a platform architecture decision, not a point-tool purchase. Evaluate how well candidate solutions reduce fragmentation across scanning, dependency management, infrastructure validation, and runtime protection.
- Factor AI readiness into vendor selection. The integration of AI-assisted security workflows, secure development support, and workload protection for AI-enabled applications is rapidly becoming a differentiating capability rather than a niche enhancement.
- Align tool selection with regulatory exposure. Organizations operating in or serving heavily regulated sectors should prioritize solutions with clear compliance mapping, auditability, and continuous monitoring alignment, especially where guidance is moving toward lifecycle-based risk management.
- Quantify operational burden before committing. The hidden labor costs associated with inefficient approvals and duplicate processes can undermine the return on security investment. Platforms should be assessed for their ability to streamline developer workflows rather than add procedural overhead.
- Plan for multi-year integration evolution. The most effective DevSecOps environments are built through incremental orchestration, not a single procurement event. Budget and roadmap planning should account for integration effort, internal enablement, and the likely need to consolidate tools as platform capabilities mature.
- Use market concentration dynamics to inform negotiation strategy. A moderately consolidated vendor landscape creates both opportunities and risks. Enterprises should evaluate whether suite-based platforms or best-of-breed combinations better fit their maturity level, internal skill base, and tolerance for integration complexity.
Why This Research Matters Now
The DevSecOps tool market is entering a phase where strategic clarity determines execution advantage. Growth is strong, vendor positioning is shifting, and the regulatory and operational context is becoming more demanding. In this environment, organizations need more than a list of tools or a surface-level market summary. They need a disciplined, evidence-based view of where the market is heading, how leading vendors are differentiating, and what decision criteria will produce the best security and delivery outcomes over the next several years.
This research is designed to provide that view. It combines macroeconomic trajectory with operational depth, competitive analysis, and market dynamics that shape real procurement choices. For leaders preparing budgets, architecture roadmaps, and vendor evaluations during 2026, the report offers a structured foundation for decisions that are both defensible and forward looking.
Access the Full Intelligence
The overview presented here provides the strategic framing and analytical direction of the study, but the detailed segmentation logic, capability assessments, competitive benchmarks, and scenario-based planning guidance are contained in the full report. Enterprise buyers, investors, and technology leaders who need granular market structure, vendor-by-vendor evaluation, and decision-ready frameworks will find the complete intelligence essential for informed action.
To access the complete DevSecOps Tool Market research and use it directly in your 2026 planning, review the full publication at the source page.
For detailed analysis of this topic, please visit the official page: DevSecOps Tool Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Amisulbrom Market Hits $72.5M in 2025, Projected to Reach $96M by 2032
By pmarketresearch, 2026-09-17
Unlocking Strategic Value in the Amisulbrom Market: A 2026 Decision-Maker's Guide
The global agrochemical landscape is entering a pivotal phase where precision fungicides are no longer just tactical tools but strategic assets for crop protection portfolios. As we navigate through 2026, the Amisulbrom market stands out as a critical segment within the oomycete control category, offering unique growth dynamics and competitive complexities that demand sharp analytical focus. This industry insight serves as a preface to our comprehensive market research publication, designed to equip stakeholders with the foundational knowledge required to capitalize on emerging opportunities while mitigating regulatory and competitive risks.
Our latest analysis spans a robust historical review from 2020 through 2025, providing a clear baseline of market performance before projecting forward into the forecast period of 2026 to 2032. The data indicates a steady evolution in market valuation, reflecting the compound's entrenched position in key agricultural regions. Understanding the trajectory of this market is essential for formulation developers, supply chain strategists, and investment analysts who need to align their roadmaps with realistic growth expectations.
Market Trajectory and Growth Dynamics
The Amisulbrom market has demonstrated resilience and consistent expansion over the past half-decade. Based on our consolidated data, the global revenue for this segment reached approximately 72.5 USD Million in the base year of 2025. This figure represents a culmination of growth trends observed since 2020, where the market size was recorded at 59.12 USD Million. The progression from 2020 to 2025 highlights a market that has recovered from minor fluctuations, such as the slight contraction observed in 2023, to resume a positive growth path leading into 2024 and 2025.
Forecast Outlook: 2026 to 2032
Looking ahead, the forecast period presents a compelling case for continued investment. The market is projected to reach 74.91 USD Million in 2026, marking the beginning of a growth curve that is expected to accelerate towards the end of the decade. By 2028, the valuation is anticipated to cross the 84 USD Million threshold, with further gains pushing the market to approximately 96.37 USD Million by 2032. This upward trajectory is underpinned by a Compound Annual Growth Rate (CAGR) of 4.15 percent throughout the forecast period.
This growth rate suggests a mature yet expanding market, driven by the need for effective resistance management solutions and the registration of new use patterns in key crops. For enterprises planning capital allocation or product development cycles, this CAGR serves as a critical benchmark for evaluating the potential return on investment in Amisulbrom-related activities.
Bromine Market
Competitive Landscape and Key Players
The market structure is characterized by a high degree of concentration, which influences pricing power, supply security, and innovation velocity. Our analysis indicates that the top three companies hold a combined market share of 72.4 percent, while the top five players control 88.15 percent of the market. This concentration underscores the dominance of established agrochemical giants and the originator of the active ingredient, creating a barrier to entry that favors strategic partnerships or specialized niche positioning for new entrants.
Strategic Profiles of Market Leaders
Nissan Chemical Corporation, headquartered in Tokyo, Japan, remains the originator and primary manufacturer of the Amisulbrom active ingredient. As the holder of the proprietary sulfonamide fungicide technology (code NC-224), Nissan Chemical supplies the technical material that forms the backbone of the supply chain. Their product portfolio includes formulations such as LEIMAY®, specifically targeted at controlling downy mildew in potatoes and vegetables. Their position as the upstream source gives them significant influence over global availability and technical specifications.
In the formulation and distribution tier, Nufarm Limited, based in Melbourne, Australia, plays a crucial role. Nufarm markets formulated products containing Amisulbrom, including Amishield, which is utilized for clubroot control in brassicas and disease suppression in potatoes. Additionally, their Amicus Blue product, combining amisulbrom with copper, represents a strategic co-formulation approach available in select markets. This diversification allows Nufarm to address multiple disease pressures while leveraging the core active ingredient.
Amisulbrom Market
Corteva Agriscience, headquartered in Wilmington, Delaware, USA, has been particularly active in expanding the utility of Amisulbrom through co-formulations. Their product, Zorvec Entecta, combines 240 g/l amisulbrom with 48 g/l oxathiapiprolin. This solution is actively promoted for late blight control in potatoes and downy mildew in vines across Europe and other regions. Corteva's strategy focuses on enhancing efficacy and managing resistance through combination products, which resonates with modern integrated pest management requirements.
Syngenta AG, based in Basel, Switzerland, maintains a strong presence by marketing Leimay and Evagio Forte. The latter, a combination of amisulbrom and mandipropamid, was upgraded to a full entry for blight control in potatoes in mid-2024. Syngenta's distribution networks and registration capabilities in key markets ensure that their formulations remain accessible to growers seeking reliable oomycete control.
The market also sees significant activity from Indian agritech companies, reflecting the growing importance of the Asia Pacific region in both consumption and formulation. Dhanuka Agritech Limited, located in Gurugram, India, operates as a registered importer and formulator of Amisulbrom technical and products such as Kirari. Similarly, Bharat Certis Agriscience Ltd offers Hinode, an Amisulbrom 20% SC formulation targeting oomycetes. These players contribute to the localization of supply and adaptation of products to regional crop needs.
Regulatory Environment and Industry Dynamics
Navigating the regulatory landscape is as critical as understanding market size. Amisulbrom belongs to FRAC Group 21, classified as QiI fungicides (Quinone inside inhibitors at the Qi site of complex III). This classification carries specific implications for use patterns. Resistance management strategies recommend a maximum of three applications per crop for certain hosts, such as broccoli and cauliflower. Compliance with these guidelines is essential for maintaining the longevity of the active ingredient and ensuring continued market access.
Geographically, the regulatory status varies significantly, influencing where and how products can be deployed. In the United States, tolerances for residues have been established by the EPA for imported commodities, with specific limits for grapes and tomatoes. However, Amisulbrom is not registered for domestic use in the US, which shapes the market dynamics by limiting domestic formulation opportunities while supporting export-related trade flows. Conversely, the European Food Safety Authority (EFSA) maintains maximum residue levels for the EU, and products are registered in Europe, Japan, Korea, Taiwan, Vietnam, Australia, and New Zealand for specific crops including potatoes, grapes, and brassicas.
Recent regulatory and product developments highlight the evolving nature of the market. In February 2026, Corteva Agriscience received the first Extension of Authorisation for Minor Use (EAMU) for Zorvec Entecta, approving its use for downy mildew control in bulb onions, garlic, and shallots with a 28-day harvest interval. This expansion into allium crops represents a strategic broadening of the addressable market. Earlier in 2025, Corteva issued updated technical sheets and best-use advice, emphasizing resistance management for QiI fungicides, which signals a proactive approach to stewardship.
Furthermore, the introduction of Zorvec Entecta in India in early 2025 for downy mildew in vines and late blight in potatoes illustrates the ongoing international rollout of advanced formulations. These developments are not merely product launches but strategic moves that redefine the boundaries of effective crop protection and open new revenue streams in diverse agricultural economies.
Segmentation Insights and Application Focus
The market is segmented across multiple dimensions, including region, formulation, and application. While specific percentage breakdowns are detailed in the full report, it is vital to understand the structural weight of these segments. The formulation landscape is dominated by Suspension Concentrate (SC) types, which command the largest share of the market value. Water Dispersible Granules (WG) and other formulations follow, reflecting diverse preferences in application technology and handling requirements across different agricultural systems.
In terms of application, the crop focus is heavily weighted towards high-value horticultural and field crops. Grapes and potatoes represent the primary use cases, driven by the severe impact of downy mildew and late blight on yield and quality. Vegetables form another significant segment, encompassing a range of crops where oomycete diseases pose consistent threats. Ornamentals and other applications complete the spectrum, representing niche but steady demand areas. The distribution of these applications varies by region, correlating with local cropping patterns and regulatory approvals.
Regional dynamics also play a pivotal role. Europe and Asia Pacific are key regions in the global mix, reflecting advanced agricultural practices and significant production volumes of target crops. Latin America, North America, and the Middle East and Africa contribute to the global total, each with unique regulatory and market access characteristics. Understanding the relative importance of these regions is crucial for companies planning market entry or expansion strategies.
Operational Content and Strategic Utility
Our comprehensive report goes beyond high-level aggregates to provide operational depth that supports decision-making at every level of the organization. The study includes detailed profiles of the key companies mentioned above, offering insights into their product portfolios, strategic moves, and recent developments. This allows stakeholders to benchmark their position against competitors and identify potential collaboration or acquisition targets.
The research also delves into the supply chain dynamics, examining the flow of technical material from originators to formulators and distributors. This is particularly relevant for understanding cost structures, supply security, and potential bottlenecks. Additionally, the report addresses frequently asked questions regarding the nature of Amisulbrom, clarifying its status as an agrochemical fungicide for oomycete control and distinguishing it from pharmaceutical applications, which is essential for compliance and communication strategies.
For market entrants and investors, the segmentation analysis provides a granular view of where growth is concentrated. By isolating the performance of different formulations and applications, the report enables targeted investment in high-potential areas. The regulatory section offers a concise summary of the current status across major jurisdictions, helping legal and regulatory affairs teams anticipate changes and prepare accordingly.
Strategic Implications for 2026 Decision Makers
As we move through 2026, the Amisulbrom market offers a blend of stability and opportunity. The consistent growth projected through 2032 indicates a healthy demand environment, but the high market concentration and regulatory complexities require a sophisticated approach. Companies must balance the advantages of established supply chains with the need for innovation in formulation and use patterns.
The recent expansions into new crops and regions, such as the EAMU for alliums and the introduction of products in India, suggest that the market is still evolving. Stakeholders who can navigate the resistance management guidelines while leveraging co-formulation technologies will be well-positioned to capture value. Furthermore, the disparity in regulatory status between regions like the US and the EU/Australia/Asia presents specific challenges and opportunities for trade and product development.
To fully harness these insights, access to the complete dataset and detailed segmentation analysis is essential. The macro trends outlined here provide the strategic context, but the precise figures, regional splits, and competitive benchmarks contained in the full report are necessary for granular planning. We invite you to explore the comprehensive Amisulbrom Market research to gain the detailed intelligence required to drive your 2026 strategies forward.
For detailed analysis of this topic, please visit the official page: Amisulbrom Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Casing Spools Market to Hit $1.02B by 2032, Growing at 5.12% CAGR from 2026-2032
By pmarketresearch, 2026-09-17
Strategic Intelligence in a Decade of Transformation: Navigating the Worldwide Casing Spools Market (2026–2032)
The global casing spools market stands at a critical inflection point. Between 2020 and 2025, the sector demonstrated remarkable resilience, navigating commodity price fluctuations, supply chain realignments, and shifting exploration priorities to reach a baseline valuation of 720.5 million USD. Looking ahead to the 2026–2032 forecast window, the market is projected to expand at a compound annual growth rate of 5.12 percent, ultimately surpassing the 1 billion USD milestone by the decade's end. For executives, procurement leaders, and strategic planners operating in oilfield equipment, energy infrastructure, and surface wellhead systems, this trajectory represents far more than a top-line projection. It signals a structural realignment in how casing spool technologies are specified, manufactured, sourced, and integrated into broader well lifecycle strategies.
The Worldwide Casing Spools Market research study recently published by PW Consulting has been engineered to translate macroeconomic momentum into actionable decision intelligence. Rather than offering static snapshots, the analysis maps the interplay between drilling complexity, material innovation, regulatory pressure, and competitive consolidation. The following overview previews the strategic architecture of the report, illustrating how executives can leverage its findings to optimize capital allocation, mitigate supply chain exposure, and position product portfolios for high-growth operational environments.
Decoding the Macro Trajectory: What the Numbers Reveal for 2026 Decision-Makers
The five-year historical baseline (2020–2025) establishes a clear narrative of accelerating demand maturity. After navigating a period of operational consolidation and value engineering in the early part of the decade, the market rebounded with renewed investment velocity, closing 2025 at 720.5 million USD. The forecast period extends this momentum, projecting sequential growth through 2032, where the market is expected to reach 1,021.96 million USD. The 5.12 percent CAGR is not merely a statistical output; it reflects a compounding set of industry realities: expanding production scenarios in complex geological basins, the progressive retirement of legacy wellhead infrastructure, and the strategic shift toward integrated surface pressure control architectures that place casing spools at the center of well integrity management.
Crucially, the report contextualizes this growth within the operational realities facing OEMs, distributors, and end-users. Revenue expansion is not uniform across the value chain. Instead, it is being driven by targeted demand in high-pressure and high-temperature (HPHT) environments, deepwater and ultra-deepwater development corridors, and onshore basins where well completion cycles are intensifying. The report's macro framing allows executives to separate cyclical noise from structural adoption curves, enabling more precise scenario planning for procurement cycles, inventory positioning, and long-term capacity investments.
Product Architecture and Application Realities: A Deep Dive into Type and Use-Case Dynamics
Casing spool technology sits at the intersection of mechanical reliability, pressure containment, and operational standardization. The market's product landscape is anchored by three primary categories: standard casing spools, high-pressure and high-temperature (HPHT) casing spools, and multi-bowl wellhead systems. Standard configurations continue to serve the broadest installed base, particularly in mature onshore fields where cost efficiency, interchangeability, and API 6A compliance define procurement criteria. HPHT casing spools, by contrast, represent a high-value growth vector, driven by wells operating under extreme thermal and mechanical stress that demand enhanced sealing performance, corrosion-resistant metallurgy, and advanced dimensional tolerances. Multi-bowl wellhead systems address complex well architectures requiring multiple production or injection pathways, a configuration increasingly favored in phased field development and artificial lift integration.
From an application standpoint, the market is shaped by the divergent operational rhythms of onshore and offshore environments. Onshore operations continue to account for a substantial share of demand, reflecting ongoing drilling campaigns in conventional and unconventional reservoirs, as well as the retrofitting of existing wellheads to support extended production lifecycles. Offshore demand, while numerically smaller in aggregate volume, carries disproportionate strategic weight due to the technical complexity of subsea and deepwater systems, the elevated cost of failure, and the concentration of capital in large-scale offshore developments. The report's segmentation analysis dissects these demand drivers without reducing them to simplistic volume counts, instead mapping how pressure ratings, metallurgy specifications, hanger compatibility, and well lifecycle stages influence procurement behavior.
Regional Market Reconfiguration: Where Demand Is Concentrating and Why
Geographic demand for casing spools is undergoing a meaningful redistribution. North America remains a central hub of activity, supported by mature basin redevelopment, shale-related well completion activity, and a dense ecosystem of oilfield service providers and equipment manufacturers. The Middle East and Africa sector reflects sustained investment in reservoir optimization, enhanced oil recovery initiatives, and high-capacity wellhead installations tied to long-term production commitments. Asia Pacific demand is broadening beyond traditional exploration to include expanded downstream integration, regional content provisions, and growing participation in offshore supply chains. Latin America and Europe contribute more specialized demand profiles, often shaped by deepwater access, regulatory frameworks, and localized content mandates that influence sourcing strategies.
The report resists the temptation to present regional data as static partitions. Instead, it examines how trade policy, steel and aluminum safeguarding measures, logistics constraints, and regional content requirements are reshaping where and how casing spools are produced, certified, and deployed. For multinational operators and equipment suppliers, regional analysis becomes a tool for evaluating localization opportunities, assessing tariff exposure, and aligning manufacturing footprints with shifting procurement geographies.
Competitive Architecture: How the Market Leaders Are Redefining Value Creation
The competitive landscape is characterized by a tiered structure in which a small group of integrated service and equipment providers holds a substantial share of high-complexity demand, while a broader field of manufacturers competes on specification compliance, regional availability, and cost positioning. The market's consolidated nature, with the top three competitors accounting for approximately 38.5 percent of revenue and the top five capturing over half of total market value, underscores the importance of strategic differentiation in an otherwise specification-driven environment.
Leading players have moved beyond offering discrete casing spool components. Their strategic relevance now stems from integrated wellhead assemblies, bundled surface pressure control solutions, digital monitoring integration, and increasingly, regional manufacturing and service partnerships. SLB continues to strengthen its position through high-value contract awards that bundle low-pressure, high-pressure, and thermal wellhead systems with artificial lift technologies, signaling a market preference for integrated lifecycle solutions. Baker Hughes has been actively restructuring its wellhead and pressure-control equipment capabilities, including the formation of surface pressure control joint ventures and the inauguration of dedicated service and manufacturing centers designed to expand regional capacity and responsiveness. TechnipFMC's recent subsea production system contract activity highlights the strategic importance of advanced casing spool solutions in deepwater and offshore development campaigns, especially where well integrity and production reliability are paramount.
Mid-tier and regional manufacturers remain highly relevant, particularly where API 6A compliance, competitive unit pricing, hanger compatibility, and localized service support drive procurement decisions. Companies such as Weatherford International, NOV Inc., Worldwide Oilfield Machine, Sentry Wellhead Systems, Kingsa Industries, Parveen Industries, and a growing cohort of Chinese and Eastern European manufacturers including CCSC Petroleum Equipment, All-Petro, Yulin Machinery (Aqe Machinery), Qilu Steel Group, and UZTEL S.A. illustrate the breadth of manufacturing capabilities serving onshore, offshore, sour service, and developing-market applications. Their competitive positioning often hinges on forgings and castings quality, product range breadth, lead-time reliability, and the ability to meet specific pressure ratings, bore designs, and PSL requirements.
The report's competitive analysis does not stop at corporate profiling. It evaluates how product roadmaps, materials innovation, supply partnerships, joint venture structures, and recent contract awards are reshaping competitive advantage. By linking corporate strategy to market share dynamics, the study helps clients assess which competitors are expanding capability footprints, which are consolidating around core wellhead platforms, and which are creating new pathways for value capture through regionalization or specialized product lines.
Structural Dynamics: Materials, Regulations, Tariffs, and the New Cost Environment
No strategic assessment of the casing spools market is complete without confronting the operating environment that governs cost, compliance, and competitiveness. Casing spools are predominantly manufactured from forged steel or low-alloy steel to meet API Spec 6A requirements for materials, dimensions, test procedures, and pressure ratings. This specification baseline provides a common language for procurement, but it also means that raw material volatility and trade policy changes can transmit quickly through the supply chain. Recent policy environments have introduced significant uncertainty, including the elevation of steel and aluminum duties and their extension to derivative goods, with potential cost implications for wellhead equipment that analysts estimate could range from 4 percent to 40 percent depending on sourcing configuration and product complexity.
Worldwide Casing Collar Locator Market
Simultaneously, the market is being shaped by macro-trend acceleration. Rising investments in deepwater, ultra-deepwater, and HPHT drilling projects are increasing demand for advanced casing spools with enhanced sealing technologies and improved corrosion resistance. Policy shifts in key oil-producing regions have also reinforced local content requirements, prompting manufacturers to invest in regional production capabilities and service infrastructure to preserve eligibility for major procurement programs. These dynamics create a dual pressure: cost containment on one side, and capability escalation on the other. The report maps this tension explicitly, helping clients evaluate whether to pursue standardization and cost efficiency, differentiate through HPHT and corrosion-resistant offerings, or localize production to meet content requirements and reduce tariff exposure.
Worldwide Casing Spools Market
What the Report Delivers: Operational Intelligence for Executive Decision-Making
The Worldwide Casing Spools Market study is designed as a working intelligence asset, not a summary document. It integrates historical baselines, a detailed 2026–2032 forecast, segmentation analysis by region, type, and application, and a structured competitive landscape review anchored by recent contract awards, joint venture formations, and facility expansions. The report also overlays industry context on materials, regulatory compliance, tariff exposure, and macro demand drivers to provide a multi-layered view of market risk and opportunity.
Practically, this means executives can use the study to:
- Benchmark procurement forecasts against market-level demand trajectories and segmentation patterns
- Evaluate whether product portfolios are aligned to the fastest-growing specifications, including HPHT, multi-bowl configurations, and enhanced sealing designs
- Assess regional sourcing strategies in light of local content requirements, tariff exposure, and manufacturing footprint decisions
- Identify competitor moves that may affect pricing, lead times, bundled solution offerings, or after-sales service expectations
- Frame capital allocation for production capacity, inventory strategy, and service expansion in markets where wellhead equipment demand is intensifying
- Integrate digital monitoring and integrated wellhead architectures into product positioning where end-users increasingly prefer bundled, lifecycle-oriented solutions
The report's structure enables cross-functional use. Engineers and procurement teams can reference specification-relevant demand patterns and application assumptions. Commercial and strategy leaders can use competitive mapping and regional dynamics to refine market-entry, partnership, and pricing strategies. Senior executives can rely on the forecast architecture and concentration metrics to test strategic scenarios and align investment priorities with durable demand shifts rather than short-term cycle noise.
Looking Ahead: Turning Market Intelligence into Strategic Advantage
The casing spools market is not merely expanding; it is being redefined by technical complexity, regulatory constraints, regional content policy, and the strategic bundling of wellhead equipment into broader surface pressure control and production systems. In this environment, organizations that rely on historical assumptions or generic equipment forecasts risk misaligning their portfolios with where value is actually being created. The Worldwide Casing Spools Market research study offers a structured, data-anchored pathway to close that gap.
By combining a robust historical baseline, a detailed 2026–2032 forecast, segmentation analysis, competitive profiling, and real-world corporate developments, the report gives decision-makers the context needed to act with confidence in a market where margin, compliance, and reliability are increasingly inseparable from strategic success. For executives seeking to protect supply continuity, optimize product positioning, and capitalize on high-growth segments, the full study provides the depth, segmentation precision, and forward-looking intelligence required to convert market visibility into measurable advantage.
The complete analysis, including detailed segmentation breakdowns, regional and application-level demand mapping, and extended competitive intelligence, is available through the full Worldwide Casing Spools Market report. Access the full study to translate these high-level insights into precise, decision-ready intelligence for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Casing Spools Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Vortex Cooler Market Hits $728.5M in 2025, Poised for 5.85% CAGR to 2032
By pmarketresearch, 2026-09-17
Strategic Intelligence for the Vortex Cooler Market: Navigating Growth Trajectories Through 2032
Industrial cooling technologies have evolved from auxiliary utilities to mission-critical components in modern manufacturing ecosystems. As compressed air infrastructure becomes increasingly optimized and environmental regulations tighten around refrigerant-based systems, the vortex cooler market stands at a strategic inflection point. This article serves as a foundational preview of our comprehensive market research, designed to equip executive decision-makers with the macro-level intelligence required to allocate capital, position product portfolios, and anticipate competitive shifts across the 2026 to 2032 forecast horizon.
Worldwide Immersion Coolers Market
The trajectory of this sector is not merely a function of incremental demand growth. It reflects deeper industrial transformations: the push toward maintenance-free thermal management, the phasing out of synthetic refrigerants in sensitive electrical enclosures, and the geographic redistribution of manufacturing capacity. Our latest publication decodes these structural forces into actionable intelligence, bridging historical performance with forward-looking scenario modeling. The following analysis outlines the strategic architecture of the report, highlights the competitive dynamics shaping market share, and demonstrates why precise segmentation data remains indispensable for calibrated enterprise planning.
Market Architecture and Historical Trajectory
The vortex cooler market has demonstrated consistent expansion over the past half-decade, driven by sustained industrialization, automation scaling, and the operational advantages of compressed-air-based cooling systems. Our baseline analysis establishes a clear historical arc: from a foundational valuation of USD 512.45 million in 2020, the market advanced through successive growth cycles to reach USD 728.5 million by 2025. This progression underscores steady adoption across industrial environments where reliability, simplicity, and absence of moving parts translate directly into reduced downtime and lower maintenance overhead.
Looking forward, the forecast window from 2026 through 2032 projects a compound annual growth rate of 5.85 percent. This rate places the sector on a measured but unambiguous expansion path, culminating in a projected market valuation exceeding the one-billion-dollar threshold by the early 2030s. Such growth is not uniform; it is shaped by regional industrial density, material preference shifts, and application-specific thermal management requirements. Executives evaluating capacity expansion, supply chain localization, or product line diversification must understand how these structural variables interact. Our full report isolates these dynamics without obscuring them behind aggregated averages, ensuring that strategic plans are anchored in regionally and segmentally precise intelligence.
Vortex Cooler Market
Operational Scope of the Market Study
A market research publication is only as valuable as the decision-making clarity it delivers. Our vortex cooler study is structured to move beyond descriptive market sizing and into operational deployment. The report contains a modular assessment framework that covers the following core components:
- Historical baseline reconstruction spanning 2020 through 2025, with validated revenue trajectories and demand driver mapping
- Forward-looking scenario modeling across the 2026 to 2032 period, incorporating base, optimistic, and conservative growth pathways
- Material and engineering segmentation analysis, distinguishing adoption patterns across stainless steel configurations, polycarbonate alternatives, and other structural variants
- Application-level demand mapping that isolates industrial cooling, spot cooling, and electronics cooling as distinct thermal management use cases
- Regional market architecture covering North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with localized demand intensity and infrastructure dependency indicators
- Regulatory and compliance context analysis, including NEMA enclosure ratings, hazardous location certifications, and refrigerant-free operational mandates
- Supply-side operational parameters, including compressed air pressure thresholds, filtration standards, and durability requirements in corrosive industrial environments
This structure is intentionally designed for cross-functional consumption. Engineering leaders can reference application-specific thermal performance parameters, procurement teams can align material and supply specifications with operational environments, and commercial strategy units can map regional growth intensity against sales territory planning. The full dataset, complete with segmentation values, pricing proxies, and adoption elasticity indicators, is available through the complete report download.
Competitive Landscape and Strategic Positioning
The vortex cooler segment is characterized by a moderately concentrated competitive structure. Current market analysis indicates that the top three participants collectively command approximately 42.8 percent of total market revenue, while the top five firms extend that influence to roughly 58.6 percent. This concentration pattern signals a market where established engineering capability, application-specific certification portfolios, and regional distribution networks create meaningful barriers to entry. At the same time, it leaves substantial addressable space for specialized players, regional distributors, and engineering-focused entrants that can differentiate through material durability, CFM capacity ranges, or enclosure integration design.
Several core enterprises define the competitive baseline. EXAIR Corporation, headquartered in Cincinnati, Ohio, offers stainless steel vortex tubes and spot coolers engineered for industrial applications capable of producing cold air down to negative 50 degrees Fahrenheit without moving parts, supplemented by cabinet cooler systems. ITW Vortec, also based in Cincinnati, pioneered commercial vortex tube technology in 1961 and continues to supply vortex A/C enclosure coolers in NEMA-rated and hazardous location configurations with cooling capacities spanning 400 to 5000 BTU per hour. Nex Flow Air Products Corp., operating from Ontario, Canada, manufactures Frigid-X vortex tubes in stainless steel with welded construction, targeting spot cooling and enclosure cooling applications. Meech International, based in the United Kingdom, provides stainless steel vortex tubes and cabinet coolers for spot cooling, machine cooling, and enclosure temperature control. nVent HOFFMAN, operating from the United States, supplies vortex cooling systems for indoor and outdoor enclosures that rely on compressed air rather than refrigerants. Streamtek Corp., headquartered in Canada, offers vortex tubes in stainless steel or aluminum with multiple CFM capacities for diverse cooling applications. AiRTX, known as Air Research Technology in the United States, specializes in precision stainless steel vortex tubes designed for spot cooling deployments.
Competitive differentiation in this space rarely depends on price alone. It emerges from certification breadth, material durability in corrosive environments, compressed air efficiency, and the ability to integrate cooling modules directly into electrical enclosure architectures. Recent market activity reinforces this pattern. ITW Vortec returned to trade show and exhibition spaces in August 2024, showcasing compressed air cooling products including vortex A/C enclosure coolers, signaling renewed emphasis on live demonstration and direct technical engagement with industrial buyers. Meech International updated its vortex cooling range brochure in April 2025, detailing stainless steel vortex tubes and cabinet coolers with revised performance specifications, reflecting an ongoing focus on specification transparency and application matching. These moves illustrate a sector where technical credibility and product documentation quality directly influence procurement confidence.
Industry Dynamics and Structural Drivers
The operating environment for vortex coolers is shaped by a combination of regulatory frameworks, material engineering realities, and utility infrastructure dependencies. Understanding these dynamics is essential for evaluating both market growth and implementation risk.
Regulatory and Certification Context
Vortex coolers are positioned as refrigerant-free thermal management solutions, which makes them particularly relevant in environments where chemical refrigerants are restricted, undesirable, or impractical. Compliance with NEMA 12, NEMA 4, and NEMA 4X enclosure standards, alongside hazardous location certifications such as ATEX, enables deployment in industrial electrical enclosures where environmental sealing and explosion safety are mandatory. This certification footprint is not incidental; it expands the addressable application base beyond standard factory floors into outdoor industrial sites, washdown environments, and classified hazardous zones. Organizations evaluating thermal management strategies must therefore treat certification readiness as a market access precondition, not a post-purchase consideration.
Material Engineering and Durability
Material selection directly influences lifecycle performance in industrial cooling applications. Vortex tubes are primarily constructed from stainless steel to deliver corrosion resistance and structural durability in demanding industrial environments. This material baseline aligns with the operational requirements of facilities exposed to moisture, chemical splash, particulate contamination, or temperature cycling. Alternatives such as polycarbonate and other materials serve specific cost, weight, or application constraints, but stainless steel remains the engineering default for high-intensity industrial deployments. Procurement and engineering teams evaluating total cost of ownership must weigh initial material cost against maintenance frequency, failure rates, and enclosure compatibility over multi-year deployment horizons.
Compressed Air Infrastructure Dependency
Performance optimization for vortex cooling systems depends on compressed air supply stability. Industry product guidelines indicate that compressed air at 80 to 100 PSIG is required for optimal vortex tube performance, with filtration recommended to 5 microns or better. This operational parameter creates a direct link between vortex cooler adoption and a facility existing compressed air infrastructure. Enterprises planning deployment must assess air quality, pressure consistency, and filtration readiness, because degraded air supply can reduce cooling efficiency and increase wear on internal components. In turn, this dynamic creates an adjacent market for filtration integration, air preparation accessories, and system sizing consultation, expanding the strategic relevance of vortex cooler vendors beyond the tube itself.
Strategic Implications for 2026 Decision-Making
The 2026 planning cycle requires executives to make capital and portfolio decisions against a backdrop of moderate but consistent growth, a competitive field with clear leaders yet meaningful fragmentation, and a technology profile that favors reliability, certification readiness, and infrastructure compatibility over novelty. Several strategic implications follow directly from the macro architecture of this market.
First, growth visibility in the vortex cooler sector is sufficient to justify capacity planning and distribution investment, but it does not eliminate the need for segmentation precision. Aggregate growth rates and total market size establish the ceiling; regional intensity, material preference, and application mix determine where value is actually captured. Companies that operate solely on headline growth figures risk misallocating sales resources, over-indexing on low-intensity territories, or under-serving high-demand application verticals.
Second, the moderately concentrated competitive structure suggests that market share gains will depend on technical differentiation and application-specific trust rather than broad-based discounting. Certification portfolios, enclosure compatibility, CFM range breadth, and material durability are the parameters that industrial buyers evaluate when selecting between established vendors and emerging alternatives. Strategic newcomers and regional players can compete effectively by narrowing their focus to specific enclosure types, hazardous location requirements, or compressed air integration specialties rather than attempting to replicate full-line incumbents from day one.
Third, regulatory and environmental trends continue to reinforce the strategic appeal of refrigerant-free cooling. As industrial facilities navigate compliance complexity, enclosure protection requirements, and maintenance efficiency targets, vortex coolers offer a mechanically simple, chemically benign alternative. This positioning does not guarantee automatic market share expansion, but it does expand the strategic conversation from cost-per-unit to lifecycle reliability and compliance alignment. Decision-makers should therefore evaluate vortex cooler adoption within broader facility thermal management strategies, not as isolated component purchases.
Fourth, compressed air dependency introduces both an adoption requirement and a service integration opportunity. Facilities with mature, well-filtered compressed air systems will extract optimal performance from vortex cooling modules. Facilities with inconsistent pressure delivery or poor filtration will face reduced efficiency and higher maintenance exposure. This reality creates strategic value for vendors and channel partners who bundle air preparation guidance, filtration recommendations, and system sizing support alongside the cooling hardware itself.
Why Complete Intelligence Matters
Strategic planning in a growing but structurally nuanced market requires more than directional confidence. It requires precise regional demand indicators, application-level adoption intensity, material-segment revenue distribution, and competitive share mapping that can be translated directly into territory planning, product roadmap decisions, and procurement forecasting. Aggregated market size and a credible CAGR provide the narrative frame; segmentation detail provides the operational map.
Our full vortex cooler market research delivers that operational map. It expands each macro dimension discussed here into validated figures, scenario parameters, and segment-level comparisons that enable procurement, engineering, sales leadership, and corporate strategy teams to align on the same evidence base. Readers seeking the complete dataset, including regional and application splits, material-segment valuations, concentration analysis, and forward scenario ranges, should access the full report through our source page. The complete publication is designed to support quantifiable investment cases, capacity allocation models, and competitive response planning across the 2026 to 2032 forecast period.
The vortex cooler market is not a high-volatility sector, but it is a strategically dense one. Growth is real, competitive positioning is measurable, and adoption outcomes depend on infrastructure readiness, certification alignment, and material durability. For organizations operating in industrial cooling, enclosure thermal management, or compressed air system integration, the difference between a reactive market posture and a proactive strategic position lies in the depth of intelligence available at the point of decision. Our research is built to provide that depth, and the complete market study remains the most direct path to securing it.
For detailed analysis of this topic, please visit the official page: Vortex Cooler Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AI Game Generator Market Hits $247.3M in 2025, Projected to Surge to $1,171.1M by 2032 at 24.5% CAGR
By pmarketresearch, 2026-09-17
The Strategic Imperative: Navigating the AI Game Generators Market in 2026
Previewing PW Consulting's Comprehensive Market Intelligence Report
The landscape of video game development is undergoing a seismic shift, driven by the rapid maturation of generative artificial intelligence. What was once a niche experimentation phase has evolved into a core component of production pipelines across the global industry. For executives, investors, and product strategists, understanding the trajectory of AI Game Generators is no longer optional—it is critical for sustaining competitive advantage in a hyper-accelerated market environment.
PW Consulting is pleased to introduce our latest deep-dive research study, designed specifically to equip decision-makers with the actionable intelligence needed to navigate the forecast period from 2026 to 2032. This article serves as a strategic overview, highlighting the magnitude of the opportunity and the key dynamics shaping the sector, while reserving the granular financial modeling and segmentation data for our full proprietary report.
Market Trajectory and Historical Acceleration
The momentum behind AI-driven game generation is best understood through the lens of recent historical performance. The market has demonstrated remarkable resilience and growth velocity over the past half-decade. Starting from a baseline of 42.1 million USD in 2020, the sector expanded to 63.33 million USD in 2021, and crossed the 100 million USD threshold in 2022. This upward trend accelerated significantly, reaching 161.87 million USD in 2023 and approaching 199.47 million USD in 2024.
AI Game Generators Market
By the base year of 2025, the market size was estimated at 247.3 million USD. This historical compound growth sets the stage for a forecast period where expansion is expected to continue at a robust pace. Our analysis projects the market to reach 301.04 million USD in 2026, further climbing to 395.98 million USD in 2027, and 482.08 million USD in 2028. The trajectory suggests a significant milestone near the end of the decade, with projections indicating a valuation of 768.14 million USD by 2030. Ultimately, the forecast extends to 1171.1 million USD by 2032.
This growth narrative supports a Compound Annual Growth Rate (CAGR) of 24.5 percent over the forecast period. Such a rate indicates not just incremental improvement, but a fundamental transformation in how games are conceived, built, and iterated. For enterprise strategists, this velocity implies that window of opportunity for market entry or expansion is narrowing. The differentiator will not be access to technology, but the strategic integration of these tools into broader business models.
Technological Pillars and Deployment Strategies
The AI Game Generators Market is not a monolith; it is composed of distinct technological capabilities that serve different stages of the development lifecycle. Understanding which technology pillars drive value is essential for allocating R&D budgets and partnership resources. The landscape includes advanced systems for Text-to-3D Models, which allow developers to generate complex three-dimensional assets from simple prompts. This capability is reshaping asset creation pipelines, reducing the time required for modeling and texturing.
Simultaneously, Text-to-2D Assets and Sprites remain a critical component, particularly for 2D gaming genres and UI element generation. These tools enable rapid prototyping and style-consistent asset production. Beyond visual assets, Code Generation Tools are increasingly being utilized to automate scripting and logic implementation, allowing engineers to focus on architecture rather than repetitive coding tasks. Furthermore, Level Generation Systems are automating the creation of virtual environments, enabling procedural world-building that scales with player engagement needs.
Deployment models also play a crucial role in market adoption. The market is split between Cloud-Based solutions, which offer scalability and lower upfront infrastructure costs, and On-Premises deployments, which cater to studios with stringent data security or latency requirements. Our full report dissects the revenue contribution and adoption rates of each segment, providing a clear picture of where capital is flowing within the technology stack. While specific allocation percentages are detailed in the comprehensive study, the overarching trend favors flexible, scalable solutions that integrate seamlessly with existing engine workflows.
Competitive Landscape and Key Market Players
The competitive environment is characterized by a mix of specialized AI-native startups and established technology giants integrating AI into their existing ecosystems. Market concentration data indicates a moderate level of consolidation, with the top three players holding a significant share, while the top five firms capture a broader portion of the total revenue. This structure suggests that while dominance is being established, there remains room for agile innovators to capture niche segments.
Several key companies are defining the boundaries of what is possible in this sector. Rosebud AI, based in San Francisco, provides AI-powered prompt-to-game generation for creating playable 2D/3D browser games, assets, NPCs, and full experiences without coding. This end-to-end approach appeals to indie developers and rapid prototyping teams. Scenario, also headquartered in San Francisco, offers an AI platform for generating style-consistent game assets, images, video, 3D, and textures by training custom models on studio art data, a solution utilized by major studios such as Ubisoft.
Layer AI operates as a creative AI platform for game studios, offering image, video, 3D, and audio generation with custom styles, workflow automation, and high-volume production capabilities. Ludo.ai, with a presence in Sacramento and Seattle, focuses on an AI platform for game research, concept generation, market analysis, asset creation including sprites and 3D models, and prototypes to accelerate game development. On the environmental side, Promethean AI provides an AI system for procedural world-building and environment design, automating placement and generation of assets for virtual worlds.
Additionally, established giants are integrating these capabilities. Unity Technologies, based in San Francisco, offers Muse and ML-Agents for AI-assisted game development, prompt-based generation, and behavioral AI within Unity engine workflows. These companies represent the vanguard of the industry, and our report includes detailed profiling of their strategic moves, product roadmaps, and partnership ecosystems. Understanding the specific positioning of each player is vital for identifying potential collaborations or competitive threats.
Regulatory Dynamics and Ethical Considerations
As the market matures, the regulatory environment is becoming an increasingly important factor in strategic planning. The introduction of frameworks governing artificial intelligence is shaping how developers deploy generative tools. For instance, the EU AI Act entered into force in August 2024, with full applicability for most provisions expected by August 2026. Under this framework, most AI-powered video games are classified as minimal or no risk, requiring limited or no obligations. However, compliance readiness remains a key concern for studios operating across multiple jurisdictions.
Complementing regulatory frameworks, industry bodies are establishing best practices. In July 2025, the International Gaming Standards Association (IGSA) released an Ethical Use of Artificial Intelligence best practices document. This framework provides guidance for the AI in gaming industry, developed with input from regulatory authorities. The IGSA released nine best practices for ethical AI use in gaming, covering purpose documentation, fairness, and oversight. These guidelines are becoming a de facto standard for responsible development.
Furthermore, legal considerations regarding intellectual property remain complex. AI-generated content in games raises copyright considerations in many jurisdictions, where AI is not recognized as an author, requiring human oversight for protection. Strategic teams must account for these legal nuances when building pipelines that rely heavily on generative outputs. Additionally, the high computational demands for training custom generative models and real-time inference in game asset creation rely heavily on GPU infrastructure, adding a layer of technical and capital planning to the regulatory equation.
Operational Content and Strategic Utility of the Report
PW Consulting's full market research report is designed to move beyond high-level trends and provide the operational data necessary for execution. The study encompasses a thorough analysis of market size drivers, restraints, and opportunities. It offers a detailed segmentation analysis that breaks down the market by region, technology, and deployment mode, allowing readers to identify high-growth pockets within the broader landscape.
The report includes comprehensive profiles of the key companies mentioned, along with an analysis of recent developments such as the IGSA standards release. It provides a competitive benchmarking section that evaluates market positioning, product capabilities, and strategic focus areas. For financial planners, the report includes forecast models that project revenue flows over the 2026-2032 period, enabling precise budgeting and investment forecasting.
Additionally, the study addresses the industry context noise, including regulatory shifts and technological constraints like computational requirements. This holistic view ensures that decision-makers are not blindsided by external factors that could impact deployment timelines or cost structures. The FAQ section of the report tackles common queries regarding copyright, risk classification, and infrastructure needs, serving as a quick reference guide for legal and technical teams.
Conclusion: Securing Position in a High-Growth Sector
The AI Game Generators Market represents one of the most dynamic growth sectors in the technology and entertainment industries. With a projected CAGR of 24.5 percent and a market trajectory moving toward over 1 billion USD by 2032, the stakes for strategic positioning are high. The convergence of advanced generative models, evolving regulatory standards, and intense competition among key players creates a complex environment that demands precise intelligence.
AI Perfume Generator Market
PW Consulting's latest report is built to provide that precision. By integrating historical data, detailed segmentation analysis, and competitive profiling, this study offers a roadmap for navigating the forecast period. We invite industry leaders, investors, and strategic planners to access the full comprehensive report to gain the granular insights required to make informed decisions. The full breakdown of regional splits, specific technology revenue shares, and detailed financial forecasts is available in our complete market intelligence package.
In a market moving at this speed, visibility is currency. Ensure your organization has the clarity needed to capitalize on the opportunities within the AI Game Generators Market. Reach out to access the full study and secure your strategic edge for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: AI Game Generators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com