

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Casing Spools Market to Hit $1.02B by 2032, Growing at 5.12% CAGR from 2026-2032

Strategic Intelligence in a Decade of Transformation: Navigating the Worldwide Casing Spools Market (2026–2032)
The global casing spools market stands at a critical inflection point. Between 2020 and 2025, the sector demonstrated remarkable resilience, navigating commodity price fluctuations, supply chain realignments, and shifting exploration priorities to reach a baseline valuation of 720.5 million USD. Looking ahead to the 2026–2032 forecast window, the market is projected to expand at a compound annual growth rate of 5.12 percent, ultimately surpassing the 1 billion USD milestone by the decade's end. For executives, procurement leaders, and strategic planners operating in oilfield equipment, energy infrastructure, and surface wellhead systems, this trajectory represents far more than a top-line projection. It signals a structural realignment in how casing spool technologies are specified, manufactured, sourced, and integrated into broader well lifecycle strategies.
The Worldwide Casing Spools Market research study recently published by PW Consulting has been engineered to translate macroeconomic momentum into actionable decision intelligence. Rather than offering static snapshots, the analysis maps the interplay between drilling complexity, material innovation, regulatory pressure, and competitive consolidation. The following overview previews the strategic architecture of the report, illustrating how executives can leverage its findings to optimize capital allocation, mitigate supply chain exposure, and position product portfolios for high-growth operational environments.
Decoding the Macro Trajectory: What the Numbers Reveal for 2026 Decision-Makers
The five-year historical baseline (2020–2025) establishes a clear narrative of accelerating demand maturity. After navigating a period of operational consolidation and value engineering in the early part of the decade, the market rebounded with renewed investment velocity, closing 2025 at 720.5 million USD. The forecast period extends this momentum, projecting sequential growth through 2032, where the market is expected to reach 1,021.96 million USD. The 5.12 percent CAGR is not merely a statistical output; it reflects a compounding set of industry realities: expanding production scenarios in complex geological basins, the progressive retirement of legacy wellhead infrastructure, and the strategic shift toward integrated surface pressure control architectures that place casing spools at the center of well integrity management.
Crucially, the report contextualizes this growth within the operational realities facing OEMs, distributors, and end-users. Revenue expansion is not uniform across the value chain. Instead, it is being driven by targeted demand in high-pressure and high-temperature (HPHT) environments, deepwater and ultra-deepwater development corridors, and onshore basins where well completion cycles are intensifying. The report's macro framing allows executives to separate cyclical noise from structural adoption curves, enabling more precise scenario planning for procurement cycles, inventory positioning, and long-term capacity investments.
Product Architecture and Application Realities: A Deep Dive into Type and Use-Case Dynamics
Casing spool technology sits at the intersection of mechanical reliability, pressure containment, and operational standardization. The market's product landscape is anchored by three primary categories: standard casing spools, high-pressure and high-temperature (HPHT) casing spools, and multi-bowl wellhead systems. Standard configurations continue to serve the broadest installed base, particularly in mature onshore fields where cost efficiency, interchangeability, and API 6A compliance define procurement criteria. HPHT casing spools, by contrast, represent a high-value growth vector, driven by wells operating under extreme thermal and mechanical stress that demand enhanced sealing performance, corrosion-resistant metallurgy, and advanced dimensional tolerances. Multi-bowl wellhead systems address complex well architectures requiring multiple production or injection pathways, a configuration increasingly favored in phased field development and artificial lift integration.
From an application standpoint, the market is shaped by the divergent operational rhythms of onshore and offshore environments. Onshore operations continue to account for a substantial share of demand, reflecting ongoing drilling campaigns in conventional and unconventional reservoirs, as well as the retrofitting of existing wellheads to support extended production lifecycles. Offshore demand, while numerically smaller in aggregate volume, carries disproportionate strategic weight due to the technical complexity of subsea and deepwater systems, the elevated cost of failure, and the concentration of capital in large-scale offshore developments. The report's segmentation analysis dissects these demand drivers without reducing them to simplistic volume counts, instead mapping how pressure ratings, metallurgy specifications, hanger compatibility, and well lifecycle stages influence procurement behavior.
Regional Market Reconfiguration: Where Demand Is Concentrating and Why
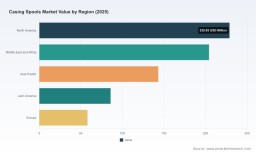
Geographic demand for casing spools is undergoing a meaningful redistribution. North America remains a central hub of activity, supported by mature basin redevelopment, shale-related well completion activity, and a dense ecosystem of oilfield service providers and equipment manufacturers. The Middle East and Africa sector reflects sustained investment in reservoir optimization, enhanced oil recovery initiatives, and high-capacity wellhead installations tied to long-term production commitments. Asia Pacific demand is broadening beyond traditional exploration to include expanded downstream integration, regional content provisions, and growing participation in offshore supply chains. Latin America and Europe contribute more specialized demand profiles, often shaped by deepwater access, regulatory frameworks, and localized content mandates that influence sourcing strategies.
The report resists the temptation to present regional data as static partitions. Instead, it examines how trade policy, steel and aluminum safeguarding measures, logistics constraints, and regional content requirements are reshaping where and how casing spools are produced, certified, and deployed. For multinational operators and equipment suppliers, regional analysis becomes a tool for evaluating localization opportunities, assessing tariff exposure, and aligning manufacturing footprints with shifting procurement geographies.
Competitive Architecture: How the Market Leaders Are Redefining Value Creation
The competitive landscape is characterized by a tiered structure in which a small group of integrated service and equipment providers holds a substantial share of high-complexity demand, while a broader field of manufacturers competes on specification compliance, regional availability, and cost positioning. The market's consolidated nature, with the top three competitors accounting for approximately 38.5 percent of revenue and the top five capturing over half of total market value, underscores the importance of strategic differentiation in an otherwise specification-driven environment.
Leading players have moved beyond offering discrete casing spool components. Their strategic relevance now stems from integrated wellhead assemblies, bundled surface pressure control solutions, digital monitoring integration, and increasingly, regional manufacturing and service partnerships. SLB continues to strengthen its position through high-value contract awards that bundle low-pressure, high-pressure, and thermal wellhead systems with artificial lift technologies, signaling a market preference for integrated lifecycle solutions. Baker Hughes has been actively restructuring its wellhead and pressure-control equipment capabilities, including the formation of surface pressure control joint ventures and the inauguration of dedicated service and manufacturing centers designed to expand regional capacity and responsiveness. TechnipFMC's recent subsea production system contract activity highlights the strategic importance of advanced casing spool solutions in deepwater and offshore development campaigns, especially where well integrity and production reliability are paramount.
Mid-tier and regional manufacturers remain highly relevant, particularly where API 6A compliance, competitive unit pricing, hanger compatibility, and localized service support drive procurement decisions. Companies such as Weatherford International, NOV Inc., Worldwide Oilfield Machine, Sentry Wellhead Systems, Kingsa Industries, Parveen Industries, and a growing cohort of Chinese and Eastern European manufacturers including CCSC Petroleum Equipment, All-Petro, Yulin Machinery (Aqe Machinery), Qilu Steel Group, and UZTEL S.A. illustrate the breadth of manufacturing capabilities serving onshore, offshore, sour service, and developing-market applications. Their competitive positioning often hinges on forgings and castings quality, product range breadth, lead-time reliability, and the ability to meet specific pressure ratings, bore designs, and PSL requirements.
The report's competitive analysis does not stop at corporate profiling. It evaluates how product roadmaps, materials innovation, supply partnerships, joint venture structures, and recent contract awards are reshaping competitive advantage. By linking corporate strategy to market share dynamics, the study helps clients assess which competitors are expanding capability footprints, which are consolidating around core wellhead platforms, and which are creating new pathways for value capture through regionalization or specialized product lines.
Structural Dynamics: Materials, Regulations, Tariffs, and the New Cost Environment
No strategic assessment of the casing spools market is complete without confronting the operating environment that governs cost, compliance, and competitiveness. Casing spools are predominantly manufactured from forged steel or low-alloy steel to meet API Spec 6A requirements for materials, dimensions, test procedures, and pressure ratings. This specification baseline provides a common language for procurement, but it also means that raw material volatility and trade policy changes can transmit quickly through the supply chain. Recent policy environments have introduced significant uncertainty, including the elevation of steel and aluminum duties and their extension to derivative goods, with potential cost implications for wellhead equipment that analysts estimate could range from 4 percent to 40 percent depending on sourcing configuration and product complexity.
Worldwide Casing Collar Locator Market
Simultaneously, the market is being shaped by macro-trend acceleration. Rising investments in deepwater, ultra-deepwater, and HPHT drilling projects are increasing demand for advanced casing spools with enhanced sealing technologies and improved corrosion resistance. Policy shifts in key oil-producing regions have also reinforced local content requirements, prompting manufacturers to invest in regional production capabilities and service infrastructure to preserve eligibility for major procurement programs. These dynamics create a dual pressure: cost containment on one side, and capability escalation on the other. The report maps this tension explicitly, helping clients evaluate whether to pursue standardization and cost efficiency, differentiate through HPHT and corrosion-resistant offerings, or localize production to meet content requirements and reduce tariff exposure.
Worldwide Casing Spools Market
What the Report Delivers: Operational Intelligence for Executive Decision-Making
The Worldwide Casing Spools Market study is designed as a working intelligence asset, not a summary document. It integrates historical baselines, a detailed 2026–2032 forecast, segmentation analysis by region, type, and application, and a structured competitive landscape review anchored by recent contract awards, joint venture formations, and facility expansions. The report also overlays industry context on materials, regulatory compliance, tariff exposure, and macro demand drivers to provide a multi-layered view of market risk and opportunity.
Practically, this means executives can use the study to:
- Benchmark procurement forecasts against market-level demand trajectories and segmentation patterns
- Evaluate whether product portfolios are aligned to the fastest-growing specifications, including HPHT, multi-bowl configurations, and enhanced sealing designs
- Assess regional sourcing strategies in light of local content requirements, tariff exposure, and manufacturing footprint decisions
- Identify competitor moves that may affect pricing, lead times, bundled solution offerings, or after-sales service expectations
- Frame capital allocation for production capacity, inventory strategy, and service expansion in markets where wellhead equipment demand is intensifying
- Integrate digital monitoring and integrated wellhead architectures into product positioning where end-users increasingly prefer bundled, lifecycle-oriented solutions
The report's structure enables cross-functional use. Engineers and procurement teams can reference specification-relevant demand patterns and application assumptions. Commercial and strategy leaders can use competitive mapping and regional dynamics to refine market-entry, partnership, and pricing strategies. Senior executives can rely on the forecast architecture and concentration metrics to test strategic scenarios and align investment priorities with durable demand shifts rather than short-term cycle noise.
Looking Ahead: Turning Market Intelligence into Strategic Advantage
The casing spools market is not merely expanding; it is being redefined by technical complexity, regulatory constraints, regional content policy, and the strategic bundling of wellhead equipment into broader surface pressure control and production systems. In this environment, organizations that rely on historical assumptions or generic equipment forecasts risk misaligning their portfolios with where value is actually being created. The Worldwide Casing Spools Market research study offers a structured, data-anchored pathway to close that gap.
By combining a robust historical baseline, a detailed 2026–2032 forecast, segmentation analysis, competitive profiling, and real-world corporate developments, the report gives decision-makers the context needed to act with confidence in a market where margin, compliance, and reliability are increasingly inseparable from strategic success. For executives seeking to protect supply continuity, optimize product positioning, and capitalize on high-growth segments, the full study provides the depth, segmentation precision, and forward-looking intelligence required to convert market visibility into measurable advantage.
The complete analysis, including detailed segmentation breakdowns, regional and application-level demand mapping, and extended competitive intelligence, is available through the full Worldwide Casing Spools Market report. Access the full study to translate these high-level insights into precise, decision-ready intelligence for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Casing Spools Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com