

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Steam Reformers Market to Hit $1.17 Billion by 2032, 6.12% CAGR

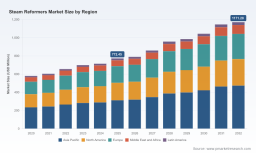
Global Steam Reformers Market 2026: Strategic Intelligence for Capital Allocation and Competitive Positioning
The worldwide steam reformers market stands at a critical inflection point as the energy and chemicals industries navigate the dual imperatives of operational efficiency and decarbonization. Steam methane reforming remains the dominant technological pathway for large-scale hydrogen and syngas production, anchoring capital-intensive projects across oil refining, ammonia synthesis, methanol manufacturing, and merchant hydrogen distribution. For executives planning capacity expansions, technology selections, or feedstock procurement strategies in 2026 and beyond, fragmented data and anecdotal market signals are no longer sufficient. PW Consulting's newly released Worldwide Steam Reformers Market study delivers a rigorous, decision-ready intelligence framework that translates historical performance into actionable forward-looking strategy.
This article serves as a strategic preview of the full report. It outlines the structural forces shaping the market, highlights the operational and competitive dimensions covered in depth, and explains why the complete intelligence package is essential for capital allocation, vendor evaluation, and risk management in the coming years.
Market Trajectory and Macro Landscape: Why 2026 Is a Pivotal Year
The steam reformers market has demonstrated steady expansion over the past half-decade, supported by sustained demand from downstream chemical and refining operations. Historical valuations from 2020 through 2025 reflect a market that has consistently scaled as industrial hydrogen consumption, syngas integration, and process optimization initiatives gained momentum. The trajectory continues into the forecast window, with the market projected to reach approximately 790 million USD in 2026 and climb steadily toward the 1.1-billion USD threshold by the early 2030s. Over the full forecast horizon, the compound annual growth rate is estimated at 6.12 percent, indicating a durable upward trend rather than a temporary surge.
This growth profile carries direct implications for 2026 decision-making. First, it signals that demand for reforming capacity is not cyclical in the short term; it is structurally reinforced by longLead industrial projects and the gradual integration of hydrogen-bearing value chains. Second, it underscores the importance of timing. Firms that delay capacity evaluations or technology comparisons risk entering procurement cycles when vendor backlogs are already stretched and customization lead times extend. Third, the steady expansion suggests that pricing dynamics, feedstock cost structures, and equipment availability will increasingly influence project economics, making macro awareness a prerequisite for sound internal rate-of-return modeling.
The complete report anchors these macro movements in a transparent historical series and forward projection, allowing readers to benchmark internal assumptions against independently modeled trajectories. Rather than presenting isolated snapshots, the analysis connects year-over-year patterns to the underlying drivers that will sustain volume growth well beyond the immediate forecast window.
Core Segmentation Dimensions and How They Shape Investment Decisions
Understanding where growth concentrates—and why—requires a disciplined breakdown of feedstock pathways, application end-uses, and geographic deployment profiles. The report deconstructs the market across these axes without isolating narrow percentage splits or nominal sub-values that would oversimplify regional and sectoral dynamics. Instead, it frames each dimension in terms of operational relevance, cost sensitivity, and strategic prioritization.
Feedstock selection remains the foundational variable for reformer design, operating economics, and emissions profiling. Natural gas continues to dominate as the primary input for steam methane reforming, reflecting its widespread availability, established infrastructure, and favorable stoichiometry for hydrogen yield. Naphtha and other hydrocarbon streams, including LPG, represent complementary pathways that gain relevance in regions where natural gas logistics are constrained or where integration with existing petrochemical complexes offers economic advantages. The report evaluates how these feedstock options interact with reformer configuration, catalyst requirements, and downstream purification needs, helping procurement teams align technology choices with local supply realities rather than generic benchmark assumptions.
Application end-uses further differentiate project priorities. Oil refineries continue to represent a major consumption base, driven by hydrogen demand for hydrotreating and hydrocracking operations. Ammonia production remains tightly linked to reforming capacity, given the scale of hydrogen requirements in conventional ammonia synthesis routes. Methanol production and merchant hydrogen output constitute additional demand pillars, each with distinct throughput sensitivities, purity specifications, and operating profiles. The study maps how these application segments influence reformer sizing, thermal design, and integration with ancillary systems such as pressure swing adsorption units, carbon management equipment, and heat recovery trains.
Geographic deployment patterns add another strategic layer. Asia Pacific, North America, Europe, the Middle East and Africa, and Latin America each present different combinations of feedstock cost structures, industrial demand intensity, regulatory expectations, and project development rhythms. The report assesses how these regional contexts shape vendor presence, engineering preferences, and implementation timelines. Decision-makers gain a structured basis for evaluating where to pursue near-term capacity additions, where to monitor emerging demand clusters, and where to anticipate longer development cycles that may affect equipment delivery and commissioning schedules.
Competitive Dynamics: Technology Portfolio Positioning and Strategic Implications
The steam reformers market is characterized by a mix of engineering groups, equipment specialists, catalyst providers, and component manufacturers. Rather than competing on a single performance metric, firms differentiate through design philosophy, thermal efficiency, materials durability, modularization capability, and integration with downstream or emissions-control systems. PW Consulting's analysis profiles the leading players and decodes how their capabilities translate into commercial leverage for buyers and investors.
European and German-headquartered engineering organizations occupy a prominent position in the competitive landscape. Linde Engineering has built a substantial global footprint through multiple reforming furnace deliveries and modular hydrogen plant configurations, offering both top-fired and side-fired approaches and a strong record in hydrogen and syngas projects from varied feedstocks. thyssenkrupp Uhde emphasizes proprietary reforming technology with cold outlet manifold systems, designing reformers that operate across elevated temperature and pressure ranges with a documented deployment history across dozens of plants. Bihl focuses on primary steam-methane reformer design and supply, alongside waste heat recovery sections and fired heaters, extending its relevance to auto-thermal reforming pathways. Mahler AGS develops hydroform-type SMR plants tailored for high-purity hydrogen production, combining top-fired reformer design with purification systems.
In parallel, firms such as Topsoe contribute radiant wall reformer designs backed by a large installed base and a broader offering that spans catalysts and process technology. Schmidt + Clemens specializes in reformer tubes and outlet manifolds, components that directly influence reliability under high-temperature service. MetalTek brings centrifugal casting expertise for reformer tubes engineered to withstand prolonged exposure to creep and stress conditions in demanding petrochemical environments. Clariant complements the equipment ecosystem with nickel-based reforming catalysts designed for tubular primary reformers producing syngas for hydrogen, ammonia, and methanol applications.
Air Liquide Engineering & Construction and Technip Energies further illustrate the breadth of competitive approaches. Air Liquide focuses on steam methane reforming technology across small and large scales, with attention to integration pathways that align reforming operations with carbon capture concepts. Technip Energies supplies high-efficiency top-fired steam reformers for hydrogen production plants, including low-NOx burner integration that reflects growing attention to emissions performance.
This competitive mosaic matters for 2026 strategy because vendor selection increasingly determines not only capital cost but also long-term operability, maintenance burden, and flexibility to adapt to changing feedstock or regulatory conditions. The report does not simply list vendor attributes; it translates them into procurement considerations. Readers gain insight into where design differentiation carries the most weight, how modularization affects project phasing, and what technical trade-offs should be evaluated when comparing reformer tube materials, furnace firing configurations, and catalyst compatibility.
Recent industry activity reinforces the need for up-to-date competitive tracking. In late 2025, Sypox advanced the development of a large-scale electric steam methane reformer concept, using renewable electricity to produce syngas at a substantial daily rate in partnership with a catalyst supplier. While such projects remain indicative of emerging electrification and hybrid pathway exploration rather than immediate market displacement, they signal that technology roadmaps are expanding and that future procurement comparisons will need to account for alternative energy input models, catalyst integration, and process intensification options. The full report situates these developments within the broader competitive landscape so that decision-makers can distinguish near-term commercial reality from longer-term optionality.
Operational Context and External Pressure Points
Market performance does not occur in a vacuum. Feedstock pricing, production availability, and equipment supply constraints all interact to shape project feasibility and timing. The report integrates external context that directly influences reformer economics, including the evolving cost environment for natural gas as a primary feedstock and the trajectory of domestic production that supports feedstock supply continuity. Rising feedstock cost expectations can alter sensitivity analyses, shift the relative attractiveness of alternative hydrocarbon inputs, and affect the payback logic for efficiency upgrades or carbon management add-ons. At the same time, stronger production outlooks may ease some supply concerns while intensifying competition for engineering and fabrication resources.
These dynamics underscore why a static market snapshot is insufficient. Executive teams need a framework that connects external cost signals to internal project assumptions, evaluates how feedstock price movement alters the expected value of different reformer designs, and anticipates where backlogs or component lead times could influence implementation schedules. The study is structured to support that kind of integrated assessment.
What the Full Study Delivers: Analytical Depth and Practical Utility
Beyond the macro outlook and competitive profiling, the Worldwide Steam Reformers Market report is built around decision tools that can be applied directly to capital planning, procurement strategy, and investor communication. The study combines quantitative trajectory modeling with qualitative assessment of technology, applications, feedstocks, and regional deployment patterns to create a cohesive working reference for project evaluation.
Key elements of the report include:
- A transparent historical and forecast series that grounds internal projections in a consistent analytical baseline, enabling readers to test their own growth assumptions against modeled trends.
- Segment-level analysis across feedstock pathways and application end-uses that explains operational implications rather than merely reporting numeric splits, helping teams match reformer configurations to site-specific requirements.
- Geographic assessment that contextualizes regional demand, feedstock logistics, and project development environments so that expansion plans reflect local realities rather than global averages.
- Competitive profiling that maps vendor capabilities, design philosophies, and integration strengths to procurement considerations, supporting more disciplined vendor shortlisting and request-for-proposal preparation.
- Contextual integration of feedstock cost and supply signals, with commentary on how these factors influence project economics, sensitivity ranges, and timing choices.
- Operational and strategic synthesis that connects market momentum to practical implications for capacity planning, technology selection, and risk management in the 2026 to 2032 window.
The emphasis throughout is on usable intelligence. The report is designed for teams that need to justify capital commitments, compare engineering options, assess feedstock exposure, and communicate market logic to internal stakeholders or external partners. By combining market sizing with structural analysis and competitive decoding, it supports both strategic positioning and operational execution.
Worldwide Steam Reformers Market
Worldwide Reformer Unit Market
Strategic Read-Through for 2026 Decision Makers
For organizations evaluating hydrogen-related capacity, syngas integration, or reformer technology selection in 2026, the strategic message is clear: the market is expanding on a durable basis, but execution advantage will be determined by how well decision-makers interpret the underlying segmentation, competitive differentiation, and external cost dynamics. The firms that succeed will be those that treat steam reforming not as a commodity equipment purchase but as a long-duration process choice with implications for efficiency, emissions management, uptime, and future flexibility.
PW Consulting's study is designed to support that level of judgment. It provides the analytical grounding needed to separate genuine growth opportunities from noise, align technology and feedstock choices with regional and application realities, and anticipate how competitive and supply-side conditions may influence project outcomes over the forecast period. The complete report contains the detailed segmentation analysis, company evaluations, and forward modeling that turn high-level market awareness into concrete action.
Accessing the Full Intelligence Package
This preview has outlined the strategic rationale behind the Worldwide Steam Reformers Market study and the analytical dimensions it covers. To move from directional understanding to execution-ready intelligence, decision-makers should consult the full report, where detailed market sizing, segmentation breakdowns, competitive analysis, and forecast trajectories are presented in a structured format for direct application to capital planning and procurement strategy. The complete study is available through the source page, where the full dataset, methodology context, and applied insights can be reviewed in depth.
For detailed analysis of this topic, please visit the official page: Worldwide Steam Reformers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com