

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Regatta Buoys Market to Hit $190.81M by 2032 at 6.54% CAGR

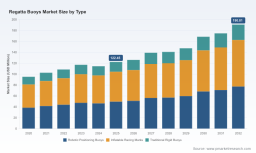
Global Regatta Buoys Market 2026–2032: Strategic Intelligence for Nautical Event Stakeholders
The Worldwide Regatta Buoys Market is entering a decisive growth cycle. As the nautical sports ecosystem expands beyond traditional sailing into rowing, paddle disciplines, and large-scale marine festivals, the infrastructure that defines competitive courses is undergoing a parallel transformation. Our latest market research, Worldwide Regatta Buoys Market, maps this evolution with a forensic lens on technology adoption, supply chain resilience, and competitive positioning. For executives, procurement leaders, and event organizers operating in 2026 and beyond, this report is not a retrospective summary—it is a forward-looking decision architecture.
Worldwide Regatta Buoys Market
Beacon Buoys Market
Between 2020 and 2025, the market demonstrated a clear recovery and expansion trajectory following early disruption cycles, with revenues climbing steadily to an estimated USD 122.45 million in our base year. Looking ahead, the forecast window from 2026 through 2032 projects sustained momentum, anchored by a compound annual growth rate of 6.54 percent. By the close of the outlook period, total market revenue is projected to approach the USD 190 million threshold. These figures are not abstract statistics; they represent a structural shift in how races are marked, managed, and experienced across global waterways. What separates this analysis from conventional industry tallies is the deliberate focus on operational inflection points: the migration from anchor-dependent layouts to autonomous positioning systems, the material science driving longevity in harsh marine environments, and the regulatory pacing that dictates event deployment timelines.
The 2026 Decision Lens: Why Timing Matters
Firms that treat buoy procurement as a commoditized purchasing exercise are increasingly exposed to hidden costs. Traditional deployment models rely on heavy anchor systems, manual course alignment, and reactive replacement cycles. Each of these steps introduces labor premiums, fuel consumption, and positioning drift that erode both budget predictability and race-day reliability. The 2026–2032 forecast window captures a market where these pain points are being systematically addressed through robotic GPS-controlled buoys and higher-durability inflatable architectures. Decision-makers who understand the cadence of this transition can align capital planning, vendor partnerships, and event scheduling before competitor organizations lock in early-mover advantages.
This research is engineered to answer three executive-level questions that generic market sizing cannot resolve. First, where is the revenue gravity shifting as event formats diversify across sailing, rowing, paddling, and festival environments? Second, which sub-segments command the highest strategic relevance for procurement and product development, and how do their relative weightings inform resource allocation? Third, what competitive asymmetries are emerging among manufacturers who are scaling customization, reducing maintenance footprints, and embedding autonomous navigation into routine race operations? By addressing these questions without resorting to superficial percentage breakdowns, the report equips leadership teams to prioritize investments that compound over the forecast horizon rather than deliver a single-season tactical fix.
Report Architecture: Operational Intelligence Over Static Sizing
A robust market study must bridge the gap between high-level revenue projections and the practical realities of on-water deployment. Our Worldwide Regatta Buoys Market report is structured to deliver exactly that bridge. The analysis begins with a diagnostic of market concentration dynamics, revealing how consolidated the competitive field has become and where fragmentation still creates entry opportunities. From there, the research decomposes the ecosystem across three interlocking dimensions: product architecture, geographic demand distribution, and end-use application profiles.
The segmentation framework is deliberately granular in scope but disciplined in delivery. Readers receive a structured assessment of how robotic positioning buoys, inflatable racing marks, and traditional rigid buoys each serve distinct operational requirements, durability expectations, and visibility standards. Rather than reducing these categories to isolated share figures, the report evaluates them through total addressable demand, replacement cycle economics, and performance trade-offs that event organizers and manufacturers face in live conditions. This approach ensures that procurement teams can benchmark specifications against real deployment scenarios, while product leaders can identify which design attributes—UV stabilization, tensile fabric strength, color contrast, inflation reliability, or autonomous holding capability—are driving purchasing preference in each context.
Geographic coverage is treated with equal analytical rigor. The research traces how regional event calendars, regulatory environments, and maritime traditions shape localized demand patterns, without reducing complex territories to static snapshots. Similarly, the application analysis maps how core regatta and yachting competitions interact with secondary growth vectors such as rowing and paddling sports and broader marine events and festivals. By presenting these layers as interconnected demand drivers rather than independent silos, the report helps organizations model scenario-based revenue pathways, anticipate substitution effects, and plan for the burden of multi-sport event programming on buoy fleets.
Competitive Landscape: Scale, Specialization, and Autonomy
The supplier landscape in regatta buoy manufacturing reflects a blend of established marine equipment brands, regional fabricators, and technology-forward entrants redefining course-marking logistics. Leading generalist and specialist players such as Plastimo, Crewsaver, Certec, ETP Race Marks, Osculati, and G.F.N. SRL anchor the traditional and inflatable segments, each bringing distinct strengths in material construction, color visibility, and event-specific form factors. Plastimo, for instance, has built a reputation around large-format inflatable marks in high-visibility PVC with practical field features, while Crewsaver and Certec emphasize cylindrical and conical inflatable designs optimized for sailing and watersport visibility. ETP Race Marks differentiates through custom fabrication capabilities spanning varied shapes, sizes, and print options, supporting event organizers who need tailored marking solutions for yachts, triathlons, and open-water competitions.
Parallel to this established base, a next-generation cohort is reshaping expectations around course precision and labor efficiency. MarkSetBot and WaterSportMarks exemplify the shift toward self-propelled, GPS-controlled sailing marks that maintain position without conventional anchoring. MarkSetBot’s recent product iteration introduced enhancements targeting race-day performance, on-water operation, and lower maintenance requirements—an evolution that directly addresses the operational friction historically associated with anchor deployment and repositioning. WaterSportMarks complements this trajectory with robotic GPS-controlled buoys engineered for effortless anchoring and autonomous positioning, reducing setup time and improving course integrity under variable water conditions. These systems are not merely convenience upgrades; they are becoming strategic assets for events where scheduling precision, environmental stewardship, and repeatable course geometry carry competitive and reputational weight.
The competitive dynamics also feature regional specialists such as Flexitank and TurtlePac, whose inflatable buoy offerings support regattas and water sports events with flexible sizing and material choices, including PVC-free alternatives. This diversification matters because procurement decisions increasingly weigh longevity, environmental compliance, and visibility alongside unit cost. Suppliers capable of harmonizing durability with ecological considerations are gaining traction, particularly as event organizers and regulatory bodies scrutinize waste, degradation, and marine compatibility. In this environment, competitive advantage is shifting from volume alone toward solution reliability, customization responsiveness, and the ability to support event teams through setup, recovery, and maintenance workflows.
Market Dynamics: Materials, Regulation, and Automation
Three intersecting forces are defining the operating environment for regatta buoys through the forecast period. The first is materials engineering. Modern regatta buoys are predominantly constructed from UV-stabilized polyethylene or high-tenancy PVC tarpaulin, with specifications commonly calibrated around durable fabric weights and resistance profiles designed to withstand prolonged sun exposure, abrasion, and saltwater conditions. Inflatable variants increasingly incorporate high-visibility color treatments and, in some product lines, PVC-free formulations to align with environmental expectations and marine stewardship goals. For procurement leaders, these material choices translate directly into service life, replacement frequency, and total cost of ownership, making specification literacy a competitive necessity rather than a back-office detail.
The second force is regulatory pacing. Marine events, including regattas, operate within layered authorization frameworks that can dictate lead times, waterway access, and operational compliance. Requirements such as advance permitting for boat races on state waters illustrate how event planning is gated by procedural timelines that procurement and logistics teams must accommodate well before race week. These regulatory rhythms influence not only when buoy fleets must be provisioned and positioned, but also how standardized, traceable, and reliably deployable those systems need to be. Organizations that integrate permitting calendars into their equipment planning reduce the risk of last-minute substitution, rushed logistics, and course-design compromises.
The third force is automation. The growing adoption of GPS-controlled robotic buoys is reducing dependence on traditional anchoring, with measurable implications for setup speed, fuel usage, and positioning accuracy. By holding position autonomously, these systems allow race committees to adjust courses in near real time, respond to shifting wind or current patterns, and minimize the physical footprint of course-laying operations. The strategic significance extends beyond efficiency metrics: autonomous marking supports more complex course geometries, enables faster recovery and redeployment between race legs, and improves repeatability for multi-day events where course consistency directly affects fairness and spectator experience. As these platforms mature, they are becoming central to event operational models rather than niche add-ons.
2026 and Beyond: Positioning for the Intelligence Gap
The Worldwide Regatta Buoys Market is not merely expanding; it is reconfiguring around autonomy, material durability, custom event integration, and regulatory-aligned planning. For organizations operating in this space, the difference between reactive spending and strategic advantage will come down to the quality of market intelligence available at the point of decision. Our research is built to close that gap. It consolidates demand trajectories, competitive positioning, application-level demand drivers, and operational dynamics into a single analytical framework that can be used for procurement planning, product roadmap prioritization, partnership strategy, and event-operations forecasting.
The full report delivers the segmented breakdowns, regional demand patterns, application weightings, concentration metrics, and company-level competitive profiles necessary to translate macro trends into executable strategy. It also contextualizes recent developments—such as autonomous buoy deployments in high-profile competitive settings and refreshed product generations aimed at race-day performance and maintenance reduction—within the broader forecast narrative. For leaders who need to validate assumptions, benchmark vendor capabilities, and model growth pathways through 2032, this intelligence offers a structured path from observation to action.
To access the complete dataset, detailed segmentation evaluations, competitive profiles, and forward-looking scenario analysis, explore the full Worldwide Regatta Buoys Market research. The executive summary provided here is designed to demonstrate analytical depth and strategic relevance; the complete study is where the numbers, comparisons, and deployment frameworks that support confident 2026 planning are fully realized.
For detailed analysis of this topic, please visit the official page: Worldwide Regatta Buoys Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com