

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Polyolefin Antioxidants Market to Hit $2,298.61 Million by 2032 at 4.85% CAGR

Strategic Imperatives in the Global Polyolefin Antioxidants Market: A 2026 Outlook
Introduction: The Critical Role of Stabilization in Polymer Durability
The global polyolefin antioxidants market stands at a pivotal juncture as we enter 2026. As the backbone of modern polymer processing, polyolefins such as polyethylene and polypropylene require robust stabilization to withstand thermal degradation during processing and oxidative stress during service life. For manufacturers, compounders, and end-users, understanding the trajectory of antioxidant demand is not merely an academic exercise—it is a strategic necessity. The ability to anticipate market shifts, regulatory pressures, and competitive moves defines the resilience of supply chains in the plastics industry.
This analysis serves as a precursor to the comprehensive Worldwide Polyolefin Antioxidants Market study released by PW Consulting. Our objective is to outline the macro-environmental forces shaping the sector and demonstrate why actionable intelligence is vital for corporate strategy in 2026 and beyond. The market has shown resilience despite volatile raw material costs and shifting regulatory landscapes, signaling a mature yet evolving ecosystem.
Market Trajectory and Historical Performance
The market size has demonstrated a consistent upward trajectory over the past half-decade, reflecting the insatiable global demand for plastic products across packaging, automotive, and construction sectors. Historical data from 2020 through 2025 indicates a steady recovery and growth pattern following initial pandemic-related disruptions. In 2020, the market valuation stood at approximately 1302.1 million USD. This figure climbed to 1386.8 million USD in 2021 and reached 1449.36 million USD by 2022.
Worldwide Polyolefin Antioxidants Market
A notable acceleration occurred in 2024, with revenue hitting 1593.45 million USD, culminating in a base year 2025 estimate of 1650.0 million USD. This growth underscores the critical integration of antioxidants in high-performance polymer applications. Looking forward, the forecast period from 2026 to 2032 projects continued expansion. The market is expected to begin 2026 at 1723.94 million USD, progressing toward 2298.61 million USD by 2032.
This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 4.85 percent throughout the forecast period. Such a rate suggests steady, moderate expansion rather than explosive volatility, indicating a market where strategic positioning and efficiency gains matter more than sheer volume grabs. However, slight contractions in specific forecast years, such as the dip projected between 2027 and 2028, highlight the sensitivity of the market to external economic and supply chain variables.
Segmentation Dynamics: Types and Applications
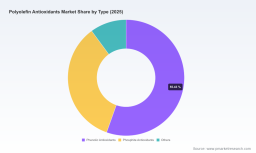
The market is fundamentally divided by chemical type and end-use application, each carrying distinct implications for supply chain management and product development. In terms of chemical composition, phenolic antioxidants and phosphite antioxidants dominate the landscape. Phenolic antioxidants are widely recognized for their ability to scavenge free radicals, making them essential for long-term thermal stability in polyolefins. Phosphite antioxidants, conversely, play a crucial role during the melt processing phase, preventing degradation under high temperatures.
Rubber Antioxidant Market
While specific regional revenue splits and precise percentage breakdowns of these segments are detailed in the full report, it is important to understand the strategic weight of these categories. The balance between phenolic and phosphite usage often depends on the specific processing requirements of the polyolefin compound. For instance, applications requiring high heat resistance during extrusion may lean heavily on phosphite varieties, whereas final product durability might prioritize phenolic stabilizers.
Regarding applications, the packaging sector remains a primary driver of demand. The need for durable films and containers that resist oxidation extends shelf life and maintains integrity. Automotive and construction sectors follow closely, where polymer components must endure harsh environmental conditions over extended lifecycles. The interplay between these application sectors dictates demand fluctuations. For example, a surge in automotive lightweighting initiatives using polypropylene directly ripples through the antioxidants market. Understanding which application segment is driving growth in a specific region is key to targeting sales and production strategies effectively.
Competitive Landscape and Key Players
The industry is characterized by a moderately concentrated competitive structure. The top three players hold a significant market share, while the top five companies consolidate a majority of the revenue. This concentration suggests that scale, technology, and regulatory compliance are significant barriers to entry. Major corporations are actively managing their portfolios through innovation, capacity expansion, and strategic compliance updates.
Key entities shaping this landscape include BASF SE, headquartered in Ludwigshafen, Germany. BASF continues to lead with its Irganox and Irgafos series, tailored for stabilization in films, pipes, and automotive applications. In October 2025, BASF launched Irganox 1135, a high-performance phenolic antioxidant designed for polyolefin masterbatches with improved migration resistance. This product launch signals a focus on high-value specialty grades rather than commoditized volumes.
Songwon Industrial Group, based in Ulsan, South Korea, is another critical player. They provide SONOX primary and secondary antioxidants emphasizing heat and oxidation resistance. In June 2025, Songwon expanded production capacity for phosphite antioxidants in their Ulsan facility by 20 percent to meet rising polyolefin demand. This capacity expansion indicates a bullish outlook on regional manufacturing needs and supply security.
SI Group (SICPA Specialty Chemicals), located in Schenectady, NY, USA, supplies Lowinox and Weston phosphite antioxidants for polyolefin compounding. Notably, in March 2025, SI Group achieved a REACH compliance update for Weston 619F phosphite used in polyolefin stabilization. This regulatory milestone is crucial for maintaining access to the European market. Other significant contributors include Clariant AG in Switzerland with their Hostanox and Hostaphos lines, Sumitomo Chemical Co., Ltd. in Tokyo with Sumilizer series, and Addivant, now part of SI Group, known for Naugard phenolic antioxidants.
Regional players are also gaining traction. Everlight Chemical Industrial Corp. in Taipei supplies Eversorb and Evernox antioxidants, while Rianlon Corporation in Shijiazhuang, China, manufactures Songnox phenolic and phosphite antioxidants, focusing on cost-effective blends for global markets. The presence of cost-focused manufacturers in Asia alongside technology leaders in Europe and North America creates a dynamic competitive environment where pricing pressure meets performance requirements.
Industry Dynamics: Raw Materials and Regulatory Headwinds
Strategic planning in 2026 must account for volatile input costs and stringent regulatory frameworks. Raw material pricing has been a significant variable. Phenol spot prices reached 1450 USD per metric ton in Q4 2025, marking a 12 percent increase year-over-year due to supply tightness from Asian producers. This upward pressure on key feedstock directly impacts the cost structure of phenolic antioxidants. Simultaneously, phosphorous acid prices increased to 1200 USD per metric ton in Asia during Q3 2025 amid raw phosphate disruptions. These cost escalations require manufacturers to optimize formulations or pass costs through the value chain carefully.
Regulatory compliance remains a critical filter for market access. The EU REACH Annex XVII restricts certain phosphite antioxidants in polyolefins if hydrolyzate levels exceed 0.1 percent. This regulation, highlighted by the European Chemicals Agency in February 2024, forces formulators to monitor degradation products closely. Non-compliance can lead to market exclusion, making regulatory intelligence a core competency for suppliers. Additionally, trade policies continue to shape flow patterns. US Section 301 tariffs on Chinese-origin antioxidants remain at 25 percent for polyolefin additives imported post-2024. This tariff structure influences sourcing decisions, encouraging buyers to diversify supply chains away from tariff-exposed origins or absorb the cost margin erosion.
Strategic Implications for 2026 Decision Makers
For executives and strategists navigating the 2026 landscape, several imperatives emerge from this macro analysis. First, supply chain resilience is paramount. Given the tariff structures and raw material volatility, reliance on single-source suppliers from specific regions poses a risk. Diversifying sourcing between established European and North American producers and cost-competitive Asian manufacturers requires a nuanced understanding of total landed cost, including duties and logistics.
Second, innovation must focus on compliance and performance. The regulatory environment, particularly in Europe, is tightening around chemical safety and degradation products. Companies that proactively adapt their formulations to meet REACH standards and invest in migration-resistant technologies, similar to recent launches by major players, will secure a competitive advantage. Third, capacity planning must align with regional demand shifts. The capacity expansion by Songwon suggests strong demand in Asia Pacific, while regulatory pressures may shift some production or formulation activities closer to end markets in North America and Europe.
The market concentration indicates that partnerships with top-tier suppliers can guarantee stability, but niche players offering cost-effective blends may provide flexibility in price-sensitive segments. Decision-makers need to balance the security of established brands with the cost efficiencies offered by emerging competitors.
Conclusion: Unlocking Comprehensive Intelligence
The polyolefin antioxidants market is a complex ecosystem driven by chemical innovation, regulatory compliance, and raw material economics. While the macro trends point to steady growth supported by a 4.85 percent CAGR, the devil lies in the details. Regional disparities, specific application growth rates, and precise competitive market shares require granular analysis to inform accurate forecasting and investment decisions.
This overview highlights the strategic context necessary for high-level planning. However, to truly optimize supply chains, pricing strategies, and product portfolios, stakeholders need access to the full depth of data available in the Worldwide Polyolefin Antioxidants Market report. The complete study provides detailed segmentation analysis, specific regional revenue estimates, comprehensive company profiles, and scenario-based forecasting that goes beyond the macro narrative.
We invite industry leaders to explore the full findings to equip their teams with the precise intelligence needed to thrive in 2026 and beyond. Understanding the nuances of market concentration, regulatory impacts, and specific segment dynamics is the key to transforming uncertainty into strategic opportunity.
For detailed analysis of this topic, please visit the official page: Worldwide Polyolefin Antioxidants Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com