

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Domestic Appliances Market to Reach $1,059.51 Billion by 2032, Growing at 4.85% CAGR

Navigating the Next Wave: Strategic Intelligence for the Global Domestic Appliances Market
The worldwide domestic appliances sector stands at a critical inflection point. From shifting trade policies and raw material volatility to accelerating smart-home integration and evolving consumer replacement cycles, the operating environment demands more than surface-level market commentary. Decision-makers need a structured, data-grounded view of where value is being created, where margins are under pressure, and which competitive moves will separate leaders from laggards over the coming decade. Our newly released Worldwide Domestic Appliances Market research study delivers exactly that: a comprehensive strategic blueprint designed for executive teams, category managers, and corporate development professionals who must act on evidence rather than intuition.
Home Appliances Market
This article previews the analytical architecture, market sizing framework, competitive dynamics, and real-world industry developments embedded in the full report. It is designed to demonstrate the depth of our methodology and the practical utility of our findings while leaving the granular segmentation, regional breakdowns, and quantified investment modeling for the complete intelligence package. For organizations preparing capital allocation, product roadmap, and go-to-market decisions for 2026 and beyond, the complete dataset is essential reading.
A Market in Motion: Sizing, Trajectory, and Structural Shifts
Understanding the global domestic appliances market requires a disciplined look at both historical performance and forward-looking momentum. Our analysis traces the sector from 2020 through the base year of 2025, then extends a structured forecast window through 2032. Over the historical period, the market demonstrated resilient expansion, driven by post-pandemic housing activity, rising disposable incomes in key emerging economies, and accelerated upgrades in residential appliance fleets. Revenue measurements across this timeframe show a clear upward trajectory, with the global market surpassing the half-trillion mark and continuing to scale toward new highs as household modernization and replacement demand compound across regions.
Looking ahead, the forecast period captures a market expected to grow at a compound annual growth rate of 4.85 percent. This figure is not a blunt average but a synthesized outcome of divergent regional maturity curves, product-category performance, and channel migration patterns. Our modeling reflects how macroeconomic conditions, housing turnover, and consumer willingness to invest in premium or smart-enabled features will interact with supply-side constraints, logistics costs, and trade policy shifts. The result is a nuanced growth path that accounts for periods of acceleration alongside segments where saturation and replacement-cycle lengthening moderate expansion.
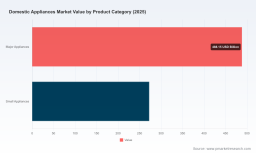
Importantly, the report does not treat growth as monolithic. Revenue expansion is being shaped by the interplay of major and small appliances, multi-brand retailing versus direct-to-consumer and online channels, and the geographic weight of Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa. Each of these structural vectors carries different margin profiles, competitive intensity, and risk exposure. The full publication unpacks these layers with quantified contributions, year-by-year projections, and scenario analysis, but the headline takeaway for strategic planning is clear: growth is real, yet it is unevenly distributed and increasingly contingent on how well companies align product portfolios, pricing strategies, and distribution footprints with local demand economics.
Market structure also informs competitive behavior. Our analysis incorporates market concentration metrics that highlight the share held by leading firms. A CR3 near twenty-eight and a half percent and a CR5 in the low forty-two percent range indicate a landscape where scale players command meaningful presence without fully dominating every sub-segment or geography. This concentration profile has strategic implications: it suggests room for specialist and regional brands to compete effectively in attractive niches, while larger multinationals leverage brand portfolios, manufacturing scale, and global supply networks to defend share and pursue premiumization. For investors and corporate strategists, concentration dynamics are a vital input into M&A screening, partnership evaluation, and offensive or defensive market entry decisions.
Competitive Architecture: Who Sets the Pace and How
The domestic appliances ecosystem is anchored by a set of globally capable manufacturers whose strategies shape pricing, innovation cadence, and consumer expectations. Our report profiles a cross-section of these organizations, capturing their headquarters, brand portfolios, geographic strengths, and strategic emphasis.
Haier Smart Home Co., Ltd., operating from Qingdao, has built a broad global footprint by integrating flagship, acquired, and regional brands across refrigerators, washing machines, air conditioners, and cooking appliances. Its strategy emphasizes smart and energy-efficient solutions, positioning the company to compete across value and premium tiers while leveraging a multi-brand architecture to address distinct market segments. Whirlpool Corporation, based in Benton Harbor, Michigan, remains a leading manufacturer of major domestic appliances with a deep North American footprint and a global brand portfolio that includes Whirlpool, Maytag, and KitchenAid. Its strength in refrigerators, washers, dryers, dishwashers, and ovens makes it a bellwether for major-appliance demand and pricing dynamics in mature markets.
From East Asia, LG Electronics and Samsung Electronics both offer wide-ranging appliance lines that increasingly converge on smart connectivity, AI features, and energy efficiency. LG’s portfolio spans refrigerators, washing machines, dishwashers, and air conditioners, with a clear emphasis on connected functionality and efficiency gains. Samsung complements this with a comprehensive lineup that includes smart refrigerators, washers, dryers, ovens, and air conditioners, differentiating through Bespoke customization and AI-powered technologies that target consumers seeking personalization alongside performance. These two players illustrate how product design, software integration, and brand positioning can be used to capture share in increasingly discerning consumer markets.
Electrolux AB, headquartered in Stockholm, operates as a global producer of both major and small domestic appliances under the Electrolux and Frigidaire brands, with a pronounced emphasis on sustainability across cookers, washing machines, dishwashers, and vacuum cleaners. BSH Hausgeräte GmbH, the Bosch-Siemens home appliance entity based in Munich, anchors European premium demand with Bosch and Siemens brands, covering cooking, laundry, dishwashing, and refrigeration while prioritizing quality and innovation. Midea Group, from Foshan, is a large-scale manufacturer with significant export volume, covering air conditioners, refrigerators, washing machines, and small kitchen appliances, and it continues to expand its international reach. Panasonic, operating from Kadoma, widens the field with refrigerators, washing machines, microwaves, and air conditioners, emphasizing health, wellness, and energy-saving features. Arçelik A.Ş., based in Istanbul, is a major producer of white goods under Beko, Grundig, and other brands, with particular strength in Europe and emerging markets. Hisense, also headquartered in Qingdao, competes on affordability across refrigerators, washing machines, TVs, and air conditioners while growing its global share. Miele & Cie. KG, in Gütersloh, occupies the high-end niche with a reputation for durability and performance in washing machines, dishwashers, ovens, and vacuum cleaners. Finally, Gree Electric Appliances, from Zhuhai, remains a leading producer of air conditioners and other climate-control appliances, wielding substantial worldwide production capacity.
These profiles are not static corporate snapshots. Each organization is navigating a different combination of input cost pressures, regulatory exposure, channel shifts, and technology roadmaps. The report examines how their strategies intersect with market concentration, regional demand profiles, and product-category growth rates, helping readers identify which competitors are likely to gain share in which segments and why. The full document layers in quantified competitive positioning and movement analysis, enabling sharper benchmarking and more credible scenario planning.
Industry Dynamics in Real Time: Regulation, Materials, and Consumer Behavior
A market study gains its value when it connects structural data to the forces actively reshaping operations and demand. Several recent developments illustrate how quickly the domestic appliances landscape can shift and why forward-looking intelligence is indispensable.
Trade policy has become a first-order variable. In June 2025, the United States increased Section 232 tariffs on steel and aluminum imports to 50 percent, with subsequent expansions affecting steel content in imported appliances such as refrigerators, washers, dryers, dishwashers, and ovens. For manufacturers and retailers, this change alters landed costs, sourcing strategies, and end-price positioning. Public statements from major industry participants have indicated that steel tariffs and related measures can materially raise input costs, with estimates that new tariffs could increase retail prices of affected imported appliances by $50 to $70. These dynamics do not simply compress margins; they also influence consumer affordability, cross-border sourcing decisions, and the relative competitiveness of domestic versus imported product lines.
At the same time, regulatory conversations around appliance energy sources are evolving. Ongoing discussions by U.S. municipal, state, and federal regulators regarding potential new regulations or bans on natural gas appliances, citing climate concerns, could reshape product mix and transition costs for manufacturers. Even where final rules remain under debate, the uncertainty alone affects portfolio planning, engineering investments, and go-to-market messaging. Companies that anticipate these shifts can prepare alternative product architectures and channel strategies well ahead of enforceable deadlines, while laggards risk stranded development spend and reactive repositioning.
Consumer behavior is also being redefined by practical considerations rather than abstract trends. In North America, early replacement cycles are expected for dishwashers, refrigerators, and air conditioners amid moderate growth projections, with emphasis on energy savings and convenience features. This pattern signals a market where renewal is being driven by functional payoff—lower operating costs, smarter controls, and improved reliability—rather than by discretionary upgrade alone. Meanwhile, broader market outlooks for 2026 point to flat to modest growth in major domestic appliances and small domestic appliances, underscoring the importance of replacement timing, product mix, and promotional strategy in mature markets.
On the innovation and showcase front, events such as IFA and AWE continue to function as barometers of product direction and brand ambition. Exhibitions have highlighted handheld cleaning devices, robotic mopping and window-cleaning systems, and a broader theme of humanizing technology in household appliances. These showcases reflect an industry moving beyond core mechanical performance toward integrated convenience, automation, and user experience. Preparations for major appliance fairs in 2026 indicate sustained momentum in smart-home appliances and consumer electronics convergence, with new product launches and forums designed to shape consumer expectations and vendor partnerships. For strategists, such events are not merely promotional; they are leading indicators of feature prioritization, design language, and competitive differentiation in the next product cycle.
What the Full Study Delivers: Operational Intelligence for 2026 Decisions
A strategic research report is only as useful as the decisions it enables. Our Worldwide Domestic Appliances Market study is built around actionable outputs rather than retrospective summaries. It provides a detailed segmentation framework that breaks down revenue by region and by product category, allowing users to isolate the markets and categories most relevant to their portfolios. The report maps distribution channels—including multi-brand stores, online retail, and specialty stores—so that commercial teams can evaluate where demand is concentrating and how channel economics differ across product types and geographies.
Beyond segmentation, the study delivers quantified market sizing across historical and forecast periods, scenario-aware growth trajectories, and concentration analysis that grounds competitive benchmarking in measurable share dynamics. It connects these market structures to the strategic profiles of leading manufacturers, giving readers a clear line of sight from macro demand conditions to individual company positioning. This integrated design supports a wide range of decisions: entry and expansion prioritization, pricing and promotional calibration, product roadmap alignment, sourcing and tariff mitigation planning, and M&A or partnership screening.
Critically, the full publication also integrates the operational implications of regulation, raw material costs, and consumer replacement behavior into the analytical framework. Rather than treating these as separate overlays, the report weaves them into the market outlook so that strategic recommendations reflect both opportunity and constraint. This is what transforms data into decision support: a consolidated view that shows not only how large the market is and where it is heading, but also what will determine profitability and share outcomes along the way.
Worldwide Domestic Appliances Market
Why This Research Matters Now
The domestic appliances market in 2026 is not a passive backdrop for corporate strategy. It is a dynamic environment where trade policy, input costs, regulatory trajectories, and consumer replacement behavior interact with product innovation and channel evolution. In such a landscape, organizations that rely on lagged data or fragmented sources risk misjudging demand timing, margin exposure, and competitive threat. A structured, forward-looking research asset reduces that uncertainty and provides a common factual foundation for cross-functional planning.
Our study is designed to serve exactly that function. It offers the scale and rigor required for enterprise-level decisions while preserving the granularity needed for category, regional, and channel-level action. By integrating historical performance, forecast momentum, segmentation splits, concentration metrics, competitor profiles, and current industry developments, it creates a single reference point for market intelligence. For leaders preparing investments, product launches, pricing frameworks, and supply strategies for the 2026 to 2032 horizon, this depth is not optional—it is foundational.
The preview above outlines the strategic logic, market structure, competitive landscape, and live industry forces that define the sector. The complete Worldwide Domestic Appliances Market research report contains the detailed regional and product-category breakdowns, quantified forecast tables, channel-level analysis, concentration calculations, and competitive movement mapping needed to operationalize these insights. To access the full dataset and integrate it directly into your 2026 decision process, review the complete Worldwide Domestic Appliances Market market research study and its accompanying intelligence package.
For detailed analysis of this topic, please visit the official page: Worldwide Domestic Appliances Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com