

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Candy Displays Market to Hit $666.88M by 2032, Growing at 4.2% CAGR

The Candy Displays Market in 2026: Strategic Intelligence for Retail Merchandising Decision-Makers
From Shelf Impact to Supply Chain Resilience: Why the 2026 Landscape Demands Precision Planning
The candy and confectionery aisle has evolved far beyond passive shelving. In 2026, point-of-sale merchandising is a strategic lever for brand differentiation, basket building, and operational efficiency. The candy displays market reflects this transformation, with total industry revenue reaching approximately 500.00 million USD in 2025 and climbing to an estimated 520.38 million USD in 2026. Over the 2026-2032 forecast period, the market is projected to grow at a compound annual growth rate of 4.2 percent, culminating in a valuation that underscores sustained capital deployment across retail fixtures, custom POP solutions, and next-generation display architectures.
For executives navigating procurement, category management, facility design, and brand partnerships, these figures are only the starting point. The real strategic value lies in understanding how material selection, end-user behavior, regional demand patterns, competitive positioning, and regulatory pressures interact to shape total cost of ownership and in-store performance. Our latest Candy Displays Market research report distills this complexity into an actionable decision framework. It is designed not as a static data sheet, but as a working intelligence asset for merchandising directors, supply chain leaders, private-label strategists, and retail expansion teams who must allocate budget with precision while anticipating structural shifts in packaging, sustainability, and consumer engagement.
Candy Displays Market
This article previews the analytical depth of the full study. It highlights the market trajectory, the operational dimensions covered in the report, the competitive forces reshaping supply, and the regulatory and materials dynamics that will influence sourcing strategies through the end of the decade. As always, the detailed segmentation tables, proprietary forecasts, and company-by-company benchmarks remain exclusive to the report, where they are presented in formats built for boardroom discussion and category-level planning.
The Trajectory: Reading the Numbers as a Strategic Signal, Not Just a Trend Line
Market growth is rarely linear, and the candy displays segment is no exception. Historical data from 2020 through 2025 reveals a pattern of recovery, consolidation, and selective acceleration. Total revenue moved from 412.35 million USD in 2020 to 438.27 million USD in 2021, experienced a short-term correction to 431.50 million USD in 2022, and then resumed a steadier climb through 2023, 2024, and 2025. This trajectory signals more than post-pandemic normalization. It reflects structural demand for higher-performing merchandising assets, the expansion of impulse-driven formats, and a broader retail shift toward experiential, visually optimized confectionery zones.
The forecast period from 2026 to 2032 extends this logic. Growth compounds steadily as retailers and manufacturers invest in displays that do more than hold product. They guide purchase decisions, support promotional architecture, and adapt to changing store footprints. The compound annual growth rate of 4.2 percent may appear measured, but in a mature segment it indicates durable demand rather than speculative hype. For decision-makers, the implication is clear: incremental budget increases must be paired with smarter specification choices, because the efficiency of each display asset now matters as much as the total spend.
This report treats the numbers as a foundation for scenario planning. It maps how demand indices connect to material preferences, store formats, and regional expansion priorities, enabling teams to pressure-test assumptions rather than accept headline figures at face value. The goal is to help organizations align display investments with broader commercial objectives, whether those involve premiumization, cost containment, faster seasonal turnarounds, or omnichannel consistency.
What the Report Delivers: A Working Toolkit for Merchandising, Sourcing, and Capital Allocation
The study is built around practical application. Instead of stopping at top-line forecasts, it walks through the operational dimensions that determine how display investments perform in real retail environments. The report examines the market along multiple decision-critical axes, including material choices, end-user adoption patterns, and regional demand variation, while integrating supplier capability profiles and recent industry developments. Each section is structured to support concrete actions: specification benchmarking, sourcing strategy refinement, retail format alignment, and risk assessment.
Material analysis is central to this framework. Different substrates create different tradeoffs across durability, aesthetics, weight, lead time, and sustainability compliance. The report evaluates how acrylic, metal, wood and cardboard, and glass each fit into specific merchandising contexts, without reducing the discussion to simplistic cost comparisons. Instead, it considers where each material performs best in terms of shelf impact, maintenance burden, recyclability pathways, and compatibility with automated or modular fixtures. For procurement teams, this means clearer criteria for selecting display families that align with store conditions, brand guidelines, and total lifecycle cost.
End-user analysis adds another layer of operational relevance. The report assesses how major retail channels approach candy displays, from high-throughput environments where speed, density, and ease of replenishment matter most, to specialty settings where presentation quality, brand storytelling, and tactile customer experience take priority. It also examines convenience-oriented formats and other emerging channels that require compact footprints, flexible merchandising, and rapid seasonal adaptation. By connecting channel behavior to display requirements, the study helps teams avoid the common mistake of applying a single fixture strategy across dissimilar retail settings.
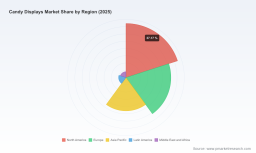
Regional analysis is presented with the same decision-oriented logic. Rather than treating geography as a set of disconnected numbers, the report interprets regional variation as a reflection of retail maturity, store expansion dynamics, local sourcing feasibility, and regulatory exposure. This approach supports more realistic market-entry evaluations, distribution planning, and partner selection for organizations operating across multiple territories or considering cross-border sourcing strategies.
Beyond the structural breakdowns, the report integrates recent market activities that signal where the industry is heading. It references high-visibility events such as the 2026 Sweets & Snacks Expo in Las Vegas, where more than 1,000 exhibitors showcased candy displays, merchandising innovations, and packaging developments. It also tracks product-level observations, including dual-brand display towers seen in retail settings, the release of creative POP strategies aimed at boosting retail sales, and ongoing deployment of modular, robot-built merchandising displays by major manufacturers. These developments are not included as isolated news items. They are used as indicators of broader shifts in customization, automation, co-branding, and retail readiness.
The report also embeds macroeconomic and regulatory context into its analysis. Materials pricing signals, including recent movements in plastics packaging and containerboard costs, are discussed as variables that affect fixture economics and sourcing timing. Regulatory developments, such as extended producer responsibility initiatives across multiple U.S. states and packaging reduction mandates with 2032 targets, are framed as strategic considerations that influence material selection, supplier qualification, and long-term compliance planning. In short, the report treats display purchasing as a decision that sits at the intersection of design, operations, sustainability, and risk management.
Competitive Dynamics: A Fragmented Field Shaped by Specialization and Innovation
The candy displays market remains notably fragmented. Concentration metrics show that the top three firms account for roughly 28.5 percent of market share, while the top five firms reach approximately 35.8 percent. This structure matters for strategy. It indicates that no single participant dominates the category, that regional and functional specialization continue to create viable competitive positions, and that buyers can benefit from diversified sourcing relationships if they evaluate suppliers against the right criteria.
The competitive landscape includes a mix of specialized display manufacturers, packaging-oriented design firms, and major confectionery producers with in-house merchandising capabilities. Several U.S.-based companies emphasize specialized candy retail fixtures, acrylic bins, countertop and floor displays, hinged containers, dispensers, LED-enhanced racks, and custom store solutions. Their positioning often centers on merchandising precision, speed of deployment, and channel-specific design expertise. At the same time, leading Chinese manufacturers contribute strong capabilities in custom display stands, POP structures, cardboard and metal fixtures, multi-tier shelving, and scalable retail interior solutions. Their role in the market highlights the importance of evaluating supplier base geography not only for cost, but also for design flexibility, production capacity, and compliance alignment.
What distinguishes the current competitive environment is the growing overlap between display manufacturing and broader merchandising innovation. Some vendors focus on modular, customizable systems that can be reconfigured for promotional calendars or seasonal assortments. Others emphasize integrated solutions that combine structural design with brand activation, such as dual-brand installations or co-developed fixtures for retail partners. The report examines these differences in detail, mapping company profiles to the capabilities that matter most for procurement and category strategy. Rather than presenting a simple vendor directory, it interprets each participant through the lens of operational fit: what they build well, what channels they serve, where they are likely to add value, and where limitations may arise depending on the buyer’s priorities.
Recent developments reinforce the idea that competition is increasingly expressed through execution speed and design responsiveness. Creative POP strategies, custom display concepts, and robotics-informed merchandising programs all point to a market in which differentiation is tied to adaptability. For retailers and brands, the strategic question is no longer whether to invest in candy displays, but how to select partners and specifications that can keep pace with changing promotional cycles, store layouts, and consumer expectations. The report provides a comparative lens for answering that question without relying on generic vendor claims.
Regulatory and Materials Signals: Why Sourcing Strategy Must Be Forward-Looking
One of the most valuable contributions of the research is its integration of supply-side and regulatory signals into the market narrative. Candy displays do not exist in a vacuum. They are affected by resin pricing, packaging material volatility, state-level sustainability mandates, and evolving expectations around end-of-life responsibility. As of 2026, these forces are becoming more than background conditions; they are increasingly decisive in specification and sourcing decisions.
Materials data offers a clear example. Recent producer price indicators for plastics packaging products and plastics material and resins manufacturing show elevated levels that can influence the cost structure of acrylic and other resin-based display components. At the same time, containerboard price volatility has introduced uncertainty for cardboard-based solutions. For procurement teams, this means that material decisions cannot be optimized solely on upfront unit cost. They must account for price swings, lead-time variability, and the possibility that a seemingly economical choice today may carry higher exposure tomorrow. The report translates these dynamics into procurement-relevant guidance, helping buyers assess which material families offer the best balance of performance and cost stability under different sourcing scenarios.
On the regulatory side, the growing patchwork of extended producer responsibility laws across multiple U.S. states adds complexity to display design and packaging choices. Requirements affecting plastics and paper-based materials are increasingly shaping what can be used, how it is disposed or recycled, and what documentation suppliers must support. In parallel, high-profile packaging mandates with 2032 targets are accelerating attention on recyclability, compostability, and material reduction for single-use applications. For candy displays, these trends have direct implications. They influence substrate selection, supplier qualification, and the durability-versus-sustainability balance that many merchandising teams now need to manage.
The strategic takeaway is that compliance and sourcing strategy should be integrated early, not retrofitted after specifications are finalized. The report addresses this by framing regulatory exposure as part of the decision matrix alongside cost, aesthetics, functionality, and lead time. This is especially important for organizations operating in multiple jurisdictions or considering long-term display programs where regulatory drift could affect total program economics.
Why the Full Study Matters for 2026 Decision-Making
A top-line forecast can confirm that the candy displays market is expanding, but it cannot tell a merchandising director which display family deserves budget priority, nor can it help a sourcing leader evaluate whether a given supplier’s capabilities match a new retail format. That is the gap this research is designed to close. The full study provides the granularity required to make informed choices across material selection, channel alignment, regional planning, and supplier evaluation.
For companies planning 2026 and beyond, the report supports several concrete decisions. It helps teams forecast demand with greater confidence by placing the 2026-2032 trajectory in the context of historical variability and current industry momentum. It aids specification decisions by comparing material families within the operational realities of different retail settings. It informs sourcing strategies by interpreting competitive fragmentation, supplier profiles, and recent innovation signals in a way that supports partner selection rather than ad hoc purchasing. And it strengthens risk planning by embedding materials cost behavior and regulatory developments into the same analysis as demand growth.
The report is also structured to support internal alignment. Because it moves from market structure to competitive dynamics to operational risks, it gives cross-functional teams a shared reference point. Category managers, procurement leaders, finance stakeholders, and sustainability teams can all use the same intelligence base, each through the lens most relevant to their responsibilities. That shared context is often the difference between fragmented purchasing decisions and a coherent display strategy.
Worldwide Home Display Case Market
Conclusion: Turn Market Momentum into Disciplined Execution
The candy displays market is entering a phase in which growth is supported not only by demand, but by continuous innovation in materials, design, and merchandising execution. The combination of steady projection, fragmented competition, and intensifying materials and regulatory pressures makes this a landscape where informed judgment outperforms intuitive procurement. Our upcoming research report is built for that environment. It offers the strategic scaffolding needed to interpret the market, evaluate suppliers, and plan display investments with discipline.
The detailed segmentation analysis, proprietary company assessments, and forward-looking scenario frameworks are reserved for the full report. Readers seeking a complete view of the candy displays market for 2026 decision-making are encouraged to access the source page, where the full intelligence package is available for download and review.
For detailed analysis of this topic, please visit the official page: Candy Displays Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com