

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecast: Maritime Missile Launch System Market Poised to Expand at a 7.12% CAGR Through 2032
By pmarketresearch, 2026-07-06
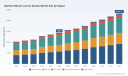
Maritime Missile Launch System Market 2026: Strategic Preview for Decision‑Makers
Executive snapshot
As geopolitical uncertainty and naval modernization programs accelerate, maritime missile launch systems have moved from niche capability purchases to core fleet-planning priorities. PW Consulting’s new Maritime Missile Launch System Market report—anchored on a 2025 base year—quantifies that shift. The global market expanded from roughly USD 10.3 billion in 2020 to an estimated USD 14.35 billion in 2025, and is projected to grow to about USD 15.66 billion in 2026, continuing at a compound annual growth rate (CAGR) of 7.12% through the 2026–2032 forecast window, reaching an anticipated USD 23.22 billion by 2032.
Maritime Missile Launch System Market
This press release outlines the report’s strategic value for enterprise and public‑sector decision-makers preparing procurement, R&D, M&A, and industrial policy actions in 2026. It presents high‑level takeaways and actionable implications while preserving the granular segmentation and proprietary models that constitute the report’s core—available through the full report portal.
Maritime Missile Launch System Market
Why this matters for 2026 planning
-
Momentum and scale: The market’s steady mid‑single‑digit CAGR masks heterogeneous pockets of demand and technology differentiation—factors that will determine winners and losers in upcoming procurement cycles. For strategic planners, the headline growth converts to expanded budgets and stretched supply chains that require proactive management.
Maritime Missile Launch System Market -
Concentration and competitive dynamics: Market concentration is material—our analysis shows the top three incumbent groups capture over 60% of market revenue, and the top five approach nearly 79%. This concentration underwrites predictable supplier behavior but raises acquisition and substitution costs for buyers exploring vendor diversification.
-
Timing is critical: 2026 represents an inflection year where near‑term deliveries, upgrade contracts, and interoperability initiatives (notably accelerated under recent alliance arrangements) will lock in platform capabilities for the next decade. Companies that align R&D pacing, supply chain agreements, and partner networks to those delivery pipelines will secure differentiated runway.
What the full report delivers (practical, usable outputs)
-
Investment-grade market model: A calibrated topline forecast with scenario variants (baseline, accelerated‑procurement, constrained‑supply) and sensitivity analyses tuned to commodity swings, export controls, and alliance‑driven procurement uplifts.
-
Procurement pipeline and timing map: Program schedules and decision‑points for shipyards, navies and prime integrators that help planning teams prioritize bids, capacity investments, and offset negotiations across 2026–2032.
-
Competitive playbooks: Vendor‑level benchmarking (technology footprint, integration capability, program backlog, partner ecosystem), win/loss archetypes and go‑to‑market motions tailored to primes, subsystem suppliers and emerging challengers.
-
Supply‑chain stress tests: Component‑level risk modelling, including raw‑material exposure, single‑sourcing vulnerabilities, and time‑to‑certification overlays, with recommended mitigation steps and contract language to protect schedules and margins.
-
Regulatory and export roadmaps: Practical guidance for navigating export control regimes, offset regimes and alliance interoperability standards—complete with decision trees that operational teams can use when evaluating cross‑border partnerships in 2026.
-
Actionable M&A and partnership diagnostics: Criteria‑based screens to evaluate target attractiveness, integration risk, and synergies—backed by valuation sensitivities linked to program backlog and expected procurement cycles.
Competitive landscape—what the incumbents are doing and what it means
The market is dominated by an ecosystem of established primes with deep systems integration capabilities. Key players include BAE Systems, Lockheed Martin, Raytheon Technologies (RTX), MBDA, Naval Group, Leonardo, Thales Group and Saab—each bringing differentiated technology stacks and program footprints. Recent program movements highlight tactical shifts that matter to 2026 decisions:
-
Lockheed Martin completed delivery of VLS modules for a major destroyer program in late 2025, reinforcing its delivery credibility and near‑term revenue base.
-
BAE Systems secured an upgrade contract for allied destroyers in 2025, a signal that lifecycle upgrade markets will be a substantial addressable opportunity alongside new‑build orders.
-
MBDA’s showcase of VLS upgrades and Naval Group’s recent frigate launch illustrate active modernization programs in Europe—relevant for suppliers assessing platform integration demand and aftermarket growth.
For buyers and suppliers, these developments underline two strategic imperatives: first, align product roadmaps to integration requirements of platform primes and national navies; second, anticipate aftermarket and upgrade pipelines that can sustain margins beyond initial system supply.
Supply chain, materials and regulatory headwinds
Our industry monitoring shows three cross‑cutting dynamics that will shape procurement and production strategies in 2026:
-
Raw‑material volatility: Specialized high‑strength steels used in launch canisters have experienced price and availability shocks—our sources show recent double‑digit pressure points in specific supply lines. This requires buyers to embed material escalation clauses or to co‑invest in assured supply capacity.
-
Export controls and certification complexity: ITAR and comparable regimes continue to constrain transfers of key launch system technologies, limiting partnership options in several geographies. The net effect is longer lead times for cross‑border integrations and elevated compliance costs that must be budgeted into program proposals.
-
Geopolitical procurement drivers: Heightened Indo‑Pacific tensions and recent alliance initiatives have directly lifted procurement allocations in key partner navies, accelerating interoperability standards and creating windows of opportunity for suppliers that can certify cross‑ally compatibility rapidly.
Strategic recommendations for 2026 decision windows
-
For primes and system integrators: Prioritize interoperability and modularity. Invest incrementally in common interfaces and testbeds that reduce integration cost for allied navies; this is a multiplier effect in markets where alliance procurement is accelerating.
-
For component and materials suppliers: Lock in long‑lead raw‑material contracts and qualify alternate sources now. Where feasible, offer fixed‑price frameworks tied to verified supplier cohorts to improve predictability for integrators.
-
For private‑equity and strategic buyers: Focus on targets that bring niche technical differentiation (e.g., thermal management, canister life‑extension, single‑cell modularity) and proven pathway to prime certifications; these attributes command premium entry into long lifecycle upgrade markets.
-
For defense procurement authorities: Include lifecycle cost and upgradeability metrics in new‑build RFPs. Contestable upgrade clauses and shared‑risk development can unlock innovation while preserving sovereign access.
Use cases: Rapid decisions enabled by the report
Three example scenarios where the report is directly actionable for 2026 decisions:
-
A prime preparing a bid for a 2026 destroyer modernization can use our pipeline timing map to align margin commitments and supplier contracts to phased delivery milestones—reducing cost overruns and improving proposal hit‑rates.
-
An intermediate supplier can deploy our supply‑chain stress tests to quantify the benefit of vertical integration into critical alloy supply, and to build a business case for capex in 2026 that shortens lead times for key components.
-
An alliance procurement office can use the regulatory roadmaps and interoperability matrices to fast‑track certification strategies that preserve sovereign control while enabling allied logistics chains.
What we withhold here—and how to get it
Consistent with our “trailer” approach, this release highlights the analytical framework, strategic implications and executable recommendations that make the report a practical decision tool for 2026. To preserve the integrity of the commercial models and proprietary segmentation that buyers rely on, we have not published the detailed region‑by‑region or application‑level splits in this summary. The full report contains the granular segment tables, vendor share matrices, program‑level revenue schedules and downloadable models that support procurement and investment decisions.
Next steps
For immediate access to the complete dataset, scenario models and the vendor playbooks that underpin our recommendations, please download the full Maritime Missile Launch System Market report from the PW Consulting portal. The report is structured to be operational—from one‑page executive summaries for boardrooms to detailed, cell‑level models for program managers and M&A teams.
In a market where timing, supply assurance and interoperability will determine strategic positioning over the next decade, this report is designed to convert market intelligence into executable advantage in 2026.
For detailed analysis of this topic, please visit the official page: Maritime Missile Launch System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Household Solid-State Relay Market to Expand at a 7.66% CAGR, Fueling Smart Home Power-Control Growth
By pmarketresearch, 2026-07-06
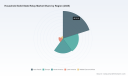
Household Solid State Relay Market: Strategic Imperatives for 2026 — PW Consulting Executive Brief
As households worldwide accelerate their adoption of smarter, quieter and more energy-efficient electrical systems, solid state relays (SSRs) have transitioned from niche components to strategic enablers across appliances, lighting and HVAC control. PW Consulting’s latest Household Solid State Relay Market report (base year 2025; historical coverage 2020–2025; forecast 2026–2032) frames the market opportunity and risk landscape that corporate leaders must incorporate into 2026 strategic planning cycles.
Household Solid State Relay Market
Why this market matters now
Between 2020 and 2025 the household SSR market expanded materially — rising from approximately USD 305 million to USD 430 million — reflecting a convergence of product-level drivers (noise-free switching, longer service life, miniaturization) and system-level trends (smart home integration, electrification of household functions, tighter energy-efficiency standards). Our forecast shows the market continuing to expand to roughly USD 721 million by 2032, representing a 7.66% compound annual growth rate across the 2026–2032 forecast horizon. That trajectory positions SSRs as a high-priority component class for OEMs, component suppliers and integrators focused on household electrification and energy management.
Household Solid State Relay Market
What PW Consulting’s report delivers (actionable, operational intelligence)
- Strategic market sizing and trend narratives that translate macro growth into product and program priorities for 2026.
- Competitive value-mapping and supplier scorecards that evaluate performance across technology, thermal management, form factor and compliance risk (no proprietary split data published here — full scorecards are available in the report).
- Supply chain stress tests and scenario planning tools that model tariff shocks, raw-material constrictions and licensing controls, and quantify tactical hedges (inventory, dual-sourcing, nearshoring).
- Go-to-market playbooks for appliance OEMs, smart-home platform providers and electrical distributors to accelerate design-ins — including reference design checklists and BOQ (bill-of-material) rationalization frameworks.
- M&A and partnership roadmaps identifying capability adjacencies (thermal subsystems, integrated power modules, embedded sensing) most likely to deliver differentiation in household use-cases.
- Regulatory tracker and compliance templates to operationalize responses to export controls, tariffs and critical-minerals policy moves.
Competitive landscape — who matters and why
The household SSR market is neither hyper-consolidated nor atomized: the top three vendors account for a meaningful share of the market while the top five approach half of sector revenues — a structure that favours both scale players and specialized innovators. This mixed concentration profile creates space for strategic plays across pricing, product differentiation and channel partnerships.
Household Solid State Relay Market
- Omron Corporation (Kyoto, Japan) — A broad product portfolio spanning compact PCB-mount and panel-mount SSRs. Omron is particularly relevant for appliance manufacturers seeking proven temperature-control and small-load switching building blocks.
- Panasonic Corporation (Osaka, Japan) — Strong in optoelectronic PhotoMOS and low-power SSRs; a natural partner for consumer-electronics routes-to-market where silent switching and space-constrained PCB footprints matter.
- Carlo Gavazzi Holding AG (Steinhausen, Switzerland) — Offers rugged DIN-rail and panel-mount devices tailored to building automation and HVAC, including integrated thermal management solutions for higher continuous loads.
- Sensata Technologies (Crydom) (Attleboro, USA) — Industrial-grade SSRs with features like zero-cross switching; attractive to OEMs that require high reliability and low noise in residential environments.
- Schneider Electric SE (Rueil-Malmaison, France) and Siemens AG (Munich, Germany) — Each brings modular systems and integration pathways into smart-home and building-management ecosystems, prioritizing interoperability and serviceability.
- ABB Ltd , TE Connectivity , Vishay Intertechnology , Littelfuse , Celduc Relais and Fujitsu — These suppliers together span the landscape from high-cycle, vibration-tolerant components to compact, low-power PCB SSRs for consumer devices, enabling a spectrum of differentiation strategies for OEMs.
Recent vendor activity underscores the pace of product and go-to-market evolution. Notable examples include Sensata’s fourth-generation SSRs (2025) with improved thermal performance and electrical isolation, Omron’s 2025 showcases of AC/DC high-power solid state relay variants for renewable and control applications, and multiple Chinese manufacturers exhibiting advanced SSR solutions at trade events in early 2026. These moves point to intensifying competition on thermal design, reliability, and application-specific packaging.
Supply chain and policy dynamics that will shape 2026 decisions
Two interlinked structural issues require board- and C-suite attention:
- Raw-material concentration risk — Production of key inputs for optocouplers and power semiconductors is regionally concentrated. For example, low-purity primary gallium production is highly centralized, creating single-point-of-failure exposure for certain SSR components used in household devices.
- Policy and tariff volatility — Policy shifts are already increasing landed costs and complicating sourcing strategies. Measures such as elevated tariffs on semiconductor components and executive actions targeting processed critical minerals have introduced new operational constraints and compliance burdens for global supply chains.
Collectively, these factors increase the importance of proactive supply-chain design: dual-sourcing strategies, qualified alternate chemistries where feasible, longer lead-time hedges for critical components, and scenario-based cost modeling for procurement and pricing teams.
Key strategic moves for 2026 (prioritized)
- Prioritize supply resilience — Quantify exposure to concentrated raw-material sources in component BOMs; implement dual-qualification programs and strategic inventory thresholds for critical semiconductor inputs.
- Design for environmental and regulatory robustness — Accelerate product roadmaps emphasizing thermal efficiency, higher isolation voltages and compliance to anticipated import/export scrutiny; these attributes will ease customer adoption and reduce aftermarket risk.
- Segment product stacks — Rationalize portfolios into core, adjacent and experimental offerings. Allocate R&D and manufacturing dollars to form-factors and thermal solutions where unit economics and adoption curves are most favorable.
- Commercialize system-level value — Position SSRs not as discrete components but as modules within appliance and HVAC subsystems that deliver quieter operation, lower warranty costs and energy savings — this supports value-based pricing.
- Hunt partnerships and tuck-ins — Target acquisitions or JVs that add thermal management, power-module integration or embedded sensing; these capabilities shorten time-to-market for higher-value system modules.
- Operationalize regulatory intelligence — Implement a compliance dashboard to translate tariff scenarios and export-control developments into P&L-sensitive actions (e.g., re-routing, supplier renegotiation, localization).
How PW Consulting’s report supports implementation
Our report is structured to move decision-makers from insight to execution. Deliverables include:
- Board-level briefings and scenario decks built from our forecast and regulatory trackers.
- Supplier risk heatmaps and a prioritized mitigation playbook tailored to your BOM exposure.
- Technology comparison matrices that map vendor strengths to household use-cases and show gaps you can address via targeted R&D or procurement strategies.
- Commercial tools — negotiation playbooks, channel-entry templates and TCO models — that translate product capability into distributor and OEM contract terms.
Importantly, the report purposefully omits publishable granular splits for certain proprietary subsegments in this public brief. That detailed segmentation, full vendor scorecards, and the interactive scenario tools are included in the subscription package and online report portal for clients and authorized stakeholders.
Immediate next steps for executives
- Commission a rapid SSR exposure audit across product lines and suppliers during Q1–Q2 2026 to identify single-source risks and thermal margin deficits.
- Embed a two-tier sourcing policy for high-risk inputs with qualification timelines and decoupling triggers tied to policy events (tariff changes, export-control licensing updates).
- Revisit product roadmaps to prioritize SSR-enabled value propositions (silent operation, lower warranty exposures, reduced energy consumption) and align commercial messages to energy and smart-home integrators.
- Explore targeted M&A or partnership opportunities to close capability gaps in thermal systems, integrated power modules and sensing — PW Consulting’s report includes a short-list of candidate capabilities and archetypal acquisition metrics.
Concluding perspective
For manufacturers, suppliers and systems integrators operating in the household electrification space, solid state relays are more than a component category: they are a leverage point for product differentiation, operational resilience and new-value capture. With a market expanding from the low hundreds of millions in 2020 to an expected market approaching three-quarters of a billion USD by 2032, companies that pair product innovation with disciplined supply-chain and regulatory strategies will secure disproportionate advantage.
PW Consulting’s Household Solid State Relay Market report is designed to be the operational handbook for that transition — providing proprietary segmentation, vendor benchmarks, regulatory scenario models and commercial tools to inform 2026 strategy decisions. For access to the full dataset, interactive tools and tailored executive briefings, visit our report portal or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: Household Solid State Relay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Intelligent Warehouse Market to Soar from USD 35,637.43 Million in 2025 to USD 78,783 Million by 2032, Forecasting a 12.04% CAGR
By pmarketresearch, 2026-07-06
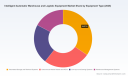
Intelligent Automatic Warehouse and Logistic Equipment Market 2026: Strategic Roadmap for Decision-Makers
Executive Preview
PW Consulting’s latest market study, Intelligent Automatic Warehouse and Logistic Equipment Market (base year 2025), arrives at a decisive moment for supply chain leaders and capital allocators. As the sector continues its double-digit ascent — growing from a global market of approximately USD 19.5 billion in 2020 to roughly USD 35.6 billion in 2025, and projected to expand at a compound annual growth rate (CAGR) of 12.04% across our 2026–2032 forecast horizon — 2026 will be the year when strategic choices made by C-suite teams crystallize into competitive differentiation or costly inertia.
Intelligent Automatic Warehouse And Logistic Equipment Market
Why this report matters to 2026 planning
-
Decision-grade synthesis: The study combines a multi-year historical base (2020–2025) with scenario-driven forecasts (2026–2032), translating broad market momentum into actionable signals for capital investment, procurement timing, and technology selection.
Intelligent Automatic Warehouse And Logistic Equipment Market -
Market structure clarity: Our analysis demonstrates that the market remains relatively fragmented (CR3 and CR5 metrics indicate limited top-tier concentration), creating both vendor choice complexity and opportunity for integrators and niche specialists to scale rapidly.
Intelligent Automatic Warehouse And Logistic Equipment Market -
Risk-adjusted planning: The report integrates cost-push factors (raw materials and tariffs), labor-cost dynamics, and regulatory/ESG pressures into a practical playbook for assessing project IRR, total cost of ownership (TCO), and operational resiliency.
High-level market trajectory
After an acceleration in adoption between 2020 and 2025, driven by e-commerce demand, labor constraints and the maturation of robotics and software, the intelligent automatic warehouse market is entering a consolidation phase in technology adoption. Our forecast anticipates continued robust expansion through 2032, underpinned by software-enabled automation, greater AMR/AGV deployment, and densification solutions that raise throughput per square foot. The sustained CAGR of 12.04% reflects both ongoing retrofit activity across legacy DCs and greenfield investments in high-growth regions and verticals.
Key demand drivers and headwinds
-
Labor substitution and productivity: Persistent labor shortages and rising wages are the primary proximate drivers for automation. Organizations are increasingly substituting capital for variable labor to stabilize fulfillment costs and service levels.
-
Technology maturation: Advances in AI, multi-agent orchestration, perception, and software-as-the-operating-layer are shifting procurement discussions from pure hardware toward integrated hardware-plus-software solutions.
-
Cost dynamics and supply-chain inflation: Raw material inflation — notably in steel and aluminum — and policy shifts such as increased tariffs have elevated project capital costs and extended vendor lead times. Buyers must now bake dynamic commodity and trade-risk scenarios into procurement timelines.
-
ESG and energy efficiency: Energy mandates and sustainability ambitions in developed markets are accelerating demand for regenerative drives, energy-optimized layouts, and lifecycle emissions transparency — all of which change the calculus for system selection and retrofit versus rebuild decisions.
-
Fragmented vendor landscape: A moderate level of market fragmentation creates negotiation leverage for informed buyers, but also increases integration risk if vendors’ software and control layers are not interoperable.
What the report contains (practical, operational content)
Designed for procurement officers, COOs, and investment committees, the study delivers hands-on tools and templates rather than academic generalities. Key deliverables include:
-
A calibrated market-sizing model and three scenario forecasts (base, upside, downside) with sensitivity to commodity, labor, and regulatory shocks.
-
Vendor benchmarking frameworks that evaluate end-to-end capabilities: hardware breadth, software maturity, integration experience, global delivery footprint, and lifecycle services.
-
Practical procurement playbooks: RFP templates, scoring matrices for technology vs. service trade-offs, and contracting guardrails to mitigate delivery and performance risk.
-
Implementation blueprints: Standardized timelines for greenfield and retrofit projects, prerequisites for warehouse digital twins, and phased roll-out approaches that protect fulfilment SLAs.
-
Financial tools: TCO calculators, payback and IRR scenarios, CAPEX-to-OPEX migration analyses, and maintenance-optimization strategies tuned to 2026 market conditions.
-
Actionable case studies and migration playbooks that map technology choices to specific operational KPIs (throughput, labor reduction, inventory accuracy, and energy consumption).
Competitive landscape — what buyers need to know
The ecosystem includes global integrators, robotics pure-plays, and specialized equipment manufacturers. Our strategic lens focuses on capability clusters rather than individual product claims, enabling buyers to align vendor selection with long-term platform strategy.
-
End-to-end integrators: Established systems houses with global delivery footprints are advantaged on large, high-throughput projects requiring tight mechanical, controls and software integration. Their strengths lie in turnkey project execution, proven engineering practices, and comprehensive service networks. Buyers considering mission-critical expansion or hub modernization will value these vendors’ ability to de-risk execution through scale and repeatability.
-
Robotics and AMR specialists: Innovators in mobile robotics and cube-based storage offer agility and rapid deployment for modular fulfillment environments. Their software-centric models enable flexible capacity scaling, and their product roadmaps increasingly prioritize multi-agent coordination and higher-level orchestration stacks.
-
Software-first challengers: A growing cohort emphasizes warehouse execution and orchestration software as the differentiation layer. These providers position themselves as neutral control layers capable of integrating best-of-breed mechanical subsystems — a model that appeals to buyers seeking vendor-agnosticity and future-proofing.
-
Regional and niche players: Local engineering houses and specialist OEMs continue to serve retrofit markets and specialized verticals where customized mechanical design and fast time-to-service are decisive.
Across these clusters, the 2026 purchasing decision will hinge on three vendor attributes: demonstrable integration experience, software maturity (including AI-based optimization), and lifecycle service economics. Our vendor profiles in the full report synthesize these attributes for leading suppliers across the ecosystem.
Recent industry signals and what they imply for 2026
-
Trade shows and forums (MODEX 2026 and Automate events) signaled consolidating themes: multi-agent AI, plug-and-play AMRs, and increased emphasis on software ecosystems. These product demonstrations suggest a shift from point-solution deployments to platform orchestration strategies.
-
Vendor technology updates highlighted investments in multi-agent systems for robot coordination — a trend indicating that performance gains will be captured through software-driven orchestration rather than incremental hardware upgrades alone.
-
Input-cost signals, including higher steel prices and trade-policy volatility, are compressing vendor margins and raising capital intensity. Buyers should expect longer lead times and consider inventory hedging or modular procurement to mitigate supply-side shocks.
Top strategic imperatives for 2026
-
Prioritize integration capability: Select partners with demonstrable multi-disciplinary project delivery and software interoperability to reduce vendor-switch and bespoke-integration risk.
-
Pursue staged deployments: De-risk large investments via modular rollouts that deliver early operational wins and allow iterative optimization of control software.
-
Embed commodity and policy scenarios into financial models: Include steel-price and tariff sensitivity in CAPEX planning and procurement cadence.
-
Optimize for energy and lifecycle cost: Given tightening ESG and energy-efficiency mandates, weight procurement decisions toward regenerative and energy-optimized solutions.
-
Lock in maintenance economics: Negotiate service-level guarantees and spare-parts agreements up front to stabilize OPEX and prevent post-deployment cost surprises.
Call to action
PW Consulting’s Intelligent Automatic Warehouse and Logistic Equipment Market report is structured to convert market intelligence into boardroom-ready actions. For procurement officers, operations leaders, and investors preparing 2026 budgets, the research offers a concise, risk-aware blueprint to navigate vendor choice, timing, and financing under persistent macro volatility.
To access the detailed segmentation, vendor profiles, case studies, and our interactive financial model — all withheld here to protect the strategic integrity of the full analysis — please visit our official report page for subscription and inquiry options. PW Consulting stands ready to support bespoke scenario workshops, vendor selection advisory, and implementation oversight to translate insight into measurable operational advantage.
For detailed analysis of this topic, please visit the official page: Intelligent Automatic Warehouse And Logistic Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Connecting Rod Bush Market to Rise from USD 642.5 Million (Base Year 2025) to USD 835.3 Million by 2032 at 3.82% CAGR — Asia Pacific, Bronze Bushings and Passenger Cars Drive Growth; Top 5 Hold 58.6%
By pmarketresearch, 2026-07-06
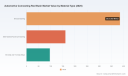
Automotive Connecting Rod Bush Market — Strategic Imperatives for 2026
PW Consulting today releases its latest industry brief on the Automotive Connecting Rod Bush market, anchored on a 2025 base year and covering historical performance (2020–2025) with a forward-looking forecast to 2032. Our analysis synthesizes engineering-level material science, supply-chain economics, regulatory change, and aftermarket dynamics into a pragmatic playbook for executives making strategic decisions in 2026. The market is exhibiting steady expansion — from approximately USD 595.6 Million in 2023 to USD 642.5 Million in 2025 — and is projected to continue growing at a compound annual growth rate (CAGR) of 3.82% through the forecast horizon, reaching an estimated USD 835.28 Million by 2032. This report is purpose-built to convert that trajectory into near-term choices that protect margin, preserve continuity, and create preferential positioning.
Automotive Connecting Rod Bush Market
Why this report matters for 2026 decision cycles
-
Sector-specific focus: Connecting rod bushings are small in unit size but pivotal in engine reliability and efficiency. As OEMs and Tier-1 suppliers wrestle with fuel-economy targets and lifecycle cost pressures, component-level improvements compound into measurable vehicle-level gains.
Automotive Connecting Rod Bush Market -
Timing: 2026 is a year of bifurcation — continued ICE volume in many markets coexists with accelerating electrification in others. Suppliers that align product, material, and aftermarket go-to-market strategies with nuanced regional and segment timelines will capture disproportionate value.
Automotive Connecting Rod Bush Market -
Actionability: Our deliverables include market-sizing, scenario-based forecasts, supplier benchmarking, and an executable checklist for product development, procurement, and M&A. The goal is to move leaders from strategic hypotheses to executable 12–36 month plans.
Macroeconomic and technical drivers
-
Engine efficiency and emissions regulation: Ongoing global fuel-efficiency and emissions standards continue to push internal combustion engine (ICE) manufacturers to reduce mechanical friction. Connecting rod bush designs that lower friction and improve durability contribute directly to meeting those standards — a persistent demand signal for advanced bimetal, bronze, and aluminum-alloy solutions.
-
Material science and manufacturing economics: The prevalent materials mix—steel-backed bronze, high-tin aluminum alloys and brass variants—remains driven by wear performance, thermal properties, and cost. Small changes in alloy composition or backing technologies can materially affect lifetime cost and reliability, which in turn influences OEM sourcing strategies.
-
Aftermarket and maintenance cycles: The aftermarket continues to be a significant revenue pool, particularly where regulatory actions or service bulletins require part replacement. Repair kits and replacement part portfolios have become strategic levers for suppliers to improve margins and customer stickiness.
-
Supply chain volatility: Raw material price swings and capacity constraints in precision casting and machining create supplier risk. Dual-sourcing strategies, local buffer inventories for critical alloys, and near-term investments in precision machining capacity are among the most effective mitigation measures.
Market structure and competitive posture
The market exhibits moderate concentration: the top three players account for a meaningful but not dominant share of the global market (CR3 ~42%), while the top five firms climb to a higher share (CR5 ~59%). This structure creates a landscape where global leaders set technology and quality benchmarks, but regional specialists and niche manufacturers retain the ability to win on cost, speed, or specific OEM program relationships.
-
Global OEM-focused leaders: Companies with deep OEM ties and broad engine-component portfolios continue to win program-level business by packaging connecting rod bushings with other bearings and engine components. Their advantages are design-in capability, validation cycles, and established quality systems.
-
Specialists and regional champions: Highly specialized manufacturers with IATF/ISO certifications and precision machining capabilities can undercut on lead time and customization, especially for legacy platforms, industrial engines, and regional OEMs.
-
Aftermarket players: Firms that combine catalog breadth with distribution reach and repair-kit offerings can monetize service cycles, regulatory-driven replacements, and fleet maintenance programs.
Competitive snapshot — what to watch from leading suppliers
-
MAHLE GmbH (Stuttgart, Germany): A global engine-components leader with strengths in low-friction designs and OEM integration. Strategic focus: maintain technology leadership in bearing metallurgy and system-level engine partnerships.
-
Federal-Mogul Motorparts / Tenneco (Southfield, MI, USA): Deep aftermarket channels plus OEM bi-metal and tri-metal technologies. Strategic focus: leverage aftermarket footprint to upsell performance or repair kits.
-
King Engine Bearings (Jerusalem/various manufacturing locations): Known for high-performance bearings and pin bushings rated for extreme loads. Strategic focus: motorsport, high-performance OEMs, and specialty diesel markets.
-
K1 Technologies (Ohio, USA): U.S.-made small end bushings with strong positioning in country-specific legacy platforms. Strategic focus: tight tolerances for performance restorations and niche OEM programs.
-
China and India-based manufacturers (select players): Offer cost-competitive bi-metal and bronze solutions at scale. Strategic focus: capture aftermarket and regionally localized OEM business, while investing incrementally in quality certifications to climb the value chain.
Recent industry developments underscore the strategic importance of being operationally and commercially nimble. In March 2026, a regulatory airworthiness directive (FAA) required replacement of certain connecting rod bushings in specific aero engine series — an example of how regulatory action can create concentrated, time-sensitive demand. Product catalog and kit updates among aftermarket vendors during 2024–2025 further demonstrate supplier responsiveness to service-driven revenue opportunities.
Practical playbook for 2026 — three strategic moves
-
Lock in critical raw-material pathways and modularize designs. Short-term hedges for copper/brass and aluminum alloys, coupled with design modularity that reduces requalification time for material substitutions, will protect margin and delivery performance.
-
Prioritize aftermarket and repair-kit strategies where conversion cycles are visible. Regulatory-driven replacements or fleet maintenance programs produce concentrated demand that favors suppliers with distribution, SKU breadth, and rapid fulfillment.
-
Make targeted capacity bets on precision machining and surface-treatment capabilities. Investment in friction-reducing coatings, micro-texturing, and high-precision bore finishing yields product differentiation that becomes increasingly valuable as ICEs evolve for efficiency.
Corporate development and M&A considerations
-
Buy capabilities, not just capacity: Pursue acquisitions that add metallurgical expertise, advanced testing labs, or validated OEM program certifications rather than solely chasing tonnage.
-
Prioritize bolt-on assets in regions where service turnaround times and spare-part availability create competitive advantage. Geographic proximity to large installed bases accelerates aftermarket monetization.
-
Screen targets using a resilience scorecard: supplier quality, certification maturity, closing time for PPAP/PPF, and ability to dual-source critical alloys.
What our report delivers to inform your 2026 plan
PW Consulting’s Automotive Connecting Rod Bush Market report is built as an operational decision support tool. Core deliverables include:
-
Macro market sizing and scenario forecasts (2026–2032) reflecting technology, regulatory, and regional adoption pathways — anchored to the 2025 base year.
-
Competitive landscape mapping and supplier capability benchmarking across manufacturing, quality systems, and aftermarket distribution.
-
Regulatory and product-risk matrix (including relevant airworthiness directives and their commercial implications) to prioritize product and service responses.
-
Actionable procurement and sourcing playbooks, including a dual-sourcing template, inventory buffers, and technical qualification checklists to accelerate time-to-volume for substitute alloys.
-
M&A and partnership screening tools with prioritized capability targets and integration checklists tailored to buyers seeking to expand into higher-value segments.
-
Appendix of technology trends — coatings, microtexturing, and friction-optimized geometries — with guidance on expected efficiency payoff per engine program (kept at a summary level here; detailed models are available in the full report).
How to use this intelligence
For OEM program managers, the report translates component-level advances into vehicle-level fuel economy and warranty outcomes. For Tier-1 and Tier-2 suppliers, it provides a road map to allocate capital between capacity, R&D, and aftermarket channel expansion. For private equity and corporate development teams, it delivers a prioritized acquisition funnel and an integration playbook geared to extract synergies in metallurgical know-how and aftermarket distribution.
In 2026, the competitive wins will go to organizations that blend engineering rigor with commercial speed: the manufacturers that can validate new materials quickly, the distributors who can fulfill regulatory replacement waves promptly, and the buyers who manage supplier risk without compromising cost. PW Consulting’s report is designed to make those choices less uncertain.
Next steps
This release is an executive synopsis intended to demonstrate scope and methodological rigor while preserving the segment-level datasets and supplier scorecards that underpin actionable strategy. For access to the full dataset — including granular segment breakouts, supplier scorecards, and the downloadable forecasting model — please visit the PW Consulting report page or contact our industry team to arrange a briefing. Our analysts will walk through tailored scenarios and the specific levers that will move margin and market share for your organization in 2026.
For detailed analysis of this topic, please visit the official page: Automotive Connecting Rod Bush Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial‑Grade Ferric Chloride Market Reaches USD 1,039.29 Million in 2025, Poised for 5.12% CAGR to USD 1,474.11 Million by 2032
By pmarketresearch, 2026-07-06
Industrial Grade Ferric Chloride Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive summary
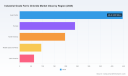
PW Consulting’s new Industrial Grade Ferric Chloride Market study (base year 2025, forecast 2026–2032) frames an evolving commodity with durable demand fundamentals and discrete supply-side vulnerabilities. Our analysis shows the market has expanded materially over the 2020–2025 period and is projected to continue growing through 2032, reaching an estimated market size in the high‑hundreds of millions to low billions (USD, revenue unit: Million), with a 2026–2032 compound annual growth rate (CAGR) of 5.12%. For executives preparing 2026 strategic plans, the report translates these macro dynamics into actionable decision frameworks — from procurement and capacity planning to regulatory risk management and M&A prioritization.
Industrial Grade Ferric Chloride Market
Why this matters for 2026 decision cycles
Ferric chloride occupies a unique position at the intersection of utilities, heavy industry, and specialty chemical supply chains. Demand drivers — primarily municipal and industrial water and wastewater treatment, metal surface treatment/etching, and a range of industrial intermediates — are subject to regulatory tightening, infrastructure investment cycles, and process substitution pressures. Meanwhile, production is materially linked to the chlor‑alkali and steel sectors, exposing supply to upstream plant economics and maintenance cycles.
Industrial Grade Ferric Chloride Market
- Purchasing teams need forward-looking price and availability scenarios to avoid single-source exposure during chlor‑alkali outages.
- Plant managers evaluating capital projects should incorporate differentiated product forms (liquid vs. anhydrous/solid) in CAPEX/OPEX models because handling, storage, and transport costs change investment returns.
- Corporate strategists must weigh consolidation and backward integration options against a market that remains moderately concentrated (top‑three and top‑five players control a meaningful portion of supply), making targeted M&A and partnership plays potentially accretive.
Market trajectory and growth context
Over the historical window (2020–2025) the market demonstrated resilience amid macro volatility as municipal capital programs and industrial effluent regulation sustained base demand. Our forecast shows continued expansion through 2032 under the central scenario, driven by incremental tightening of effluent phosphorus limits, urbanization, and industrial capacity recovery in key manufacturing sectors. The projected 5.12% CAGR for 2026–2032 reflects a balance between demand tailwinds and episodic supply constraints tied to upstream feedstocks.
Industrial Grade Ferric Chloride Market
Supply chain and raw‑material dynamics
Ferric chloride production is not an island: it is materially dependent on inputs from the chlor‑alkali value chain (chlorine/chlorine‑derived feedstock) alongside iron/steel feedstocks. Historical contractions in chlor‑alkali capacity and cycles in steel demand have led to episodic tightenings of ferric chloride availability and price spikes. Our scenario work models three supply states — balanced, constrained (chlor‑alkali maintenance/outage), and surplus — and quantifies near‑term procurement risk exposure for each.
- Procurement playbooks in the report map hedging and contract design options to these supply states, including rolling contracts with volume bands, strategic inventory cushions, and short‑term spot windows.
- We stress‑tested typical supply networks against chlor‑alkali disruption scenarios and provide recommended inventory thresholds and alternative sourcing checklists by product form.
- For firms evaluating backward integration, we provide a decision tree that weighs capital intensity, feedstock access, and regulatory compliance costs versus long‑term price capture.
Regulatory and end‑market pressures
Water and wastewater treatment applications are subject to progressively stringent effluent standards in many jurisdictions. In the U.S., for example, suppliers that target drinking‑water applications must meet NSF/ANSI Standard 60, and many producers maintain relevant certifications. Additionally, ferric chloride’s primary role in phosphorus removal and coagulation places it at the center of municipal compliance investments. The report contains a regulatory risk matrix that maps anticipated compliance timelines across major jurisdictions and the likely impact on product specification demand (e.g., purity, formulation consistency, and certification requirements).
Competitive landscape: actionable insights
The industry’s supplier set combines global chemical majors, regional specialists, and niche producers. Key players we profile include North American focused manufacturers, European integrated chemical producers, Middle East certified suppliers, and high‑capacity Asian manufacturers. Each brings differentiated capabilities:
- Some global majors maintain integrated chlorine electrolysis capability and continue to produce anhydrous grades, giving them a strategic edge for specialty applications that demand high‑purity feedstock and scale consistency.
- Regional and certified producers differentiate on regulatory certifications (NSF/ANSI and comparable schemes), local distribution networks, and tailored service models for municipal customers.
- Large Asian producers offer high volume, cost‑competitive liquid and solid forms, supporting export flows and industrial demand in adjacent markets.
We include company scorecards that evaluate manufacturing footprint, product form breadth (liquid vs. anhydrous/hexahydrate), certification profiles, and go‑to‑market capabilities. The market shows a mid‑level concentration: the top three suppliers control a substantial share of available supply and the top five increase that concentration materially, which has implications for negotiation leverage and potential regulatory scrutiny in certain jurisdictions.
What’s inside the full PW Consulting report (practical tools)
Rather than an academic overview, the study is explicitly operational. Highlights include:
- Dynamic demand model: single‑page dashboards that project demand by macro scenarios and quantify sensitivity to wastewater regulation timetables.
- Supplier scorecards and a procurement decision matrix: comparative assessments across production capability, certification, logistical reach, and counterparty risk.
- Price and availability simulation toolkit: scenario outputs for spot vs. contracted procurement strategies under chlor‑alkali stress tests.
- CapEx advisory module: NPV and IRR templates for greenfield or brownfield additions, with handling and safety OPEX inputs by product form.
- Regulatory impact maps and compliance calendars: actionable timelines for certifications and anticipated permit-driven demand uplifts.
- Portfolio optimization playbook: recommendations for customers and producers on product‑form mix, inventory placement, and flexible packaging strategies to reduce landed cost volatility.
To preserve competitive confidentiality for report subscribers, we deliberately omit granular regional and application‑level splits and specific supplier volumes in this preview.
Strategic recommendations for 2026
For commercial leaders and boardrooms planning in 2026, our priority recommendations are:
- Adopt a layered procurement strategy: combine baseline long‑term contracts with capped spot exposure and pre‑negotiated flex volumes to manage supply shocks from chlor‑alkali outages.
- Reassess product‑form positioning: evaluate the economics of shifting incremental demand towards liquid or anhydrous forms depending on local handling infrastructure and regulatory requirements.
- Prioritize certified suppliers for municipal and drinking water portfolios: certifications materially reduce execution risk in tender processes and can be decisive in contract awards.
- Explore targeted partnerships and bolt‑on M&A: for companies seeking greater upstream control, small to mid‑size acquisitions of regional producers or long‑term tolling agreements are less capital‑intensive ways to secure feedstock access.
- Incorporate supply stress scenarios into capex gating: require project approvals to include sensitivity to feedstock interruptions and alternate feed options.
How PW Consulting supports implementation
Beyond the published study, PW Consulting offers bespoke advisory services that operationalize the report’s findings: supplier negotiations, negotiated hedging constructs, localized logistics redesign, and regulatory permit support. We help clients translate the 5.12% CAGR planning assumption and scenario outputs into procurement budgets, inventory policies, and capital deployment plans for 2026 and beyond.
Conclusion and next steps
The industrial grade ferric chloride landscape presents a classic “stable demand, brittle supply” dynamic. For 2026 decision cycles, the imperative is to convert market foresight into contractual and operational resilience. PW Consulting’s report supplies the analytical backbone and practical toolset to do exactly that — while reserving detailed segment and supplier volume tables for report subscribers. For procurement, operations, and corporate strategy teams preparing budgets and capital plans this year, integrating the scenarios and playbooks we provide can materially reduce execution risk and uncover selective value creation opportunities.
To access the full report, detailed segment tables, supplier scorecards, and modeling templates that underpin these insights, please visit PW Consulting’s report page or contact our advisory team to schedule a walkthrough tailored to your company’s exposure and objectives.
For detailed analysis of this topic, please visit the official page: Industrial Grade Ferric Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Processed Vegetable Market to Jump from USD 320.0 Billion in 2025 to USD 454.8 Billion by 2032, Tracking a 5.15% CAGR
By pmarketresearch, 2026-07-06
Processed Vegetable Market 2026: Strategic Imperatives for Leaders — PW Consulting Industry Brief
As senior strategists at PW Consulting, we present a focused industry briefing distilled from our forthcoming Processed Vegetable Market report. This analysis is designed to help executive teams convert market signals into decisive 2026 actions. Our intent is to demonstrate the depth and rigor of the full study while reserving the granular segmentation tables and proprietary models for subscribers — a deliberate “trailer” approach to catalyze direct engagement with the complete report.
Processed Vegetable Market
Executive snapshot
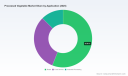
The processed vegetable market reached roughly USD 320 billion in 2025 and, under the baseline scenario in our model, is positioned to expand at a compound annual growth rate (CAGR) of about 5.15% over the 2026–2032 forecast window, trending toward the mid‑400s (USD) by 2032. That trajectory masks important short‑term volatility and shifting structural dynamics: supply‑side pressures, evolving regulatory scrutiny, and strategic consolidation are creating both elevated risk and high‑leverage opportunities for incumbent manufacturers, private‑label suppliers, ingredient processors, and foodservice partners.
Processed Vegetable Market
Why 2026 is pivotal for corporate decision‑makers
-
Macro inflection point: After a period of steady expansion, 2026 represents the transition from volume‑led growth to value‑and‑margin optimisation. Companies that use 2026 to align procurement, pricing, and product innovation will capture disproportionate share of the upside.
Processed Vegetable Market -
Capital redeployment window: Recent corporate restructurings and asset sales have created acquisition and capacity reallocation opportunities. Firms that deploy disciplined M&A frameworks now will secure scale and specialized capabilities at more favorable multiples than in prior cycles.
-
Regulatory and safety focus: Elevated recall activity and accelerating state‑level regulation mean 2026 will increasingly reward investments in traceability, testing, and product reformulations that reduce exposure to additives and contaminants.
Market dynamics: drivers, headwinds, and near‑term signals
-
Raw material inflation and sourcing: Public forecasts and our primary research indicate meaningful upward pressure on fresh vegetable prices in 2026, with sharp farm‑level increases that compress conventional margin models. Buyers and processors who implement multi‑tier procurement strategies, strategic forward contracting, and targeted hedges will be best placed to preserve margin integrity.
-
Supply chain resilience and trade risk: Trade tensions and tariff measures implemented in 2025 altered cross‑border economics for certain preserved goods. For companies reliant on North American and regional sourcing, localized redundancy and invest‑to‑scale in regional processing are now material strategic levers.
-
Food safety and recall exposure: The industry saw elevated recall activity in 2025, underscoring systemic vulnerability to contamination events. Investing in rapid‑response protocols, third‑party audit convergence, and batch‑level traceability reduces both operational downtime and reputational cost.
-
Changing channel dynamics: Retail and foodservice demand patterns continue to evolve — consumers favor convenience, premiumization of ready‑to‑heat vegetable preparations, and sustainability attributes. Long‑term value lies in premium convenience segments and industrial ingredient solutions that embed into broader prepared food value chains.
-
Regulatory headwinds on additives: Several sub‑national initiatives in 2025 seek restrictions on specific additives used in processed food. Product portfolios with legacy ingredient lists will face reformulation costs and market access friction unless proactive product stewardship programs are implemented this year.
Competitive landscape: interpretive takeaways (not a market share printout)
The competitive field remains fragmented by design: global branded players coexist with strong regional specialists and private label processors. Market concentration is moderate, leaving room for agile mid‑sized firms to scale through targeted M&A or by doubling down on service propositions to foodservice and industrial processors.
-
Dole plc and longstanding branded multinationals retain advantages in global sourcing and integrated farm‑to‑plant supply chains; they are natural acquirers of capability and can accelerate packaging, sustainability, and convenience innovations at scale.
-
Recent asset transactions have reshaped the competitive map. One prominent industry player completed the acquisition of packaged vegetable assets in March 2026, expanding its prepared and packaged processed vegetable portfolio and regional processing footprint. Corporate buyers should model the operational integration and SKU rationalizations that follow such deals when assessing M&A synergies.
-
Players like Conagra, Nestlé, Bonduelle, and long‑established private‑label processors continue to diversify across frozen, canned and dehydrated formats. Their strategic playbooks emphasize brand layering, channel segmentation, and supply chain depth rather than single‑format dominance.
-
Specialists such as Ardo, Greenyard, Seneca Foods, J.R. Simplot and other regionally focused processors compete on quality, speed‑to‑market, and specific channel intimacy (e.g., foodservice or industrial ingredient supply). These firms are logical partners for co‑manufacturing, innovation pilots, and regional capacity pooling.
Strategic implications and recommended 2026 actions
Executives must prioritize a limited set of high‑impact initiatives in 2026. Our consulting work with leading processors and CPG firms shows that combinations of the following actions create durable advantage.
-
Recalibrate procurement into a “total cost” framework: Move beyond spot price management to portfolio procurement that blends long‑term contracts, index‑linked supply, regional supplier panels, and strategic forward buys to smooth farm‑price shocks.
-
Invest in product reformulation and clean‑label migration: Anticipating additive restrictions and consumer preferences, re‑engineer core SKUs to maintain shelf life and sensory quality while meeting evolving regulatory and retailer demands.
-
Accelerate traceability and food safety digitization: Deploy batch‑level digital traceability and integrated lab‑diagnostics to shorten recall cycles and lower insurance and compliance costs. These investments pay back through faster incident resolution and improved retailer relationships.
-
Pursue targeted M&A and asset rationalization: Use strict playbooks to evaluate targets — prioritize asset adjacencies that shorten supply lines, add high‑margin convenience SKUs, or deliver proprietary processing capabilities (e.g., freeze‑dry, IQF advancements, and ready‑meal assembly).
-
Optimize channel margin: Differentiate pricing, packaging, and NPD by channel. For foodservice, prioritize cost‑efficiency and volume stability; for retail, emphasize convenience claims and premiumization.
-
Embed sustainability into cost and revenue models: Demonstrate supply‑chain emissions reduction and water stewardship; these attributes protect access to premium channels and institutional procurement contracts and increasingly factor into buyer selection.
-
Prototype manufacturing and co‑innovation hubs: Establish agile test lines or partnerships with specialist co‑manufacturers to speed new product introductions without large capital outlays.
What the PW Consulting report contains — practical, actionable modules
Our full Processed Vegetable Market report is built around an executive decision toolkit and includes:
-
Market sizing and a transparent forecast model (base year 2025; forecast through 2032) with scenario toggles for raw material price shocks, tariff scenarios, and accelerated additive regulation.
-
Demand segment playbooks that detail route‑to‑market strategies, SKU rationalization templates, and margin archetypes for retail, foodservice, and industrial customers (note: segmented numeric splits and individual regional shares are available in the full data annex).
-
Supply‑side diagnostics including a plant‑level capacity map, capital intensity benchmarks, and labor automation scorecards to prioritize modernization investments.
-
Risk heatmaps and recall mitigation frameworks, complemented by a compliance checklist tied to recent FDA/USDA and state regulatory developments.
-
M&A playbook with target screeners, valuation heuristics for asset vs. brand buys, and three worked examples demonstrating integration scenarios common to the sector.
-
Commercial acceleration kits — pricing playbooks, SKU assortment matrices, and retailer negotiation scripts — to turn strategic intent into quarterly execution plans.
-
Appendices with primary research notes, interview excerpts from growers, co‑packers, and major buyers, and a dataset for in‑house modelling (available to licensed users).
Case illustrations — how top performers will act in 2026
-
Integration‑focused consolidators will accelerate SKU rationalization and cross‑border sourcing to realize synergies from recent asset transactions while protecting margin through procurement centralization.
-
Quality‑led specialists will double down on premium frozen and semi‑prepared formats, using shorter lead times and fresh‑frozen processing to differentiate from low‑cost canned competition.
-
Retail and private‑label partners will invest in collaborative product development and shared risk arrangements that align incentives on pricing, inventory, and promotion cycles.
Final recommendations for 2026 planning cycles
Board and C‑suite teams should use 2026 planning to (1) validate procurement and pricing assumptions against scenario stress tests, (2) prioritize 1–2 capital projects that materially raise throughput or reduce cost‑per‑unit, and (3) clear M&A decision gates for bolt‑on capability buys. Operationally, make traceability and food safety non‑negotiable investment priorities — these are no longer compliance line items but competitive differentiators.
PW Consulting’s full report contains the detailed, source‑level data, regional and application segmentation, and financial templates that support these recommendations. For strategic teams preparing 2026 budgets and three‑year roadmaps, the proprietary outputs in the full study — including plant maps, SKU margin curves, and a shortlist of actionable M&A targets — will convert insight into transaction‑ready plans.
Access and next steps
To obtain the complete dataset, segmentation tables, and the interactive forecast model, please visit the PW Consulting report page or contact our Processed Vegetable practice lead. The summary here provides a strategic orientation; the full report supplies the operational playbooks and numerical evidence you will need to act decisively in 2026.
For detailed analysis of this topic, please visit the official page: Processed Vegetable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: IoT Security Solution for Unified Threat Management (UTM) Market to Expand at 22.15% CAGR, Rising from USD 6,285.2M in 2025 to USD 25,501.94M by 2032
By pmarketresearch, 2026-07-06
IoT Security Solutions for Unified Threat Management (UTM): Strategic Imperatives for 2026
Executive Overview
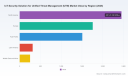
As enterprises accelerate connected deployments across factories, hospitals, campuses and smart cities, Unified Threat Management (UTM) platforms that can absorb the scale and diversity of IoT risk are moving from “nice to have” to mission-critical. Our new PW Consulting market study — with base year 2025 and a forecast horizon through 2032 — shows a sustained, high-growth trajectory (CAGR 22.15%) for IoT-focused UTM offerings, validating why security, procurement and architecture leaders must reframe their 2026 priorities around integrated, device-aware controls.
Iot Security Solution For Unified Threat Management Utm Market
To be clear: the macro market is expanding rapidly — the 2025 market base sits in the mid-single‑digit billions (USD, Million units basis), with a multi-fold expansion projected through 2032. This growth is driven by accelerating device density, regulatory pressure, and the operational need to consolidate tooling and visibility across hybrid estates.
Iot Security Solution For Unified Threat Management Utm Market
Why This Matters for 2026 Decision Makers
-
Strategic Timing: 2026 is a pivot year. With the EU Cyber Resilience Act fully rolling out and major data laws already in force across key jurisdictions, boards will expect demonstrable device security roadmaps. Investments in UTM capabilities now buy regulatory headroom as well as defensive depth.
Iot Security Solution For Unified Threat Management Utm Market -
Consolidation vs. Best-of-Breed Tradeoffs: Our concentration analysis indicates a moderately consolidated vendor ecosystem — top vendors control a meaningful portion of market share but there remains substantive room for differentiation and niche specialization. Procurement teams must weigh the benefits of broad, integrated platforms against specialized capabilities (for example, IoT profiling, lifecycle patching, and OT/IT segmentation).
-
Economic and Operational Levers: Rising infrastructure costs (notably data center construction and distributed compute) and supply-side pressures are changing TCO models. Buyers should model both capital and recurring operational costs when comparing appliance-centric, virtualized and cloud-native UTM options.
Report Highlights — Practical, Actionable Content
PW Consulting’s study is designed as an operational playbook for 2026 implementation. Highlights include:
-
Decision Frameworks: A practitioner-ready framework that maps organizational priorities (regulatory compliance, operational resilience, visibility, cost) to architectural choices (hardware UTM, virtual appliances, cloud SaaS).
-
Vendor Assessment Toolkit: A multi-dimensional vendor scoring model covering technical fit, integration maturity, support model, threat intel orchestration and financial sustainability — calibrated for IoT realities rather than generic enterprise networking.
-
Implementation Playbooks: Step-by-step roadmaps for device discovery, segmentation, policy migration, and incident response sequencing tailored to manufacturing floors, healthcare campuses and distributed retail footprints.
-
TCO and Risk Quantification Models: Scenario-based models that quantify upfront and run-rate costs alongside risk-reduction metrics (mean time to detection, containment window improvements), enabling CFO/CISO alignment on investment cases.
-
Procurement & Contract Guidance: Contractual clauses and service-level constructs that address firmware lifecycle, vulnerability disclosures, data residency and cross-border transfer obligations under emerging regulations.
Note: This article intentionally summarizes the report’s structure and strategic conclusions while withholding the granular segment-level forecasts, vendor rankings and pricing matrices that are available exclusively in the full report.
Competitive Landscape: Who Matters and Why
The UTM market for IoT security blends major networking and security vendors with specialist providers. The competitive set includes established incumbents known for integrated NGFW/UTM capabilities and newer entrants advancing cloud-native and AI-driven controls. Key players covered in the study include:
-
Fortinet, Inc.: Strong platform play combining NGFW and IoT-specific visibility/segmentation — appealing to enterprises seeking broad feature consolidation.
-
Cisco Systems, Inc.: Extensive portfolio across Secure Firewall and cloud-managed Meraki ecosystems, enabling hybrid deployments with deep device profiling.
-
Check Point Software Technologies Ltd.: Emphasis on prevention, policy enforcement and cloud posture integration relevant to multi-cloud IoT architectures.
-
Sophos Ltd. & WatchGuard Technologies, Inc.: Positioned for SMEs and managed service providers with simplified management and co-managed service models.
-
SonicWall, Barracuda, Juniper, Huawei, Palo Alto Networks: Each brings differentiated strengths — from appliance-focused performance and distributed firewalling to AI threat detection and Zero Trust enforcement — making vendor selection inherently contextual to deployment size and risk profile.
Recent industry moves underscore the pace of product evolution: new-generation firewalls incorporating Zero Trust Network Access (ZTNA), SASE converged platforms, and iterative UTM software updates were announced in 2026 — signaling that vendors are actively optimizing for co-managed services and AI-driven controls. These developments should influence procurement timelines; in many cases, a six- to twelve-month wait for next‑gen releases may be warranted if the feature set aligns with an organization’s strategic goals.
Regulatory and Cost Dynamics Shaping Buyer Priorities
-
Regulation as a Purchase Driver: The EU Cyber Resilience Act and the enforcement of the EU Data Act are elevating manufacturer liability and user data rights — making device lifecycle security and data portability contractual must-haves. Parallel rules in other jurisdictions (e.g., China’s data security regulations, U.S. bulk data controls) create compliance fragmentation that favors vendors with mature regional controls and data routing options.
-
Infrastructure Cost Pressures: Higher data center build costs and the growth of edge compute change where UTM processing should occur. Edge-friendly, resource-efficient virtual appliances and SaaS-delivered analytics reduce capital intensity but introduce new network egress and latency considerations.
Practical Recommendations for 2026
-
Adopt a Phased Consolidation Strategy: Start with discovery and segmentation pilots in high-risk device clusters, then expand policy-driven UTM controls while preserving the ability to integrate specialized tooling for deep OT/ICS use cases.
-
Insist on Lifecycle Guarantees: Contractually require firmware update commitments, vulnerability disclosure timelines and provenance controls — these are now procurement differentiators, not optional extras.
-
Leverage Co-Managed Models: For organisations lacking full-time IoT security expertise, co-managed and MSSP-backed UTM offerings accelerate time-to-value while retaining internal governance.
-
Align TCO to Risk Metrics: Use the report’s TCO scenarios to present clear ROI tied to risk reduction (e.g., reduced dwell time, avoidance of regulatory fines) for executive stakeholders.
-
Plan for Interoperability: Prioritize vendors that support open telemetry, standardized device profiling and API-first orchestration — these reduce lock‑in risk and enable hybrid deployments that mix cloud, virtual and hardware UTM elements.
How PW Consulting’s Report Helps You Win in 2026
Organizations that move beyond checkbox security and treat IoT UTM as a strategic capability will gain both risk and operational advantages. Our report is tailored to this reality: it combines granular market sizing, competitive benchmarking, regulatory scenario planning, and implementation playbooks into a single practitioner resource. For CIOs, CISOs, procurement leads and managed service operators, the study translates market growth and vendor evolution into executable roadmaps.
Remember: this article provides a high-level strategic view. The full PW Consulting report contains the detailed vendor scorecards, segment-specific forecasts, pricing and contract templates, and the precise models you need to finalize 2026 budgets and RFPs. Those granular insights are intentionally reserved for the full publication to ensure decision-makers have the actionable intelligence required to execute with confidence.
Next Steps
-
Download the executive summary and procurement checklist from our report portal to map our frameworks to your 2026 planning cycle.
-
Engage PW Consulting for a tailored vendor-selection workshop that applies our scoring model directly to your device inventory and regulatory constraints.
In an era where device proliferation multiplies attack surfaces faster than teams can hire specialists, the right UTM strategy — informed by market reality, regulatory foresight and practical implementation playbooks — is the difference between managed risk and disruptive incidents. Our 2026-focused guidance is built to help leaders choose decisively.
For detailed analysis of this topic, please visit the official page: Iot Security Solution For Unified Threat Management Utm Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Software Asset Management Managed Services to Rise from USD 1,475.78 Million in 2025 to USD 3,885.17 Million by 2032 (14.83% CAGR) — North America, Compliance Services and Large Enterprises Drive Growth as Top 5 Firms Hold 46.82%
By pmarketresearch, 2026-07-06
PW Consulting: Strategic Outlook — Software Asset Management Managed Service Market (2026 Preview)
As organizations enter 2026 with renewed focus on operational resilience, compliance, and cloud cost discipline, Software Asset Management (SAM) managed services have moved from niche optimization programs to board-level priorities. PW Consulting’s latest market research report — the Software Asset Management Managed Service Market — synthesizes six years of historical evidence and a forward-looking forecast to equip procurement leaders, CIOs, and CFOs with a pragmatic strategy playbook for 2026 decision-making.
Software Asset Management Managed Service Market
Why this report matters for 2026 decisions
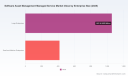
Markets are shaped as much by regulation and enforcement as they are by technology. Between accelerating SaaS adoption, the proliferation of complex licensing models, and stronger privacy and cybersecurity obligations at state and federal levels, SAM managed services are now a linchpin for predictable IT spend and risk mitigation. Our findings show the SAM managed services market expanding materially over the past half-decade and projected to continue at a robust compound annual growth rate (CAGR) of approximately 14.8% through the forecast window. The market size trajectory underscores a strategic inflection point: buyers must decide whether to invest in auxiliary capabilities (data governance, vendor-license expertise, AI-enabled normalization) internally, or to execute via third-party managed services that blend tooling, practitioner depth, and contractual risk transfer.
Software Asset Management Managed Service Market
Headline market dynamics (evidence-based)
-
Scale: The market has more than doubled since 2020 and is projected to continue expanding throughout the 2026–2032 forecast period, reflecting sustained demand for license optimization, compliance assurance, and cloud/SaaS cost governance.
Software Asset Management Managed Service Market -
Concentration: Market concentration remains moderate. The top three and top five providers collectively account for a meaningful — but not overwhelming — share of activity, leaving room for specialized players and regional integrators to compete on technical depth and industry-specific offerings.
-
Service convergence: SAM is increasingly bundled with cloud cost optimization, FinOps practices, and SaaS management. Buyers are seeking integrated outcomes: compliance plus predictable unit economics for cloud and subscription spend.
-
Regulatory pressure: A growing patchwork of privacy and data-security laws (including numerous U.S. state privacy laws and national rules) and federal obligations affecting bulk data handling have raised the bar on how SAM data is discovered, stored, and processed — directly shaping vendor selection and contract design.
Operational realities shaping supplier selection
For 2026, our practical guidance to enterprise leaders centers on three decisions: (1) define the outcome set you need SAM to deliver; (2) decide how much control you must retain over sensitive data flows; and (3) choose the delivery model that balances cost with vendor license expertise.
-
Outcomes-first contracting — shift from time-and-materials to measurable outcomes (e.g., audit-readiness, subscription rightsizing, SaaS rationalization targets).
-
Data governance as a procurement criterion — vet providers on data residency, encryption at rest and in transit, role-based access, and incident response tied to SAM datasets.
-
Specialist skills matter — vendor-specific licensing expertise and experience with vendor audit playbooks continue to be a primary operational driver and cost center; buyers should insist on proof-of-work and practitioner accreditation.
What the PW Consulting report delivers (practical, executable content)
This report is purposely tactical. It is designed to guide the “what” and the “how” for 2026 implementation, while reserving granular market split tables and vendor scorecards for the full report to preserve the strategic value of the analysis. Key deliverables within the publication include:
-
Decision frameworks to align SAM objectives with cloud and FinOps governance — templates for executive alignment and KPI scorecards.
-
Procurement playbooks — RFP templates, evaluation criteria, and commercial guardrails for outcome-based pricing, SLAs tied to audit defense, and data-handling clauses required by modern privacy regimes.
-
Implementation roadmaps — phased approaches for discovery, normalization, optimization, and continuous compliance, including operational runbooks that teams can adopt directly.
-
Technology stack assessments — capability maps for discovery agents, normalization engines, license metric interpreters, and AI-enabled optimization modules; guidance on when to integrate best-of-breed SaaS management platforms vs. adopting larger managed service bundles.
-
Case studies and “war stories” — anonymized client engagements demonstrating audit defense, multi-vendor license consolidation, and SaaS portfolio rationalization, with before/after financial and operational metrics.
-
Risk and compliance checklists — a concise register tying state and federal regulatory obligations to concrete operational controls and contractual terms.
Competitive landscape — who to watch and why
The supplier field comprises several identifiable archetypes: pure-play SAM specialists, global licensing and resale leaders, systems integrators with SAM practices, and SaaS-first platforms that provide discovery and SaaS lifecycle management. Each archetype brings distinct advantages depending on buyer priorities.
-
Pure-play specialists — Anglepoint ( https://www.anglepoint.com) stands out for its deep, license-centric managed service offering and longstanding focus on visibility, optimization, and audit defense. Such providers are often preferred where vendor audit risk and legacy estate complexity are primary concerns.
-
Global license and resale leaders — SoftwareOne ( https://www.softwareone.com) combines broad licensing expertise with global delivery scale, pairing resale capabilities with managed services to serve multinational deployments.
-
Execution-focused delivery partners — Crayon ( https://www.crayon.com) offers a strong operational delivery model and often partners with other ecosystem players to execute large-scale transformations across licensing and SaaS optimization.
-
Systems integrators and professional services firms — Deloitte ( https://www.deloitte.com) and Insight ( https://www.insight.com) bring deep vendor-license expertise coupled with extensive systems integration capabilities and a broader IT services portfolio that supports enterprise-wide change programs.
-
SaaS management and platform specialists — Companies such as Zluri ( https://www.zluri.com) represent the SaaS-first approach, emphasizing discovery, subscription control, and lightweight governance that often appeals to rapid-growth and SaaS-heavy organizations.
-
Regional and hybrid players — Livingstone Technologies ( https://livingstone-tech.com) and Softchoice ( https://www.softchoice.com) exemplify vendors that combine licensing insight with region-specific execution and cloud enablement services.
Market recognition and industry signals reinforce these positions. Notably, Anglepoint, SoftwareOne, and Crayon have continued to receive vendor-recognition accolades, and Insight was named in a leading industry quadrant for execution and vision — signals that matter when evaluating a partner’s strategic commitment and investment in SAM capabilities.
Regulatory and risk environment: immediate implications
Recent regulatory developments materially affect how SAM data must be treated and where responsibility lies during audits and contractual disputes. Examples include the expansion of U.S. state privacy regimes and federal rules impacting bulk data handling. For 2026 procurement, this translates into a few non-negotiables:
-
Contractual liabilities must be clear on data custody and breach obligations tied to SAM discovery datasets.
-
Providers must demonstrate compliance with applicable state privacy laws and federal rules for bulk data transactions, including documented dataflow maps and controls.
-
Technical safeguards — encryption, access controls, and immutable logs — should be validated as part of security due diligence.
Practical recommendations for 2026 buyers
Based on the research and market signals, PW Consulting advises the following priority actions for organizations planning SAM engagements in 2026:
-
Start with an outcome profile: audit avoidance, subscription optimization, SaaS rationalization, or cloud cost governance — clarity here determines partner fit.
-
Include data-governance and regulatory compliance requirements as scored RFP criteria — not as add-ons. Ask for evidence, certifications, and sample dataflow documentation.
-
Favor providers that can demonstrate both license metric expertise and continuous delivery capability (not one-off projects) — proof points such as multi-year engagements and audit defense cases are valuable.
-
Consider blended delivery models: combine a specialist for audit and licensing depth with a cloud/FinOps partner for ongoing cost control.
-
Invest in internal capability uplift — train a small core team in vendor-specific license models and AI-enabled normalization; this increases bargaining power and reduces single-vendor dependency.
Where this article leaves off — and why you should read the full report
This briefing is intentionally high-level: it outlines market scale, the key dynamics shaping 2026 procurement, and the operational choices buyers face. PW Consulting’s full report contains the granular tools and the confidential analytical appendices that procurement teams will use when executing a SAM transformation — including vendor scorecards, regional and service-type segmentation tables, detailed financial scenarios, and model contracts. Those core items are reserved for the report to preserve their practical value for our subscribers and clients.
In an era where software spend and regulatory obligations are both rising, SAM managed services are not a cost center — they are a strategic risk-control and value-creation lever. The evidence is clear: firms that align governance, technology, and vendor strategy will materially reduce audit exposure, improve cloud economics, and create predictable IT spend profiles. For leaders preparing 2026 budgets and sourcing decisions, the full PW Consulting report is the operational manual you will reference throughout contract negotiation and implementation.
How to access the full intelligence
To obtain the full Software Asset Management Managed Service Market report, including detailed vendor assessments, segmentation matrices, and procurement templates, visit the PW Consulting research portal or contact our industry advisory team for a briefing. The actionable content within the full report is designed to be immediately usable by procurement, legal, and IT teams charged with executing SAM and SaaS governance programs in 2026.
For detailed analysis of this topic, please visit the official page: Software Asset Management Managed Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com