

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Industrial‑Grade Ferric Chloride Market Reaches USD 1,039.29 Million in 2025, Poised for 5.12% CAGR to USD 1,474.11 Million by 2032

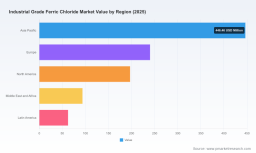
Industrial Grade Ferric Chloride Market: Strategic Imperatives for 2026 — A PW Consulting Preview
Executive summary
PW Consulting’s new Industrial Grade Ferric Chloride Market study (base year 2025, forecast 2026–2032) frames an evolving commodity with durable demand fundamentals and discrete supply-side vulnerabilities. Our analysis shows the market has expanded materially over the 2020–2025 period and is projected to continue growing through 2032, reaching an estimated market size in the high‑hundreds of millions to low billions (USD, revenue unit: Million), with a 2026–2032 compound annual growth rate (CAGR) of 5.12%. For executives preparing 2026 strategic plans, the report translates these macro dynamics into actionable decision frameworks — from procurement and capacity planning to regulatory risk management and M&A prioritization.
Industrial Grade Ferric Chloride Market
Why this matters for 2026 decision cycles
Ferric chloride occupies a unique position at the intersection of utilities, heavy industry, and specialty chemical supply chains. Demand drivers — primarily municipal and industrial water and wastewater treatment, metal surface treatment/etching, and a range of industrial intermediates — are subject to regulatory tightening, infrastructure investment cycles, and process substitution pressures. Meanwhile, production is materially linked to the chlor‑alkali and steel sectors, exposing supply to upstream plant economics and maintenance cycles.
Industrial Grade Ferric Chloride Market
- Purchasing teams need forward-looking price and availability scenarios to avoid single-source exposure during chlor‑alkali outages.
- Plant managers evaluating capital projects should incorporate differentiated product forms (liquid vs. anhydrous/solid) in CAPEX/OPEX models because handling, storage, and transport costs change investment returns.
- Corporate strategists must weigh consolidation and backward integration options against a market that remains moderately concentrated (top‑three and top‑five players control a meaningful portion of supply), making targeted M&A and partnership plays potentially accretive.
Market trajectory and growth context
Over the historical window (2020–2025) the market demonstrated resilience amid macro volatility as municipal capital programs and industrial effluent regulation sustained base demand. Our forecast shows continued expansion through 2032 under the central scenario, driven by incremental tightening of effluent phosphorus limits, urbanization, and industrial capacity recovery in key manufacturing sectors. The projected 5.12% CAGR for 2026–2032 reflects a balance between demand tailwinds and episodic supply constraints tied to upstream feedstocks.
Industrial Grade Ferric Chloride Market
Supply chain and raw‑material dynamics
Ferric chloride production is not an island: it is materially dependent on inputs from the chlor‑alkali value chain (chlorine/chlorine‑derived feedstock) alongside iron/steel feedstocks. Historical contractions in chlor‑alkali capacity and cycles in steel demand have led to episodic tightenings of ferric chloride availability and price spikes. Our scenario work models three supply states — balanced, constrained (chlor‑alkali maintenance/outage), and surplus — and quantifies near‑term procurement risk exposure for each.
- Procurement playbooks in the report map hedging and contract design options to these supply states, including rolling contracts with volume bands, strategic inventory cushions, and short‑term spot windows.
- We stress‑tested typical supply networks against chlor‑alkali disruption scenarios and provide recommended inventory thresholds and alternative sourcing checklists by product form.
- For firms evaluating backward integration, we provide a decision tree that weighs capital intensity, feedstock access, and regulatory compliance costs versus long‑term price capture.
Regulatory and end‑market pressures
Water and wastewater treatment applications are subject to progressively stringent effluent standards in many jurisdictions. In the U.S., for example, suppliers that target drinking‑water applications must meet NSF/ANSI Standard 60, and many producers maintain relevant certifications. Additionally, ferric chloride’s primary role in phosphorus removal and coagulation places it at the center of municipal compliance investments. The report contains a regulatory risk matrix that maps anticipated compliance timelines across major jurisdictions and the likely impact on product specification demand (e.g., purity, formulation consistency, and certification requirements).
Competitive landscape: actionable insights
The industry’s supplier set combines global chemical majors, regional specialists, and niche producers. Key players we profile include North American focused manufacturers, European integrated chemical producers, Middle East certified suppliers, and high‑capacity Asian manufacturers. Each brings differentiated capabilities:
- Some global majors maintain integrated chlorine electrolysis capability and continue to produce anhydrous grades, giving them a strategic edge for specialty applications that demand high‑purity feedstock and scale consistency.
- Regional and certified producers differentiate on regulatory certifications (NSF/ANSI and comparable schemes), local distribution networks, and tailored service models for municipal customers.
- Large Asian producers offer high volume, cost‑competitive liquid and solid forms, supporting export flows and industrial demand in adjacent markets.
We include company scorecards that evaluate manufacturing footprint, product form breadth (liquid vs. anhydrous/hexahydrate), certification profiles, and go‑to‑market capabilities. The market shows a mid‑level concentration: the top three suppliers control a substantial share of available supply and the top five increase that concentration materially, which has implications for negotiation leverage and potential regulatory scrutiny in certain jurisdictions.
What’s inside the full PW Consulting report (practical tools)
Rather than an academic overview, the study is explicitly operational. Highlights include:
- Dynamic demand model: single‑page dashboards that project demand by macro scenarios and quantify sensitivity to wastewater regulation timetables.
- Supplier scorecards and a procurement decision matrix: comparative assessments across production capability, certification, logistical reach, and counterparty risk.
- Price and availability simulation toolkit: scenario outputs for spot vs. contracted procurement strategies under chlor‑alkali stress tests.
- CapEx advisory module: NPV and IRR templates for greenfield or brownfield additions, with handling and safety OPEX inputs by product form.
- Regulatory impact maps and compliance calendars: actionable timelines for certifications and anticipated permit-driven demand uplifts.
- Portfolio optimization playbook: recommendations for customers and producers on product‑form mix, inventory placement, and flexible packaging strategies to reduce landed cost volatility.
To preserve competitive confidentiality for report subscribers, we deliberately omit granular regional and application‑level splits and specific supplier volumes in this preview.
Strategic recommendations for 2026
For commercial leaders and boardrooms planning in 2026, our priority recommendations are:
- Adopt a layered procurement strategy: combine baseline long‑term contracts with capped spot exposure and pre‑negotiated flex volumes to manage supply shocks from chlor‑alkali outages.
- Reassess product‑form positioning: evaluate the economics of shifting incremental demand towards liquid or anhydrous forms depending on local handling infrastructure and regulatory requirements.
- Prioritize certified suppliers for municipal and drinking water portfolios: certifications materially reduce execution risk in tender processes and can be decisive in contract awards.
- Explore targeted partnerships and bolt‑on M&A: for companies seeking greater upstream control, small to mid‑size acquisitions of regional producers or long‑term tolling agreements are less capital‑intensive ways to secure feedstock access.
- Incorporate supply stress scenarios into capex gating: require project approvals to include sensitivity to feedstock interruptions and alternate feed options.
How PW Consulting supports implementation
Beyond the published study, PW Consulting offers bespoke advisory services that operationalize the report’s findings: supplier negotiations, negotiated hedging constructs, localized logistics redesign, and regulatory permit support. We help clients translate the 5.12% CAGR planning assumption and scenario outputs into procurement budgets, inventory policies, and capital deployment plans for 2026 and beyond.
Conclusion and next steps
The industrial grade ferric chloride landscape presents a classic “stable demand, brittle supply” dynamic. For 2026 decision cycles, the imperative is to convert market foresight into contractual and operational resilience. PW Consulting’s report supplies the analytical backbone and practical toolset to do exactly that — while reserving detailed segment and supplier volume tables for report subscribers. For procurement, operations, and corporate strategy teams preparing budgets and capital plans this year, integrating the scenarios and playbooks we provide can materially reduce execution risk and uncover selective value creation opportunities.
To access the full report, detailed segment tables, supplier scorecards, and modeling templates that underpin these insights, please visit PW Consulting’s report page or contact our advisory team to schedule a walkthrough tailored to your company’s exposure and objectives.
For detailed analysis of this topic, please visit the official page: Industrial Grade Ferric Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com