

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Processed Vegetable Market to Jump from USD 320.0 Billion in 2025 to USD 454.8 Billion by 2032, Tracking a 5.15% CAGR

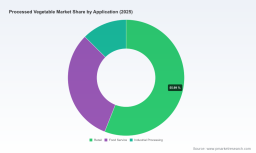
Processed Vegetable Market 2026: Strategic Imperatives for Leaders — PW Consulting Industry Brief
As senior strategists at PW Consulting, we present a focused industry briefing distilled from our forthcoming Processed Vegetable Market report. This analysis is designed to help executive teams convert market signals into decisive 2026 actions. Our intent is to demonstrate the depth and rigor of the full study while reserving the granular segmentation tables and proprietary models for subscribers — a deliberate “trailer” approach to catalyze direct engagement with the complete report.
Processed Vegetable Market
Executive snapshot
The processed vegetable market reached roughly USD 320 billion in 2025 and, under the baseline scenario in our model, is positioned to expand at a compound annual growth rate (CAGR) of about 5.15% over the 2026–2032 forecast window, trending toward the mid‑400s (USD) by 2032. That trajectory masks important short‑term volatility and shifting structural dynamics: supply‑side pressures, evolving regulatory scrutiny, and strategic consolidation are creating both elevated risk and high‑leverage opportunities for incumbent manufacturers, private‑label suppliers, ingredient processors, and foodservice partners.
Processed Vegetable Market
Why 2026 is pivotal for corporate decision‑makers
-
Macro inflection point: After a period of steady expansion, 2026 represents the transition from volume‑led growth to value‑and‑margin optimisation. Companies that use 2026 to align procurement, pricing, and product innovation will capture disproportionate share of the upside.
Processed Vegetable Market -
Capital redeployment window: Recent corporate restructurings and asset sales have created acquisition and capacity reallocation opportunities. Firms that deploy disciplined M&A frameworks now will secure scale and specialized capabilities at more favorable multiples than in prior cycles.
-
Regulatory and safety focus: Elevated recall activity and accelerating state‑level regulation mean 2026 will increasingly reward investments in traceability, testing, and product reformulations that reduce exposure to additives and contaminants.
Market dynamics: drivers, headwinds, and near‑term signals
-
Raw material inflation and sourcing: Public forecasts and our primary research indicate meaningful upward pressure on fresh vegetable prices in 2026, with sharp farm‑level increases that compress conventional margin models. Buyers and processors who implement multi‑tier procurement strategies, strategic forward contracting, and targeted hedges will be best placed to preserve margin integrity.
-
Supply chain resilience and trade risk: Trade tensions and tariff measures implemented in 2025 altered cross‑border economics for certain preserved goods. For companies reliant on North American and regional sourcing, localized redundancy and invest‑to‑scale in regional processing are now material strategic levers.
-
Food safety and recall exposure: The industry saw elevated recall activity in 2025, underscoring systemic vulnerability to contamination events. Investing in rapid‑response protocols, third‑party audit convergence, and batch‑level traceability reduces both operational downtime and reputational cost.
-
Changing channel dynamics: Retail and foodservice demand patterns continue to evolve — consumers favor convenience, premiumization of ready‑to‑heat vegetable preparations, and sustainability attributes. Long‑term value lies in premium convenience segments and industrial ingredient solutions that embed into broader prepared food value chains.
-
Regulatory headwinds on additives: Several sub‑national initiatives in 2025 seek restrictions on specific additives used in processed food. Product portfolios with legacy ingredient lists will face reformulation costs and market access friction unless proactive product stewardship programs are implemented this year.
Competitive landscape: interpretive takeaways (not a market share printout)
The competitive field remains fragmented by design: global branded players coexist with strong regional specialists and private label processors. Market concentration is moderate, leaving room for agile mid‑sized firms to scale through targeted M&A or by doubling down on service propositions to foodservice and industrial processors.
-
Dole plc and longstanding branded multinationals retain advantages in global sourcing and integrated farm‑to‑plant supply chains; they are natural acquirers of capability and can accelerate packaging, sustainability, and convenience innovations at scale.
-
Recent asset transactions have reshaped the competitive map. One prominent industry player completed the acquisition of packaged vegetable assets in March 2026, expanding its prepared and packaged processed vegetable portfolio and regional processing footprint. Corporate buyers should model the operational integration and SKU rationalizations that follow such deals when assessing M&A synergies.
-
Players like Conagra, Nestlé, Bonduelle, and long‑established private‑label processors continue to diversify across frozen, canned and dehydrated formats. Their strategic playbooks emphasize brand layering, channel segmentation, and supply chain depth rather than single‑format dominance.
-
Specialists such as Ardo, Greenyard, Seneca Foods, J.R. Simplot and other regionally focused processors compete on quality, speed‑to‑market, and specific channel intimacy (e.g., foodservice or industrial ingredient supply). These firms are logical partners for co‑manufacturing, innovation pilots, and regional capacity pooling.
Strategic implications and recommended 2026 actions
Executives must prioritize a limited set of high‑impact initiatives in 2026. Our consulting work with leading processors and CPG firms shows that combinations of the following actions create durable advantage.
-
Recalibrate procurement into a “total cost” framework: Move beyond spot price management to portfolio procurement that blends long‑term contracts, index‑linked supply, regional supplier panels, and strategic forward buys to smooth farm‑price shocks.
-
Invest in product reformulation and clean‑label migration: Anticipating additive restrictions and consumer preferences, re‑engineer core SKUs to maintain shelf life and sensory quality while meeting evolving regulatory and retailer demands.
-
Accelerate traceability and food safety digitization: Deploy batch‑level digital traceability and integrated lab‑diagnostics to shorten recall cycles and lower insurance and compliance costs. These investments pay back through faster incident resolution and improved retailer relationships.
-
Pursue targeted M&A and asset rationalization: Use strict playbooks to evaluate targets — prioritize asset adjacencies that shorten supply lines, add high‑margin convenience SKUs, or deliver proprietary processing capabilities (e.g., freeze‑dry, IQF advancements, and ready‑meal assembly).
-
Optimize channel margin: Differentiate pricing, packaging, and NPD by channel. For foodservice, prioritize cost‑efficiency and volume stability; for retail, emphasize convenience claims and premiumization.
-
Embed sustainability into cost and revenue models: Demonstrate supply‑chain emissions reduction and water stewardship; these attributes protect access to premium channels and institutional procurement contracts and increasingly factor into buyer selection.
-
Prototype manufacturing and co‑innovation hubs: Establish agile test lines or partnerships with specialist co‑manufacturers to speed new product introductions without large capital outlays.
What the PW Consulting report contains — practical, actionable modules
Our full Processed Vegetable Market report is built around an executive decision toolkit and includes:
-
Market sizing and a transparent forecast model (base year 2025; forecast through 2032) with scenario toggles for raw material price shocks, tariff scenarios, and accelerated additive regulation.
-
Demand segment playbooks that detail route‑to‑market strategies, SKU rationalization templates, and margin archetypes for retail, foodservice, and industrial customers (note: segmented numeric splits and individual regional shares are available in the full data annex).
-
Supply‑side diagnostics including a plant‑level capacity map, capital intensity benchmarks, and labor automation scorecards to prioritize modernization investments.
-
Risk heatmaps and recall mitigation frameworks, complemented by a compliance checklist tied to recent FDA/USDA and state regulatory developments.
-
M&A playbook with target screeners, valuation heuristics for asset vs. brand buys, and three worked examples demonstrating integration scenarios common to the sector.
-
Commercial acceleration kits — pricing playbooks, SKU assortment matrices, and retailer negotiation scripts — to turn strategic intent into quarterly execution plans.
-
Appendices with primary research notes, interview excerpts from growers, co‑packers, and major buyers, and a dataset for in‑house modelling (available to licensed users).
Case illustrations — how top performers will act in 2026
-
Integration‑focused consolidators will accelerate SKU rationalization and cross‑border sourcing to realize synergies from recent asset transactions while protecting margin through procurement centralization.
-
Quality‑led specialists will double down on premium frozen and semi‑prepared formats, using shorter lead times and fresh‑frozen processing to differentiate from low‑cost canned competition.
-
Retail and private‑label partners will invest in collaborative product development and shared risk arrangements that align incentives on pricing, inventory, and promotion cycles.
Final recommendations for 2026 planning cycles
Board and C‑suite teams should use 2026 planning to (1) validate procurement and pricing assumptions against scenario stress tests, (2) prioritize 1–2 capital projects that materially raise throughput or reduce cost‑per‑unit, and (3) clear M&A decision gates for bolt‑on capability buys. Operationally, make traceability and food safety non‑negotiable investment priorities — these are no longer compliance line items but competitive differentiators.
PW Consulting’s full report contains the detailed, source‑level data, regional and application segmentation, and financial templates that support these recommendations. For strategic teams preparing 2026 budgets and three‑year roadmaps, the proprietary outputs in the full study — including plant maps, SKU margin curves, and a shortlist of actionable M&A targets — will convert insight into transaction‑ready plans.
Access and next steps
To obtain the complete dataset, segmentation tables, and the interactive forecast model, please visit the PW Consulting report page or contact our Processed Vegetable practice lead. The summary here provides a strategic orientation; the full report supplies the operational playbooks and numerical evidence you will need to act decisively in 2026.
For detailed analysis of this topic, please visit the official page: Processed Vegetable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com