

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Household Solid-State Relay Market to Expand at a 7.66% CAGR, Fueling Smart Home Power-Control Growth

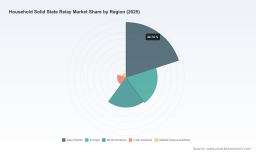
Household Solid State Relay Market: Strategic Imperatives for 2026 — PW Consulting Executive Brief
As households worldwide accelerate their adoption of smarter, quieter and more energy-efficient electrical systems, solid state relays (SSRs) have transitioned from niche components to strategic enablers across appliances, lighting and HVAC control. PW Consulting’s latest Household Solid State Relay Market report (base year 2025; historical coverage 2020–2025; forecast 2026–2032) frames the market opportunity and risk landscape that corporate leaders must incorporate into 2026 strategic planning cycles.
Household Solid State Relay Market
Why this market matters now
Between 2020 and 2025 the household SSR market expanded materially — rising from approximately USD 305 million to USD 430 million — reflecting a convergence of product-level drivers (noise-free switching, longer service life, miniaturization) and system-level trends (smart home integration, electrification of household functions, tighter energy-efficiency standards). Our forecast shows the market continuing to expand to roughly USD 721 million by 2032, representing a 7.66% compound annual growth rate across the 2026–2032 forecast horizon. That trajectory positions SSRs as a high-priority component class for OEMs, component suppliers and integrators focused on household electrification and energy management.
Household Solid State Relay Market
What PW Consulting’s report delivers (actionable, operational intelligence)
- Strategic market sizing and trend narratives that translate macro growth into product and program priorities for 2026.
- Competitive value-mapping and supplier scorecards that evaluate performance across technology, thermal management, form factor and compliance risk (no proprietary split data published here — full scorecards are available in the report).
- Supply chain stress tests and scenario planning tools that model tariff shocks, raw-material constrictions and licensing controls, and quantify tactical hedges (inventory, dual-sourcing, nearshoring).
- Go-to-market playbooks for appliance OEMs, smart-home platform providers and electrical distributors to accelerate design-ins — including reference design checklists and BOQ (bill-of-material) rationalization frameworks.
- M&A and partnership roadmaps identifying capability adjacencies (thermal subsystems, integrated power modules, embedded sensing) most likely to deliver differentiation in household use-cases.
- Regulatory tracker and compliance templates to operationalize responses to export controls, tariffs and critical-minerals policy moves.
Competitive landscape — who matters and why
The household SSR market is neither hyper-consolidated nor atomized: the top three vendors account for a meaningful share of the market while the top five approach half of sector revenues — a structure that favours both scale players and specialized innovators. This mixed concentration profile creates space for strategic plays across pricing, product differentiation and channel partnerships.
Household Solid State Relay Market
- Omron Corporation (Kyoto, Japan) — A broad product portfolio spanning compact PCB-mount and panel-mount SSRs. Omron is particularly relevant for appliance manufacturers seeking proven temperature-control and small-load switching building blocks.
- Panasonic Corporation (Osaka, Japan) — Strong in optoelectronic PhotoMOS and low-power SSRs; a natural partner for consumer-electronics routes-to-market where silent switching and space-constrained PCB footprints matter.
- Carlo Gavazzi Holding AG (Steinhausen, Switzerland) — Offers rugged DIN-rail and panel-mount devices tailored to building automation and HVAC, including integrated thermal management solutions for higher continuous loads.
- Sensata Technologies (Crydom) (Attleboro, USA) — Industrial-grade SSRs with features like zero-cross switching; attractive to OEMs that require high reliability and low noise in residential environments.
- Schneider Electric SE (Rueil-Malmaison, France) and Siemens AG (Munich, Germany) — Each brings modular systems and integration pathways into smart-home and building-management ecosystems, prioritizing interoperability and serviceability.
- ABB Ltd , TE Connectivity , Vishay Intertechnology , Littelfuse , Celduc Relais and Fujitsu — These suppliers together span the landscape from high-cycle, vibration-tolerant components to compact, low-power PCB SSRs for consumer devices, enabling a spectrum of differentiation strategies for OEMs.
Recent vendor activity underscores the pace of product and go-to-market evolution. Notable examples include Sensata’s fourth-generation SSRs (2025) with improved thermal performance and electrical isolation, Omron’s 2025 showcases of AC/DC high-power solid state relay variants for renewable and control applications, and multiple Chinese manufacturers exhibiting advanced SSR solutions at trade events in early 2026. These moves point to intensifying competition on thermal design, reliability, and application-specific packaging.
Supply chain and policy dynamics that will shape 2026 decisions
Two interlinked structural issues require board- and C-suite attention:
- Raw-material concentration risk — Production of key inputs for optocouplers and power semiconductors is regionally concentrated. For example, low-purity primary gallium production is highly centralized, creating single-point-of-failure exposure for certain SSR components used in household devices.
- Policy and tariff volatility — Policy shifts are already increasing landed costs and complicating sourcing strategies. Measures such as elevated tariffs on semiconductor components and executive actions targeting processed critical minerals have introduced new operational constraints and compliance burdens for global supply chains.
Collectively, these factors increase the importance of proactive supply-chain design: dual-sourcing strategies, qualified alternate chemistries where feasible, longer lead-time hedges for critical components, and scenario-based cost modeling for procurement and pricing teams.
Key strategic moves for 2026 (prioritized)
- Prioritize supply resilience — Quantify exposure to concentrated raw-material sources in component BOMs; implement dual-qualification programs and strategic inventory thresholds for critical semiconductor inputs.
- Design for environmental and regulatory robustness — Accelerate product roadmaps emphasizing thermal efficiency, higher isolation voltages and compliance to anticipated import/export scrutiny; these attributes will ease customer adoption and reduce aftermarket risk.
- Segment product stacks — Rationalize portfolios into core, adjacent and experimental offerings. Allocate R&D and manufacturing dollars to form-factors and thermal solutions where unit economics and adoption curves are most favorable.
- Commercialize system-level value — Position SSRs not as discrete components but as modules within appliance and HVAC subsystems that deliver quieter operation, lower warranty costs and energy savings — this supports value-based pricing.
- Hunt partnerships and tuck-ins — Target acquisitions or JVs that add thermal management, power-module integration or embedded sensing; these capabilities shorten time-to-market for higher-value system modules.
- Operationalize regulatory intelligence — Implement a compliance dashboard to translate tariff scenarios and export-control developments into P&L-sensitive actions (e.g., re-routing, supplier renegotiation, localization).
How PW Consulting’s report supports implementation
Our report is structured to move decision-makers from insight to execution. Deliverables include:
- Board-level briefings and scenario decks built from our forecast and regulatory trackers.
- Supplier risk heatmaps and a prioritized mitigation playbook tailored to your BOM exposure.
- Technology comparison matrices that map vendor strengths to household use-cases and show gaps you can address via targeted R&D or procurement strategies.
- Commercial tools — negotiation playbooks, channel-entry templates and TCO models — that translate product capability into distributor and OEM contract terms.
Importantly, the report purposefully omits publishable granular splits for certain proprietary subsegments in this public brief. That detailed segmentation, full vendor scorecards, and the interactive scenario tools are included in the subscription package and online report portal for clients and authorized stakeholders.
Immediate next steps for executives
- Commission a rapid SSR exposure audit across product lines and suppliers during Q1–Q2 2026 to identify single-source risks and thermal margin deficits.
- Embed a two-tier sourcing policy for high-risk inputs with qualification timelines and decoupling triggers tied to policy events (tariff changes, export-control licensing updates).
- Revisit product roadmaps to prioritize SSR-enabled value propositions (silent operation, lower warranty exposures, reduced energy consumption) and align commercial messages to energy and smart-home integrators.
- Explore targeted M&A or partnership opportunities to close capability gaps in thermal systems, integrated power modules and sensing — PW Consulting’s report includes a short-list of candidate capabilities and archetypal acquisition metrics.
Concluding perspective
For manufacturers, suppliers and systems integrators operating in the household electrification space, solid state relays are more than a component category: they are a leverage point for product differentiation, operational resilience and new-value capture. With a market expanding from the low hundreds of millions in 2020 to an expected market approaching three-quarters of a billion USD by 2032, companies that pair product innovation with disciplined supply-chain and regulatory strategies will secure disproportionate advantage.
PW Consulting’s Household Solid State Relay Market report is designed to be the operational handbook for that transition — providing proprietary segmentation, vendor benchmarks, regulatory scenario models and commercial tools to inform 2026 strategy decisions. For access to the full dataset, interactive tools and tailored executive briefings, visit our report portal or contact your PW Consulting representative.
For detailed analysis of this topic, please visit the official page: Household Solid State Relay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com