

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Maritime Missile Launch System Market Poised to Expand at a 7.12% CAGR Through 2032

Maritime Missile Launch System Market 2026: Strategic Preview for Decision‑Makers
Executive snapshot
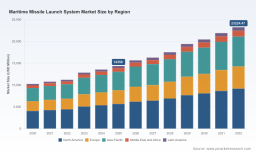
As geopolitical uncertainty and naval modernization programs accelerate, maritime missile launch systems have moved from niche capability purchases to core fleet-planning priorities. PW Consulting’s new Maritime Missile Launch System Market report—anchored on a 2025 base year—quantifies that shift. The global market expanded from roughly USD 10.3 billion in 2020 to an estimated USD 14.35 billion in 2025, and is projected to grow to about USD 15.66 billion in 2026, continuing at a compound annual growth rate (CAGR) of 7.12% through the 2026–2032 forecast window, reaching an anticipated USD 23.22 billion by 2032.
Maritime Missile Launch System Market
This press release outlines the report’s strategic value for enterprise and public‑sector decision-makers preparing procurement, R&D, M&A, and industrial policy actions in 2026. It presents high‑level takeaways and actionable implications while preserving the granular segmentation and proprietary models that constitute the report’s core—available through the full report portal.
Maritime Missile Launch System Market
Why this matters for 2026 planning
-
Momentum and scale: The market’s steady mid‑single‑digit CAGR masks heterogeneous pockets of demand and technology differentiation—factors that will determine winners and losers in upcoming procurement cycles. For strategic planners, the headline growth converts to expanded budgets and stretched supply chains that require proactive management.
Maritime Missile Launch System Market -
Concentration and competitive dynamics: Market concentration is material—our analysis shows the top three incumbent groups capture over 60% of market revenue, and the top five approach nearly 79%. This concentration underwrites predictable supplier behavior but raises acquisition and substitution costs for buyers exploring vendor diversification.
-
Timing is critical: 2026 represents an inflection year where near‑term deliveries, upgrade contracts, and interoperability initiatives (notably accelerated under recent alliance arrangements) will lock in platform capabilities for the next decade. Companies that align R&D pacing, supply chain agreements, and partner networks to those delivery pipelines will secure differentiated runway.
What the full report delivers (practical, usable outputs)
-
Investment-grade market model: A calibrated topline forecast with scenario variants (baseline, accelerated‑procurement, constrained‑supply) and sensitivity analyses tuned to commodity swings, export controls, and alliance‑driven procurement uplifts.
-
Procurement pipeline and timing map: Program schedules and decision‑points for shipyards, navies and prime integrators that help planning teams prioritize bids, capacity investments, and offset negotiations across 2026–2032.
-
Competitive playbooks: Vendor‑level benchmarking (technology footprint, integration capability, program backlog, partner ecosystem), win/loss archetypes and go‑to‑market motions tailored to primes, subsystem suppliers and emerging challengers.
-
Supply‑chain stress tests: Component‑level risk modelling, including raw‑material exposure, single‑sourcing vulnerabilities, and time‑to‑certification overlays, with recommended mitigation steps and contract language to protect schedules and margins.
-
Regulatory and export roadmaps: Practical guidance for navigating export control regimes, offset regimes and alliance interoperability standards—complete with decision trees that operational teams can use when evaluating cross‑border partnerships in 2026.
-
Actionable M&A and partnership diagnostics: Criteria‑based screens to evaluate target attractiveness, integration risk, and synergies—backed by valuation sensitivities linked to program backlog and expected procurement cycles.
Competitive landscape—what the incumbents are doing and what it means
The market is dominated by an ecosystem of established primes with deep systems integration capabilities. Key players include BAE Systems, Lockheed Martin, Raytheon Technologies (RTX), MBDA, Naval Group, Leonardo, Thales Group and Saab—each bringing differentiated technology stacks and program footprints. Recent program movements highlight tactical shifts that matter to 2026 decisions:
-
Lockheed Martin completed delivery of VLS modules for a major destroyer program in late 2025, reinforcing its delivery credibility and near‑term revenue base.
-
BAE Systems secured an upgrade contract for allied destroyers in 2025, a signal that lifecycle upgrade markets will be a substantial addressable opportunity alongside new‑build orders.
-
MBDA’s showcase of VLS upgrades and Naval Group’s recent frigate launch illustrate active modernization programs in Europe—relevant for suppliers assessing platform integration demand and aftermarket growth.
For buyers and suppliers, these developments underline two strategic imperatives: first, align product roadmaps to integration requirements of platform primes and national navies; second, anticipate aftermarket and upgrade pipelines that can sustain margins beyond initial system supply.
Supply chain, materials and regulatory headwinds
Our industry monitoring shows three cross‑cutting dynamics that will shape procurement and production strategies in 2026:
-
Raw‑material volatility: Specialized high‑strength steels used in launch canisters have experienced price and availability shocks—our sources show recent double‑digit pressure points in specific supply lines. This requires buyers to embed material escalation clauses or to co‑invest in assured supply capacity.
-
Export controls and certification complexity: ITAR and comparable regimes continue to constrain transfers of key launch system technologies, limiting partnership options in several geographies. The net effect is longer lead times for cross‑border integrations and elevated compliance costs that must be budgeted into program proposals.
-
Geopolitical procurement drivers: Heightened Indo‑Pacific tensions and recent alliance initiatives have directly lifted procurement allocations in key partner navies, accelerating interoperability standards and creating windows of opportunity for suppliers that can certify cross‑ally compatibility rapidly.
Strategic recommendations for 2026 decision windows
-
For primes and system integrators: Prioritize interoperability and modularity. Invest incrementally in common interfaces and testbeds that reduce integration cost for allied navies; this is a multiplier effect in markets where alliance procurement is accelerating.
-
For component and materials suppliers: Lock in long‑lead raw‑material contracts and qualify alternate sources now. Where feasible, offer fixed‑price frameworks tied to verified supplier cohorts to improve predictability for integrators.
-
For private‑equity and strategic buyers: Focus on targets that bring niche technical differentiation (e.g., thermal management, canister life‑extension, single‑cell modularity) and proven pathway to prime certifications; these attributes command premium entry into long lifecycle upgrade markets.
-
For defense procurement authorities: Include lifecycle cost and upgradeability metrics in new‑build RFPs. Contestable upgrade clauses and shared‑risk development can unlock innovation while preserving sovereign access.
Use cases: Rapid decisions enabled by the report
Three example scenarios where the report is directly actionable for 2026 decisions:
-
A prime preparing a bid for a 2026 destroyer modernization can use our pipeline timing map to align margin commitments and supplier contracts to phased delivery milestones—reducing cost overruns and improving proposal hit‑rates.
-
An intermediate supplier can deploy our supply‑chain stress tests to quantify the benefit of vertical integration into critical alloy supply, and to build a business case for capex in 2026 that shortens lead times for key components.
-
An alliance procurement office can use the regulatory roadmaps and interoperability matrices to fast‑track certification strategies that preserve sovereign control while enabling allied logistics chains.
What we withhold here—and how to get it
Consistent with our “trailer” approach, this release highlights the analytical framework, strategic implications and executable recommendations that make the report a practical decision tool for 2026. To preserve the integrity of the commercial models and proprietary segmentation that buyers rely on, we have not published the detailed region‑by‑region or application‑level splits in this summary. The full report contains the granular segment tables, vendor share matrices, program‑level revenue schedules and downloadable models that support procurement and investment decisions.
Next steps
For immediate access to the complete dataset, scenario models and the vendor playbooks that underpin our recommendations, please download the full Maritime Missile Launch System Market report from the PW Consulting portal. The report is structured to be operational—from one‑page executive summaries for boardrooms to detailed, cell‑level models for program managers and M&A teams.
In a market where timing, supply assurance and interoperability will determine strategic positioning over the next decade, this report is designed to convert market intelligence into executable advantage in 2026.
For detailed analysis of this topic, please visit the official page: Maritime Missile Launch System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com