

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Connecting Rod Bush Market to Rise from USD 642.5 Million (Base Year 2025) to USD 835.3 Million by 2032 at 3.82% CAGR — Asia Pacific, Bronze Bushings and Passenger Cars Drive Growth; Top 5 Hold 58.6%

Automotive Connecting Rod Bush Market — Strategic Imperatives for 2026
PW Consulting today releases its latest industry brief on the Automotive Connecting Rod Bush market, anchored on a 2025 base year and covering historical performance (2020–2025) with a forward-looking forecast to 2032. Our analysis synthesizes engineering-level material science, supply-chain economics, regulatory change, and aftermarket dynamics into a pragmatic playbook for executives making strategic decisions in 2026. The market is exhibiting steady expansion — from approximately USD 595.6 Million in 2023 to USD 642.5 Million in 2025 — and is projected to continue growing at a compound annual growth rate (CAGR) of 3.82% through the forecast horizon, reaching an estimated USD 835.28 Million by 2032. This report is purpose-built to convert that trajectory into near-term choices that protect margin, preserve continuity, and create preferential positioning.
Automotive Connecting Rod Bush Market
Why this report matters for 2026 decision cycles
-
Sector-specific focus: Connecting rod bushings are small in unit size but pivotal in engine reliability and efficiency. As OEMs and Tier-1 suppliers wrestle with fuel-economy targets and lifecycle cost pressures, component-level improvements compound into measurable vehicle-level gains.
Automotive Connecting Rod Bush Market -
Timing: 2026 is a year of bifurcation — continued ICE volume in many markets coexists with accelerating electrification in others. Suppliers that align product, material, and aftermarket go-to-market strategies with nuanced regional and segment timelines will capture disproportionate value.
Automotive Connecting Rod Bush Market -
Actionability: Our deliverables include market-sizing, scenario-based forecasts, supplier benchmarking, and an executable checklist for product development, procurement, and M&A. The goal is to move leaders from strategic hypotheses to executable 12–36 month plans.
Macroeconomic and technical drivers
-
Engine efficiency and emissions regulation: Ongoing global fuel-efficiency and emissions standards continue to push internal combustion engine (ICE) manufacturers to reduce mechanical friction. Connecting rod bush designs that lower friction and improve durability contribute directly to meeting those standards — a persistent demand signal for advanced bimetal, bronze, and aluminum-alloy solutions.
-
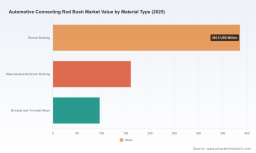
Material science and manufacturing economics: The prevalent materials mix—steel-backed bronze, high-tin aluminum alloys and brass variants—remains driven by wear performance, thermal properties, and cost. Small changes in alloy composition or backing technologies can materially affect lifetime cost and reliability, which in turn influences OEM sourcing strategies.
-
Aftermarket and maintenance cycles: The aftermarket continues to be a significant revenue pool, particularly where regulatory actions or service bulletins require part replacement. Repair kits and replacement part portfolios have become strategic levers for suppliers to improve margins and customer stickiness.
-
Supply chain volatility: Raw material price swings and capacity constraints in precision casting and machining create supplier risk. Dual-sourcing strategies, local buffer inventories for critical alloys, and near-term investments in precision machining capacity are among the most effective mitigation measures.
Market structure and competitive posture
The market exhibits moderate concentration: the top three players account for a meaningful but not dominant share of the global market (CR3 ~42%), while the top five firms climb to a higher share (CR5 ~59%). This structure creates a landscape where global leaders set technology and quality benchmarks, but regional specialists and niche manufacturers retain the ability to win on cost, speed, or specific OEM program relationships.
-
Global OEM-focused leaders: Companies with deep OEM ties and broad engine-component portfolios continue to win program-level business by packaging connecting rod bushings with other bearings and engine components. Their advantages are design-in capability, validation cycles, and established quality systems.
-
Specialists and regional champions: Highly specialized manufacturers with IATF/ISO certifications and precision machining capabilities can undercut on lead time and customization, especially for legacy platforms, industrial engines, and regional OEMs.
-
Aftermarket players: Firms that combine catalog breadth with distribution reach and repair-kit offerings can monetize service cycles, regulatory-driven replacements, and fleet maintenance programs.
Competitive snapshot — what to watch from leading suppliers
-
MAHLE GmbH (Stuttgart, Germany): A global engine-components leader with strengths in low-friction designs and OEM integration. Strategic focus: maintain technology leadership in bearing metallurgy and system-level engine partnerships.
-
Federal-Mogul Motorparts / Tenneco (Southfield, MI, USA): Deep aftermarket channels plus OEM bi-metal and tri-metal technologies. Strategic focus: leverage aftermarket footprint to upsell performance or repair kits.
-
King Engine Bearings (Jerusalem/various manufacturing locations): Known for high-performance bearings and pin bushings rated for extreme loads. Strategic focus: motorsport, high-performance OEMs, and specialty diesel markets.
-
K1 Technologies (Ohio, USA): U.S.-made small end bushings with strong positioning in country-specific legacy platforms. Strategic focus: tight tolerances for performance restorations and niche OEM programs.
-
China and India-based manufacturers (select players): Offer cost-competitive bi-metal and bronze solutions at scale. Strategic focus: capture aftermarket and regionally localized OEM business, while investing incrementally in quality certifications to climb the value chain.
Recent industry developments underscore the strategic importance of being operationally and commercially nimble. In March 2026, a regulatory airworthiness directive (FAA) required replacement of certain connecting rod bushings in specific aero engine series — an example of how regulatory action can create concentrated, time-sensitive demand. Product catalog and kit updates among aftermarket vendors during 2024–2025 further demonstrate supplier responsiveness to service-driven revenue opportunities.
Practical playbook for 2026 — three strategic moves
-
Lock in critical raw-material pathways and modularize designs. Short-term hedges for copper/brass and aluminum alloys, coupled with design modularity that reduces requalification time for material substitutions, will protect margin and delivery performance.
-
Prioritize aftermarket and repair-kit strategies where conversion cycles are visible. Regulatory-driven replacements or fleet maintenance programs produce concentrated demand that favors suppliers with distribution, SKU breadth, and rapid fulfillment.
-
Make targeted capacity bets on precision machining and surface-treatment capabilities. Investment in friction-reducing coatings, micro-texturing, and high-precision bore finishing yields product differentiation that becomes increasingly valuable as ICEs evolve for efficiency.
Corporate development and M&A considerations
-
Buy capabilities, not just capacity: Pursue acquisitions that add metallurgical expertise, advanced testing labs, or validated OEM program certifications rather than solely chasing tonnage.
-
Prioritize bolt-on assets in regions where service turnaround times and spare-part availability create competitive advantage. Geographic proximity to large installed bases accelerates aftermarket monetization.
-
Screen targets using a resilience scorecard: supplier quality, certification maturity, closing time for PPAP/PPF, and ability to dual-source critical alloys.
What our report delivers to inform your 2026 plan
PW Consulting’s Automotive Connecting Rod Bush Market report is built as an operational decision support tool. Core deliverables include:
-
Macro market sizing and scenario forecasts (2026–2032) reflecting technology, regulatory, and regional adoption pathways — anchored to the 2025 base year.
-
Competitive landscape mapping and supplier capability benchmarking across manufacturing, quality systems, and aftermarket distribution.
-
Regulatory and product-risk matrix (including relevant airworthiness directives and their commercial implications) to prioritize product and service responses.
-
Actionable procurement and sourcing playbooks, including a dual-sourcing template, inventory buffers, and technical qualification checklists to accelerate time-to-volume for substitute alloys.
-
M&A and partnership screening tools with prioritized capability targets and integration checklists tailored to buyers seeking to expand into higher-value segments.
-
Appendix of technology trends — coatings, microtexturing, and friction-optimized geometries — with guidance on expected efficiency payoff per engine program (kept at a summary level here; detailed models are available in the full report).
How to use this intelligence
For OEM program managers, the report translates component-level advances into vehicle-level fuel economy and warranty outcomes. For Tier-1 and Tier-2 suppliers, it provides a road map to allocate capital between capacity, R&D, and aftermarket channel expansion. For private equity and corporate development teams, it delivers a prioritized acquisition funnel and an integration playbook geared to extract synergies in metallurgical know-how and aftermarket distribution.
In 2026, the competitive wins will go to organizations that blend engineering rigor with commercial speed: the manufacturers that can validate new materials quickly, the distributors who can fulfill regulatory replacement waves promptly, and the buyers who manage supplier risk without compromising cost. PW Consulting’s report is designed to make those choices less uncertain.
Next steps
This release is an executive synopsis intended to demonstrate scope and methodological rigor while preserving the segment-level datasets and supplier scorecards that underpin actionable strategy. For access to the full dataset — including granular segment breakouts, supplier scorecards, and the downloadable forecasting model — please visit the PW Consulting report page or contact our industry team to arrange a briefing. Our analysts will walk through tailored scenarios and the specific levers that will move margin and market share for your organization in 2026.
For detailed analysis of this topic, please visit the official page: Automotive Connecting Rod Bush Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com