

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: IoT Security Solution for Unified Threat Management (UTM) Market to Expand at 22.15% CAGR, Rising from USD 6,285.2M in 2025 to USD 25,501.94M by 2032

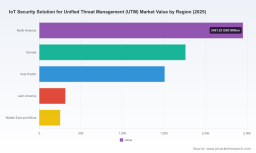
IoT Security Solutions for Unified Threat Management (UTM): Strategic Imperatives for 2026
Executive Overview
As enterprises accelerate connected deployments across factories, hospitals, campuses and smart cities, Unified Threat Management (UTM) platforms that can absorb the scale and diversity of IoT risk are moving from “nice to have” to mission-critical. Our new PW Consulting market study — with base year 2025 and a forecast horizon through 2032 — shows a sustained, high-growth trajectory (CAGR 22.15%) for IoT-focused UTM offerings, validating why security, procurement and architecture leaders must reframe their 2026 priorities around integrated, device-aware controls.
Iot Security Solution For Unified Threat Management Utm Market
To be clear: the macro market is expanding rapidly — the 2025 market base sits in the mid-single‑digit billions (USD, Million units basis), with a multi-fold expansion projected through 2032. This growth is driven by accelerating device density, regulatory pressure, and the operational need to consolidate tooling and visibility across hybrid estates.
Iot Security Solution For Unified Threat Management Utm Market
Why This Matters for 2026 Decision Makers
-
Strategic Timing: 2026 is a pivot year. With the EU Cyber Resilience Act fully rolling out and major data laws already in force across key jurisdictions, boards will expect demonstrable device security roadmaps. Investments in UTM capabilities now buy regulatory headroom as well as defensive depth.
Iot Security Solution For Unified Threat Management Utm Market -
Consolidation vs. Best-of-Breed Tradeoffs: Our concentration analysis indicates a moderately consolidated vendor ecosystem — top vendors control a meaningful portion of market share but there remains substantive room for differentiation and niche specialization. Procurement teams must weigh the benefits of broad, integrated platforms against specialized capabilities (for example, IoT profiling, lifecycle patching, and OT/IT segmentation).
-
Economic and Operational Levers: Rising infrastructure costs (notably data center construction and distributed compute) and supply-side pressures are changing TCO models. Buyers should model both capital and recurring operational costs when comparing appliance-centric, virtualized and cloud-native UTM options.
Report Highlights — Practical, Actionable Content
PW Consulting’s study is designed as an operational playbook for 2026 implementation. Highlights include:
-
Decision Frameworks: A practitioner-ready framework that maps organizational priorities (regulatory compliance, operational resilience, visibility, cost) to architectural choices (hardware UTM, virtual appliances, cloud SaaS).
-
Vendor Assessment Toolkit: A multi-dimensional vendor scoring model covering technical fit, integration maturity, support model, threat intel orchestration and financial sustainability — calibrated for IoT realities rather than generic enterprise networking.
-
Implementation Playbooks: Step-by-step roadmaps for device discovery, segmentation, policy migration, and incident response sequencing tailored to manufacturing floors, healthcare campuses and distributed retail footprints.
-
TCO and Risk Quantification Models: Scenario-based models that quantify upfront and run-rate costs alongside risk-reduction metrics (mean time to detection, containment window improvements), enabling CFO/CISO alignment on investment cases.
-
Procurement & Contract Guidance: Contractual clauses and service-level constructs that address firmware lifecycle, vulnerability disclosures, data residency and cross-border transfer obligations under emerging regulations.
Note: This article intentionally summarizes the report’s structure and strategic conclusions while withholding the granular segment-level forecasts, vendor rankings and pricing matrices that are available exclusively in the full report.
Competitive Landscape: Who Matters and Why
The UTM market for IoT security blends major networking and security vendors with specialist providers. The competitive set includes established incumbents known for integrated NGFW/UTM capabilities and newer entrants advancing cloud-native and AI-driven controls. Key players covered in the study include:
-
Fortinet, Inc.: Strong platform play combining NGFW and IoT-specific visibility/segmentation — appealing to enterprises seeking broad feature consolidation.
-
Cisco Systems, Inc.: Extensive portfolio across Secure Firewall and cloud-managed Meraki ecosystems, enabling hybrid deployments with deep device profiling.
-
Check Point Software Technologies Ltd.: Emphasis on prevention, policy enforcement and cloud posture integration relevant to multi-cloud IoT architectures.
-
Sophos Ltd. & WatchGuard Technologies, Inc.: Positioned for SMEs and managed service providers with simplified management and co-managed service models.
-
SonicWall, Barracuda, Juniper, Huawei, Palo Alto Networks: Each brings differentiated strengths — from appliance-focused performance and distributed firewalling to AI threat detection and Zero Trust enforcement — making vendor selection inherently contextual to deployment size and risk profile.
Recent industry moves underscore the pace of product evolution: new-generation firewalls incorporating Zero Trust Network Access (ZTNA), SASE converged platforms, and iterative UTM software updates were announced in 2026 — signaling that vendors are actively optimizing for co-managed services and AI-driven controls. These developments should influence procurement timelines; in many cases, a six- to twelve-month wait for next‑gen releases may be warranted if the feature set aligns with an organization’s strategic goals.
Regulatory and Cost Dynamics Shaping Buyer Priorities
-
Regulation as a Purchase Driver: The EU Cyber Resilience Act and the enforcement of the EU Data Act are elevating manufacturer liability and user data rights — making device lifecycle security and data portability contractual must-haves. Parallel rules in other jurisdictions (e.g., China’s data security regulations, U.S. bulk data controls) create compliance fragmentation that favors vendors with mature regional controls and data routing options.
-
Infrastructure Cost Pressures: Higher data center build costs and the growth of edge compute change where UTM processing should occur. Edge-friendly, resource-efficient virtual appliances and SaaS-delivered analytics reduce capital intensity but introduce new network egress and latency considerations.
Practical Recommendations for 2026
-
Adopt a Phased Consolidation Strategy: Start with discovery and segmentation pilots in high-risk device clusters, then expand policy-driven UTM controls while preserving the ability to integrate specialized tooling for deep OT/ICS use cases.
-
Insist on Lifecycle Guarantees: Contractually require firmware update commitments, vulnerability disclosure timelines and provenance controls — these are now procurement differentiators, not optional extras.
-
Leverage Co-Managed Models: For organisations lacking full-time IoT security expertise, co-managed and MSSP-backed UTM offerings accelerate time-to-value while retaining internal governance.
-
Align TCO to Risk Metrics: Use the report’s TCO scenarios to present clear ROI tied to risk reduction (e.g., reduced dwell time, avoidance of regulatory fines) for executive stakeholders.
-
Plan for Interoperability: Prioritize vendors that support open telemetry, standardized device profiling and API-first orchestration — these reduce lock‑in risk and enable hybrid deployments that mix cloud, virtual and hardware UTM elements.
How PW Consulting’s Report Helps You Win in 2026
Organizations that move beyond checkbox security and treat IoT UTM as a strategic capability will gain both risk and operational advantages. Our report is tailored to this reality: it combines granular market sizing, competitive benchmarking, regulatory scenario planning, and implementation playbooks into a single practitioner resource. For CIOs, CISOs, procurement leads and managed service operators, the study translates market growth and vendor evolution into executable roadmaps.
Remember: this article provides a high-level strategic view. The full PW Consulting report contains the detailed vendor scorecards, segment-specific forecasts, pricing and contract templates, and the precise models you need to finalize 2026 budgets and RFPs. Those granular insights are intentionally reserved for the full publication to ensure decision-makers have the actionable intelligence required to execute with confidence.
Next Steps
-
Download the executive summary and procurement checklist from our report portal to map our frameworks to your 2026 planning cycle.
-
Engage PW Consulting for a tailored vendor-selection workshop that applies our scoring model directly to your device inventory and regulatory constraints.
In an era where device proliferation multiplies attack surfaces faster than teams can hire specialists, the right UTM strategy — informed by market reality, regulatory foresight and practical implementation playbooks — is the difference between managed risk and disruptive incidents. Our 2026-focused guidance is built to help leaders choose decisively.
For detailed analysis of this topic, please visit the official page: Iot Security Solution For Unified Threat Management Utm Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com