

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Software Asset Management Managed Services to Rise from USD 1,475.78 Million in 2025 to USD 3,885.17 Million by 2032 (14.83% CAGR) — North America, Compliance Services and Large Enterprises Drive Growth as Top 5 Firms Hold 46.82%

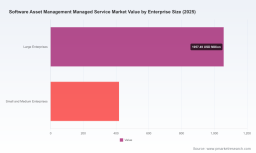
PW Consulting: Strategic Outlook — Software Asset Management Managed Service Market (2026 Preview)
As organizations enter 2026 with renewed focus on operational resilience, compliance, and cloud cost discipline, Software Asset Management (SAM) managed services have moved from niche optimization programs to board-level priorities. PW Consulting’s latest market research report — the Software Asset Management Managed Service Market — synthesizes six years of historical evidence and a forward-looking forecast to equip procurement leaders, CIOs, and CFOs with a pragmatic strategy playbook for 2026 decision-making.
Software Asset Management Managed Service Market
Why this report matters for 2026 decisions
Markets are shaped as much by regulation and enforcement as they are by technology. Between accelerating SaaS adoption, the proliferation of complex licensing models, and stronger privacy and cybersecurity obligations at state and federal levels, SAM managed services are now a linchpin for predictable IT spend and risk mitigation. Our findings show the SAM managed services market expanding materially over the past half-decade and projected to continue at a robust compound annual growth rate (CAGR) of approximately 14.8% through the forecast window. The market size trajectory underscores a strategic inflection point: buyers must decide whether to invest in auxiliary capabilities (data governance, vendor-license expertise, AI-enabled normalization) internally, or to execute via third-party managed services that blend tooling, practitioner depth, and contractual risk transfer.
Software Asset Management Managed Service Market
Headline market dynamics (evidence-based)
-
Scale: The market has more than doubled since 2020 and is projected to continue expanding throughout the 2026–2032 forecast period, reflecting sustained demand for license optimization, compliance assurance, and cloud/SaaS cost governance.
Software Asset Management Managed Service Market -
Concentration: Market concentration remains moderate. The top three and top five providers collectively account for a meaningful — but not overwhelming — share of activity, leaving room for specialized players and regional integrators to compete on technical depth and industry-specific offerings.
-
Service convergence: SAM is increasingly bundled with cloud cost optimization, FinOps practices, and SaaS management. Buyers are seeking integrated outcomes: compliance plus predictable unit economics for cloud and subscription spend.
-
Regulatory pressure: A growing patchwork of privacy and data-security laws (including numerous U.S. state privacy laws and national rules) and federal obligations affecting bulk data handling have raised the bar on how SAM data is discovered, stored, and processed — directly shaping vendor selection and contract design.
Operational realities shaping supplier selection
For 2026, our practical guidance to enterprise leaders centers on three decisions: (1) define the outcome set you need SAM to deliver; (2) decide how much control you must retain over sensitive data flows; and (3) choose the delivery model that balances cost with vendor license expertise.
-
Outcomes-first contracting — shift from time-and-materials to measurable outcomes (e.g., audit-readiness, subscription rightsizing, SaaS rationalization targets).
-
Data governance as a procurement criterion — vet providers on data residency, encryption at rest and in transit, role-based access, and incident response tied to SAM datasets.
-
Specialist skills matter — vendor-specific licensing expertise and experience with vendor audit playbooks continue to be a primary operational driver and cost center; buyers should insist on proof-of-work and practitioner accreditation.
What the PW Consulting report delivers (practical, executable content)
This report is purposely tactical. It is designed to guide the “what” and the “how” for 2026 implementation, while reserving granular market split tables and vendor scorecards for the full report to preserve the strategic value of the analysis. Key deliverables within the publication include:
-
Decision frameworks to align SAM objectives with cloud and FinOps governance — templates for executive alignment and KPI scorecards.
-
Procurement playbooks — RFP templates, evaluation criteria, and commercial guardrails for outcome-based pricing, SLAs tied to audit defense, and data-handling clauses required by modern privacy regimes.
-
Implementation roadmaps — phased approaches for discovery, normalization, optimization, and continuous compliance, including operational runbooks that teams can adopt directly.
-
Technology stack assessments — capability maps for discovery agents, normalization engines, license metric interpreters, and AI-enabled optimization modules; guidance on when to integrate best-of-breed SaaS management platforms vs. adopting larger managed service bundles.
-
Case studies and “war stories” — anonymized client engagements demonstrating audit defense, multi-vendor license consolidation, and SaaS portfolio rationalization, with before/after financial and operational metrics.
-
Risk and compliance checklists — a concise register tying state and federal regulatory obligations to concrete operational controls and contractual terms.
Competitive landscape — who to watch and why
The supplier field comprises several identifiable archetypes: pure-play SAM specialists, global licensing and resale leaders, systems integrators with SAM practices, and SaaS-first platforms that provide discovery and SaaS lifecycle management. Each archetype brings distinct advantages depending on buyer priorities.
-
Pure-play specialists — Anglepoint ( https://www.anglepoint.com) stands out for its deep, license-centric managed service offering and longstanding focus on visibility, optimization, and audit defense. Such providers are often preferred where vendor audit risk and legacy estate complexity are primary concerns.
-
Global license and resale leaders — SoftwareOne ( https://www.softwareone.com) combines broad licensing expertise with global delivery scale, pairing resale capabilities with managed services to serve multinational deployments.
-
Execution-focused delivery partners — Crayon ( https://www.crayon.com) offers a strong operational delivery model and often partners with other ecosystem players to execute large-scale transformations across licensing and SaaS optimization.
-
Systems integrators and professional services firms — Deloitte ( https://www.deloitte.com) and Insight ( https://www.insight.com) bring deep vendor-license expertise coupled with extensive systems integration capabilities and a broader IT services portfolio that supports enterprise-wide change programs.
-
SaaS management and platform specialists — Companies such as Zluri ( https://www.zluri.com) represent the SaaS-first approach, emphasizing discovery, subscription control, and lightweight governance that often appeals to rapid-growth and SaaS-heavy organizations.
-
Regional and hybrid players — Livingstone Technologies ( https://livingstone-tech.com) and Softchoice ( https://www.softchoice.com) exemplify vendors that combine licensing insight with region-specific execution and cloud enablement services.
Market recognition and industry signals reinforce these positions. Notably, Anglepoint, SoftwareOne, and Crayon have continued to receive vendor-recognition accolades, and Insight was named in a leading industry quadrant for execution and vision — signals that matter when evaluating a partner’s strategic commitment and investment in SAM capabilities.
Regulatory and risk environment: immediate implications
Recent regulatory developments materially affect how SAM data must be treated and where responsibility lies during audits and contractual disputes. Examples include the expansion of U.S. state privacy regimes and federal rules impacting bulk data handling. For 2026 procurement, this translates into a few non-negotiables:
-
Contractual liabilities must be clear on data custody and breach obligations tied to SAM discovery datasets.
-
Providers must demonstrate compliance with applicable state privacy laws and federal rules for bulk data transactions, including documented dataflow maps and controls.
-
Technical safeguards — encryption, access controls, and immutable logs — should be validated as part of security due diligence.
Practical recommendations for 2026 buyers
Based on the research and market signals, PW Consulting advises the following priority actions for organizations planning SAM engagements in 2026:
-
Start with an outcome profile: audit avoidance, subscription optimization, SaaS rationalization, or cloud cost governance — clarity here determines partner fit.
-
Include data-governance and regulatory compliance requirements as scored RFP criteria — not as add-ons. Ask for evidence, certifications, and sample dataflow documentation.
-
Favor providers that can demonstrate both license metric expertise and continuous delivery capability (not one-off projects) — proof points such as multi-year engagements and audit defense cases are valuable.
-
Consider blended delivery models: combine a specialist for audit and licensing depth with a cloud/FinOps partner for ongoing cost control.
-
Invest in internal capability uplift — train a small core team in vendor-specific license models and AI-enabled normalization; this increases bargaining power and reduces single-vendor dependency.
Where this article leaves off — and why you should read the full report
This briefing is intentionally high-level: it outlines market scale, the key dynamics shaping 2026 procurement, and the operational choices buyers face. PW Consulting’s full report contains the granular tools and the confidential analytical appendices that procurement teams will use when executing a SAM transformation — including vendor scorecards, regional and service-type segmentation tables, detailed financial scenarios, and model contracts. Those core items are reserved for the report to preserve their practical value for our subscribers and clients.
In an era where software spend and regulatory obligations are both rising, SAM managed services are not a cost center — they are a strategic risk-control and value-creation lever. The evidence is clear: firms that align governance, technology, and vendor strategy will materially reduce audit exposure, improve cloud economics, and create predictable IT spend profiles. For leaders preparing 2026 budgets and sourcing decisions, the full PW Consulting report is the operational manual you will reference throughout contract negotiation and implementation.
How to access the full intelligence
To obtain the full Software Asset Management Managed Service Market report, including detailed vendor assessments, segmentation matrices, and procurement templates, visit the PW Consulting research portal or contact our industry advisory team for a briefing. The actionable content within the full report is designed to be immediately usable by procurement, legal, and IT teams charged with executing SAM and SaaS governance programs in 2026.
For detailed analysis of this topic, please visit the official page: Software Asset Management Managed Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com