

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Intelligent Warehouse Market to Soar from USD 35,637.43 Million in 2025 to USD 78,783 Million by 2032, Forecasting a 12.04% CAGR

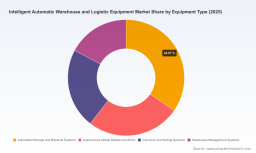
Intelligent Automatic Warehouse and Logistic Equipment Market 2026: Strategic Roadmap for Decision-Makers
Executive Preview
PW Consulting’s latest market study, Intelligent Automatic Warehouse and Logistic Equipment Market (base year 2025), arrives at a decisive moment for supply chain leaders and capital allocators. As the sector continues its double-digit ascent — growing from a global market of approximately USD 19.5 billion in 2020 to roughly USD 35.6 billion in 2025, and projected to expand at a compound annual growth rate (CAGR) of 12.04% across our 2026–2032 forecast horizon — 2026 will be the year when strategic choices made by C-suite teams crystallize into competitive differentiation or costly inertia.
Intelligent Automatic Warehouse And Logistic Equipment Market
Why this report matters to 2026 planning
-
Decision-grade synthesis: The study combines a multi-year historical base (2020–2025) with scenario-driven forecasts (2026–2032), translating broad market momentum into actionable signals for capital investment, procurement timing, and technology selection.
Intelligent Automatic Warehouse And Logistic Equipment Market -
Market structure clarity: Our analysis demonstrates that the market remains relatively fragmented (CR3 and CR5 metrics indicate limited top-tier concentration), creating both vendor choice complexity and opportunity for integrators and niche specialists to scale rapidly.
Intelligent Automatic Warehouse And Logistic Equipment Market -
Risk-adjusted planning: The report integrates cost-push factors (raw materials and tariffs), labor-cost dynamics, and regulatory/ESG pressures into a practical playbook for assessing project IRR, total cost of ownership (TCO), and operational resiliency.
High-level market trajectory
After an acceleration in adoption between 2020 and 2025, driven by e-commerce demand, labor constraints and the maturation of robotics and software, the intelligent automatic warehouse market is entering a consolidation phase in technology adoption. Our forecast anticipates continued robust expansion through 2032, underpinned by software-enabled automation, greater AMR/AGV deployment, and densification solutions that raise throughput per square foot. The sustained CAGR of 12.04% reflects both ongoing retrofit activity across legacy DCs and greenfield investments in high-growth regions and verticals.
Key demand drivers and headwinds
-
Labor substitution and productivity: Persistent labor shortages and rising wages are the primary proximate drivers for automation. Organizations are increasingly substituting capital for variable labor to stabilize fulfillment costs and service levels.
-
Technology maturation: Advances in AI, multi-agent orchestration, perception, and software-as-the-operating-layer are shifting procurement discussions from pure hardware toward integrated hardware-plus-software solutions.
-
Cost dynamics and supply-chain inflation: Raw material inflation — notably in steel and aluminum — and policy shifts such as increased tariffs have elevated project capital costs and extended vendor lead times. Buyers must now bake dynamic commodity and trade-risk scenarios into procurement timelines.
-
ESG and energy efficiency: Energy mandates and sustainability ambitions in developed markets are accelerating demand for regenerative drives, energy-optimized layouts, and lifecycle emissions transparency — all of which change the calculus for system selection and retrofit versus rebuild decisions.
-
Fragmented vendor landscape: A moderate level of market fragmentation creates negotiation leverage for informed buyers, but also increases integration risk if vendors’ software and control layers are not interoperable.
What the report contains (practical, operational content)
Designed for procurement officers, COOs, and investment committees, the study delivers hands-on tools and templates rather than academic generalities. Key deliverables include:
-
A calibrated market-sizing model and three scenario forecasts (base, upside, downside) with sensitivity to commodity, labor, and regulatory shocks.
-
Vendor benchmarking frameworks that evaluate end-to-end capabilities: hardware breadth, software maturity, integration experience, global delivery footprint, and lifecycle services.
-
Practical procurement playbooks: RFP templates, scoring matrices for technology vs. service trade-offs, and contracting guardrails to mitigate delivery and performance risk.
-
Implementation blueprints: Standardized timelines for greenfield and retrofit projects, prerequisites for warehouse digital twins, and phased roll-out approaches that protect fulfilment SLAs.
-
Financial tools: TCO calculators, payback and IRR scenarios, CAPEX-to-OPEX migration analyses, and maintenance-optimization strategies tuned to 2026 market conditions.
-
Actionable case studies and migration playbooks that map technology choices to specific operational KPIs (throughput, labor reduction, inventory accuracy, and energy consumption).
Competitive landscape — what buyers need to know
The ecosystem includes global integrators, robotics pure-plays, and specialized equipment manufacturers. Our strategic lens focuses on capability clusters rather than individual product claims, enabling buyers to align vendor selection with long-term platform strategy.
-
End-to-end integrators: Established systems houses with global delivery footprints are advantaged on large, high-throughput projects requiring tight mechanical, controls and software integration. Their strengths lie in turnkey project execution, proven engineering practices, and comprehensive service networks. Buyers considering mission-critical expansion or hub modernization will value these vendors’ ability to de-risk execution through scale and repeatability.
-
Robotics and AMR specialists: Innovators in mobile robotics and cube-based storage offer agility and rapid deployment for modular fulfillment environments. Their software-centric models enable flexible capacity scaling, and their product roadmaps increasingly prioritize multi-agent coordination and higher-level orchestration stacks.
-
Software-first challengers: A growing cohort emphasizes warehouse execution and orchestration software as the differentiation layer. These providers position themselves as neutral control layers capable of integrating best-of-breed mechanical subsystems — a model that appeals to buyers seeking vendor-agnosticity and future-proofing.
-
Regional and niche players: Local engineering houses and specialist OEMs continue to serve retrofit markets and specialized verticals where customized mechanical design and fast time-to-service are decisive.
Across these clusters, the 2026 purchasing decision will hinge on three vendor attributes: demonstrable integration experience, software maturity (including AI-based optimization), and lifecycle service economics. Our vendor profiles in the full report synthesize these attributes for leading suppliers across the ecosystem.
Recent industry signals and what they imply for 2026
-
Trade shows and forums (MODEX 2026 and Automate events) signaled consolidating themes: multi-agent AI, plug-and-play AMRs, and increased emphasis on software ecosystems. These product demonstrations suggest a shift from point-solution deployments to platform orchestration strategies.
-
Vendor technology updates highlighted investments in multi-agent systems for robot coordination — a trend indicating that performance gains will be captured through software-driven orchestration rather than incremental hardware upgrades alone.
-
Input-cost signals, including higher steel prices and trade-policy volatility, are compressing vendor margins and raising capital intensity. Buyers should expect longer lead times and consider inventory hedging or modular procurement to mitigate supply-side shocks.
Top strategic imperatives for 2026
-
Prioritize integration capability: Select partners with demonstrable multi-disciplinary project delivery and software interoperability to reduce vendor-switch and bespoke-integration risk.
-
Pursue staged deployments: De-risk large investments via modular rollouts that deliver early operational wins and allow iterative optimization of control software.
-
Embed commodity and policy scenarios into financial models: Include steel-price and tariff sensitivity in CAPEX planning and procurement cadence.
-
Optimize for energy and lifecycle cost: Given tightening ESG and energy-efficiency mandates, weight procurement decisions toward regenerative and energy-optimized solutions.
-
Lock in maintenance economics: Negotiate service-level guarantees and spare-parts agreements up front to stabilize OPEX and prevent post-deployment cost surprises.
Call to action
PW Consulting’s Intelligent Automatic Warehouse and Logistic Equipment Market report is structured to convert market intelligence into boardroom-ready actions. For procurement officers, operations leaders, and investors preparing 2026 budgets, the research offers a concise, risk-aware blueprint to navigate vendor choice, timing, and financing under persistent macro volatility.
To access the detailed segmentation, vendor profiles, case studies, and our interactive financial model — all withheld here to protect the strategic integrity of the full analysis — please visit our official report page for subscription and inquiry options. PW Consulting stands ready to support bespoke scenario workshops, vendor selection advisory, and implementation oversight to translate insight into measurable operational advantage.
For detailed analysis of this topic, please visit the official page: Intelligent Automatic Warehouse And Logistic Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com