

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Coronary Stents Market to Reach USD 10.76B by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-09
Coronary Stents Market — 2026 Strategic Brief for Corporate Decision-Makers
Executive summary
The global coronary stents market is entering a renewed growth phase that will materially shape strategic choices in 2026. Using 2025 as our analytical base year, PW Consulting’s market system model projects the market to expand at a compound annual growth rate (CAGR) of approximately 6.5% over the 2026–2032 forecast window. In dollar terms, the sector moves from roughly USD 6.9 billion in 2025 toward an expected market just above USD 10.7 billion by 2032, driven by a mix of product innovation, evolving reimbursement codes, and changing clinical practice patterns.
Coronary Stents Market
This brief synthesizes the strategic implications of that macro trajectory for executives considering R&D prioritization, regulatory timing, commercial footprint, or M&A activity in 2026. It highlights where returns are likely to concentrate, which competitive maneuvers are most consequential, and how to convert top-line growth into sustainable share gains — while deliberately withholding granular segment tables that appear only in the full report to preserve the “trailer” experience.
Coronary Stents Market
Why this analysis matters for 2026 decision cycles
- Investment prioritization: A mid-single-digit CAGR across the forecast period signals a market that is neither hyper-disruptive nor fully mature — ideal for targeted innovation bets rather than broad, unfocused capital deployment.
- Regulatory and reimbursement timing: Recent regulatory clearances and new procedure codes materially affect the value capture window for new stent designs. Firms that align PMA and clinical evidence timelines with reimbursement shifts will shorten time-to-revenue.
- M&A and portfolio shape: High market concentration among incumbent leaders creates both defensive and opportunistic M&A rationales: acquire narrow capabilities to defend clinical pockets, or snap up late-stage innovators to accelerate pipeline differentiation.
- Commercial strategy: With growth driven by complex lesions, deliverability and healing profiles, and procedural economics, go-to-market strategies must link product attributes to cath lab workflows and hospital contracting incentives.
What the full PW Consulting Coronary Stents Market report delivers (practical scope)
- Validated market-sizing model (historical 2020–2025, base year 2025) and scenario-based forecasts for 2026–2032, with sensitivity testing against adoption rates, pricing pressure, and regulatory events.
- Go-to-market playbooks for incumbent OEMs and disruptors: provider segmentation, reimbursement-mapped value propositions, hospital procurement levers, and physician adoption pathways.
- Regulatory roadmaps tailored to Class III PMA workflows, including timelines and evidence thresholds for CE mark extensions and FDA supplements.
- Commercial and pricing elasticity matrices that connect device attributes (polymer vs. metal, drug-eluting vs. alternative approaches) to purchasing outcomes in hospital systems and national payers.
- Clinical evidence gap analysis and recommended trial designs (endpoints, sample sizes, RWE integration) to maximize regulatory and reimbursement returns.
- Competitive intelligence dossiers on leading players, product-level differentiation, and tactical playbooks for defending or entering niche clinical segments.
- M&A screening tools: valuation benchmarks, integration risk checklists, and synergies calibrated to expected 2026 deal economics.
Competitive landscape and tactical implications
The coronary stents market exhibits meaningful concentration at the top: the three largest firms capture the majority of market share, and the top five account for an even larger portion. This structure shapes strategic choices in three ways — barriers to scale, premium pricing corridors, and the economics of specialization.
Coronary Stents Market
- Incumbent platform plays — Major global OEMs are doubling down on platform evolution rather than pure replacement. Product launches and polymer reformulations are designed to address deliverability, endothelial healing, and thrombosis risk, which are the primary clinical levers to command premium pricing and favorable guideline positioning.
- Specialist innovators — Smaller and regional players are focused on differentiated niches (bioadaptor designs, polymer innovations, covered stents, and regionally tailored cost-performance trade-offs). These specialists are attractive targets for bolt-on M&A or distribution partnerships.
- Recent market moves — Notable 2024–2025 events are already reshaping competitive dynamics: upgraded product clearances emphasizing faster healing and lower thrombosis risk, new FDA approvals for bioabsorbable polymer designs, and high-profile product launches for devices optimized for complex lesions. Firms that couple these clinical claims with robust RWE and payer engagement will accelerate uptake.
Key players to track include global leaders with strong platform roadmaps and evidence-generation capabilities, plus regional firms with clinically credible, lower-cost alternatives. Each type of competitor imposes distinct strategic responses — defend premium channels through evidence and training, while contest mid- to low-end volumes via cost competitiveness and distribution depth.
Regulatory and reimbursement dynamics shaping commercial strategy
- Class III device pathways remain the dominant regulatory route; PMA requirements and supplemental filings set the bar for new drug-eluting and novel polymer systems.
- Reimbursement frameworks are evolving: procedural coding updates and APC assignments influence hospital economics and the relative attractiveness of complex PCI cases. For example, new procedure-level codes introduced for complex multi-lesion or bifurcation interventions materially increase RVU credits for those cases, changing case-level profitability.
- National and regional payer decisions will increasingly require RWE demonstrating reduction in downstream events and total cost of care — not just per-device superiority.
Strategic imperatives for leadership teams in 2026
- Recalibrate portfolio investments: Prioritize product enhancements that demonstrably improve deliverability and healing metrics tied to real reimbursement benefit. De-prioritize projects without a clear linkage to hospital economics or payer value.
- Synchronize regulatory and commercial timelines: Structure clinical programs and PMA submissions to coincide with expected reimbursement code rollouts and hospital purchasing cycles to maximize early-adopter uptake.
- Invest in RWE and health economics: Fund targeted registry programs and health economic models that quantify reductions in readmissions or procedural complications — the levers payers and health systems respond to.
- Adopt a hybrid go-to-market: Combine direct specialty sales in premium markets with distribution partnerships and value-driven offerings in volume markets to optimize margin across the portfolio.
- Pursue bolt-on M&A selectively: Target niche technology owners with late-stage data or manufacturing scale in geographies where incumbents face access barriers.
- Ensure supply chain resilience: Build multi-sourced supply options for critical alloys and polymers; develop capacity contingency plans to avoid launch delays tied to materials scarcity.
- Develop physician-aligned value propositions: Integrate device-level advantages with training, procedural workflow tools, and outcomes dashboards to lower the adoption friction curve.
Risk scenarios and actionable monitoring KPIs
We model three plausible scenarios for 2026–2028 and recommend leading indicators for each.
- Base case (mid-single-digit growth): Continued adoption of next-generation drug-eluting systems and incremental shifts to bioresorbable polymers. Monitor quarterly adoption rates in major cath hubs, product-specific utilization, and payer coverage updates.
- Upside (accelerated adoption): Rapid uptake following favorable reimbursement adjustments (e.g., new complex PCI codes) and strong RWE showing reduced downstream events. Track RVU reimbursement realizations, hospital capture rates for complex PCI, and time-to-formulary inclusion.
- Downside (regulatory or reimbursement squeeze): Delays in PMA approvals, negative trial results, or reimbursement restrictions could compress pricing and slow growth. Watch PMA submission/approval timetables, adverse regulatory actions, and payer policy reversals.
How to use the full PW Consulting report (next steps)
For teams preparing 2026 strategic plans, this brief provides the directional context and senior-level recommendations. The full PW Consulting Coronary Stents Market report contains the detailed segmentations, country-level reimbursement models, product-level pricing curves, and downloadable financial models that operational teams require to build execution-ready plans.
Accessing the full report will enable you to: run tailored scenario analyses, extract TAM/SAM/SOM for specific product strategies, and apply our validated clinical adoption curves to your own portfolio. We intentionally withheld granular segment breakdowns here to ensure that your team engages directly with the full intelligence package — where raw data, methodology, and assumptions are fully documented for decision-grade use.
Concluding perspective
The coronary stents market in 2026 represents a strategic inflection point: moderate base growth provides expansive opportunity for targeted innovation, but success will be decided by firms that can synchronize regulatory, clinical, and reimbursement strategies while executing disciplined commercial playbooks. PW Consulting’s full market study equips executive teams with the models and tactical playbooks to convert the projected mid-single-digit CAGR into differentiated, durable market positions. For boards and leadership teams preparing 2026 capital allocation and M&A decisions, this is the intelligence set that converts market trajectory into executable advantage.
For detailed analysis of this topic, please visit the official page: Coronary Stents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electric Bike Market to Reach USD 147.22B by 2032, 10.54% CAGR: PW Consulting
By pmarketresearch, 2026-07-09
Electric Bike Market 2026: Strategic Imperatives from a Rapidly Scaling Industry
As decision-makers prepare budgets, partnerships, and product roadmaps for 2026, the Electric Bike (e‑bike) ecosystem presents a rare intersection of rapid consumer adoption, technological maturation, and shifting regulatory contours. PW Consulting’s latest industry study — anchored on a 2025 base year and projecting through 2032 — shows the market more than doubling from early‑decade levels and sustaining a compound annual growth rate (CAGR) of 10.54% over the forecast horizon. That trajectory creates both tangible upside and operational complexity for OEMs, component suppliers, fleet operators, and institutional buyers. This introductory brief distills the strategic takeaways executives must act on in 2026, while preserving the report’s proprietary, segment‑level detail for subscribers who require the full dataset and scenario models.
Electric Bike Market
Market Snapshot: Momentum and Scale
Between 2020 and 2025 the market expanded briskly, and our 2026 baseline confirms an inflection from niche adoption to mainstream mobility. The projected path through 2032 points to an industry that will be materially larger than today’s baseline, reflecting a convergence of urbanization trends, last‑mile logistics demand, and consumer willingness to trade car trips for e‑assisted cycling. For strategists, the headline metrics matter: the market’s mid‑teens growth profile over the forecast window is not driven by a single catalyst but by the cumulative effect of product diversification, falling unit manufacturing costs in many tiers, and increased institutional purchasing in new use cases such as cargo logistics and shared mobility.
Electric Bike Market
What This Research Delivers — Practical, Decision‑Oriented Outputs
- Quantified market sizing and top‑line forecasts at the global level with scenario sensitivity to commodity shocks, tariff moves, and regulatory shifts.
- Actionable go‑to‑market playbooks segmented by business model (D2C, channel partner, fleet), product archetype (folding, cargo, eMTB, commuter), and aftersales service models.
- Supply‑chain stress maps that prioritize vulnerability points (cells, BMS, controllers, hubs) and suggested mitigation pathways including dual‑sourcing, contractual hedging, and localized assembly levers.
- Commercial benchmarking and pricing ladders for entry, mid, and premium tiers — enabling margin modeling and SKU rationalization exercises.
- A competition database with strategic profiles, capability matrices, and recent product and market moves for leading players across geographies.
- Regulatory and standards playbook with compliance timelines and cost‑impact estimates for new battery and safety rules across key jurisdictions.
The study is deliberately designed to be executable: each chapter concludes with prioritized actions and one‑page executive checklists so leaders can translate insight into 90‑day and 18‑month plans.
Electric Bike Market
Why 2026 Is a Pivotal Year for Strategic Positioning
- From experimentation to scale: Market data indicate that e‑bikes are moving beyond early adopters into broader segments including utility and institutional fleets. This transition changes the economics of product reliability, service networks, and financing.
- Regulatory harmonization and fragmentation are simultaneous forces. New safety and battery standards reduce ambiguity in some markets while introducing compliance cost spikes elsewhere — a dynamic that favors firms with robust engineering and regulatory affairs capabilities.
- Supply‑side volatility: commodity price swings and tariff recalibrations in late 2025 and early 2026 materially affect component cost trajectories. Firms that locked minimum purchase commitments or adopted flexible manufacturing postures are already showing relative margin resilience.
Competitive Landscape — Who Controls the Narrative
The industry today is best described as moderately concentrated: leading incumbents command meaningful commercial scale, but the market remains accessible to focused challengers that can innovate on product, channel, or service economics. Our research profiles key participants across the value chain and assesses their strategic postures.
- Aventon (United States) — Strong in mid‑range and premium urban and adventure models, Aventon’s proprietary control unit and embedded connectivity position it well for value‑added services (fleet telematics, OTA updates). Their recent SKU introductions underscore a play for lifestyle and geographic expansion.
- Rad Power Bikes (United States) — Rad’s broad portfolio and emphasis on torque and range reinforce its position in commuting and utility segments. Their scale and direct‑to‑consumer channel economics remain a core advantage for growth in North America and beyond.
- Lectric E-Bikes (United States) — Competing on affordability, folding convenience, and compliance‑tested electrical systems, Lectric’s model is a case study in cost‑efficient urban penetration where entry price is the primary adoption barrier.
- Velotric (United States) — Velotric’s focus on performance and ergonomics for older adults and recreational riders creates a defensible niche that combines step‑through design with range optimization.
- Riese & Müller and Haibike (Germany) — These premium European players leverage deep integration with established powertrain partners and battery architecture expertise to capture high‑margin eMTB and cargo demand.
- Trek and Giant — Global incumbents with distribution breadth and manufacturing scale; their hybrid strategies (retail network, co‑branded tech integrations) make them formidable in performance and commuter categories.
- Eovolt (Netherlands) — Compact, design‑led folding e‑bikes for last‑mile urban mobility — a reminder that product form factor remains a potent differentiation axis.
Collectively, the competitive set reveals divergent strategic plays: scale plus channel strength, product‑led premiumization, and cost leadership in urban micro‑mobility. Our report includes relative capability maps, partnership fit assessments, and M&A themes that buyers and investors should watch in 2026.
Regulation, Commodities, and the New Operational Risk Map
Three contemporaneous dynamics are shaping near‑term risk and opportunity:
- Standards and safety updates: Regulatory bodies have accelerated battery and electrical safety standards. Firms selling into large regional markets must embed compliance into product development cycles to avoid market access disruptions.
- Tariffs and trade policy: Recent tariff adjustments have reweighted the incentives for localization versus import. The calculus for where to locate final assembly now depends on a more complex interplay of labor cost, lead time, and trade exposure.
- Raw material volatility: Sharp moves in lithium input costs in late 2025 and early 2026 have widened the margin variance between vertically integrated players and those reliant on spot component procurement.
For executives, this means rethinking sourcing strategies (long‑term offtake vs. spot buying), accelerating battery recycling and second‑life programs, and building certification roadmaps into new product development timelines.
Strategic Recommendations for 2026 Planning
- Prioritize modular architectures. Design with interchangeable battery and electronics modules to shorten certification cycles and reduce obsolescence risk, enabling faster market entry as standards evolve.
- Adopt a risk‑weighted sourcing playbook. Create tiered supplier relationships: core contracts for critical components, tactical partners for scale, and vetted single‑source contingency suppliers for rare parts.
- Monetize connectivity. Connectivity is no longer a “nice‑to‑have.” Build subscription services for fleet management, preventative maintenance, and telemetry to diversify revenue beyond unit sales.
- Segment go‑to‑market by use case. Urban commuters, cargo fleets, and recreational riders have divergent service expectations and lifecycle economics. Customize warranty, financing, and service offerings accordingly.
- Embed regulatory foresight. Allocate resources to standards engagement and pre‑certification testing; early compliance planning reduces time‑to‑market and prevents costly redesigns.
Report Access and Next Steps
PW Consulting’s full Electric Bike Market study includes the granular segment breakdowns, region‑by‑region forecasts, SKU‑level cost and margin matrices, and a searchable competitive intelligence database. The public summary here is intended to equip senior leaders with the strategic framing and near‑term imperatives required for 2026 planning. For teams that need the hard numbers — segmentation revenue by type, application, and region, scenario tables with sensitivity to tariff and commodity shifts, and executable playbooks tailored to specific business models — the full report provides those datasets alongside implementation templates.
In a market expanding at a double‑digit CAGR and facing rapid regulatory and supply surprises, the organizations that pair disciplined scenario planning with operational flexibility will capture disproportionate value. PW Consulting’s study is designed to be the playbook for exactly that shift: convert market momentum into durable advantage without exposing your organization to unnecessary compliance or supply risk.
How PW Consulting Can Help
- Custom strategy workshops aligned to your 2026 P&L and product roadmap.
- Tailored supply‑chain stress tests and hedging strategies.
- Partnership and M&A target screening using our proprietary scoring model.
Contact PW Consulting to request the complete Electric Bike Market report and to schedule a briefing with our senior analysts. The headline growth story is clear — the differential will be set by execution. Our work turns that execution into an evidence‑backed, risk‑calibrated plan.
For detailed analysis of this topic, please visit the official page: Electric Bike Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fire Pump Market to Reach USD 482 Million in 2025, Growing at 4.96% CAGR
By pmarketresearch, 2026-07-09
Fire Pump Market 2026: Strategic Imperatives for Executive Decision-Making
Executive summary
As organizations finalize capital plans and supplier strategies for 2026, the fire pump sector presents a measured growth opportunity shaped by regulatory rigidity, raw-material volatility, and concentrated vendor dynamics. PW Consulting’s latest Fire Pump Market study (base year 2025; historical series 2020–2025; forecast 2026–2032) synthesizes market sizing, scenario forecasts, and executable playbooks to help C-suite and procurement teams convert technical compliance and project-driven demand into defensible commercial outcomes.
Fire Pump Market
Why this research matters for 2026
Fire protection equipment is no longer a purely compliance-driven purchase. For building owners, EPC contractors, and industrial asset operators, fire pump selection affects lifecycle Opex, site reliability, and insurance cost profiles. The dataset underpinning our report shows the market expanding from a 2025 baseline to materially higher levels by the end of the forecast window—consistent with a mid-single-digit compound annual growth rate. Translating that macro growth into actionable decisions requires triangulating standards updates, supply-chain pressure points, and vendor capability differentials; that is precisely what our study delivers.
Fire Pump Market
Market outlook — the numbers that inform strategy
PW Consulting’s topline market sizing tracks a clear trajectory: steady recovery after pandemic-era disruption and a predictable ramp driven by refurbishment cycles, new construction, and specific industrial projects. The modeled forecast (2026–2032) uses a point estimate CAGR that reflects both demand-side drivers and supply constraints. These topline results form the backbone of scenario-based planning in our report, enabling finance and operations leaders to stress-test CapEx timing, spare-parts inventory policies, and supplier diversification plans across a range of plausible market states.
Fire Pump Market
Key dynamics shaping 2026 decisions
- Regulatory continuity with tactical change: NFPA 20 remains the dominant framework governing pump selection and installation; concurrent revisions and evolving certification processes (including updates to ASSE 15010 for inspection and testing) are forcing vendors and end-users to revisit acceptance testing protocols and maintenance contracts. These changes may drive short-term retrofit activity and alter service-contract scopes.
- Raw-material sensitivity: Steel price fluctuations have direct, quantifiable impacts on pump BOM costs and lead times. Procurement teams that modeled steel-price scenarios and hedged supplier agreements in 2025 found measurable protection against margin erosion in early 2026. Our study quantifies the pass-through sensitivity for common pump configurations and offers decision thresholds for switching procurement tactics.
- Project-driven concentrated demand: A number of large offshore and industrial projects awarded in recent quarters have temporary but significant effects on factory utilization and lead times. These episodic spikes make near-term supplier capacity and delivery performance as material to project economics as unit price.
- Service economics and digitalization: Manufacturers increasingly position monitoring and predictive maintenance services as margin-rich attachments. Buyers should evaluate total cost of ownership across both hardware and software/service bundles rather than comparing purchase price alone.
Competitive landscape — what executives must know
The market exhibits moderate concentration at the top: a small set of global manufacturers accounts for a meaningful share of revenue, with the three- and five-firm concentration ratios indicating that leading vendors maintain sizable—but not monopolistic—positions. This structure creates opportunities for mid-tier specialists and regional manufacturers to secure niches where local codes, rapid response, or tailored engineering matter most.
- Pentair (United States) — A global player offering both horizontal and vertical configurations through recognizable sub-brands; strong channel relationships in commercial and institutional projects.
- Grundfos (Denmark) — Integrates fire pumps into a broader pump portfolio; strengths in systems thinking and global aftermarket organization.
- NAFFCO (UAE) — Regional heavyweight that combines equipment and integrated fire-protection solutions for commercial and industrial projects across the Middle East.
- Flowserve (United States) and Sulzer (Switzerland) — Industrial incumbents with capabilities in engineered solutions and large-scale skid integrations, the latter having recently secured FPSO pump skid contracts that underscore its capability in oil & gas projects.
- Kirloskar Brothers (India) , SPP Pumps (UK) , Peerless Pump Company (US) , Armstrong Fluid Technology (Canada) , Rosenbauer (Austria) , Waterous (US) , CET Fire Pumps (Canada) , and Xylem (US) — A mix of specialist and diversified players that compete across segments defined by configuration, mobility (stationary vs. portable), and aftermarket service offerings.
Recent vendor activity highlights tactical shifts you should track: Armstrong launched a new constant-speed vertical-in-line series in early 2026 targeted at high-pressure applications across frequency markets; Sulzer’s contract awards in late 2025 for FPSO pump skids underscore how large energy projects can skew near-term orderbooks. These moves illustrate two trends: product refresh cycles aimed at specific use-cases, and project-level wins that reallocate supplier capacity.
What the PW Consulting study contains — practical, ready-to-use deliverables
Our report is structured to move readers from insight to action. It contains:
- Topline market sizing and an audit of the 2020–2025 historical period, anchored on the 2025 base year.
- Scenario-based forecasts for 2026–2032 with sensitivity to commodity inputs, regulation shifts, and project pipelines.
- Vendor scorecards that evaluate manufacturing footprint, lead-time reliability, aftermarket strength, digital offerings, and compliance track record.
- Operational playbooks for procurement and engineering: supplier evaluation matrices, clause templates for lead-time protection, and spare-parts stocking heuristics tied to pump configurations.
- Project-level case studies that unpack supplier selection in complex environments (offshore FPSOs, large commercial campuses, industrial retrofit programs).
- M&A and partnership heatmaps for corporates and PE investors identifying adjacencies and bolt-on targets.
- Financial models and executive dashboards to run “what-if” analyses (CapEx phasing, maintenance contract bundling, and warranty exposure).
To preserve strategic leverage for buyers and suppliers, this overview deliberately omits detailed segment-level breakout tables and region/application percentages. The full report provides those granulated views, enabling you to align procurement levers and investment timing to specific end-market exposures.
How leading organizations should use these findings in 2026
- Procurement leaders: Rebase supplier scorecards against the updated standards and raw-material scenarios; prioritize dual-sourcing for critical configurations and negotiate lead-time-linked price collars.
- Plant and asset managers: Reassess spare-parts stocks and service agreements in light of evolving inspection standards and the increasing role of remote monitoring to reduce downtime risk.
- OEMs and distributors: Differentiate with integrated services and modular skids to capture project-led opportunities and insulate margins from commodity-driven price pressure.
- Investors and strategics: Use the concentration metrics and vendor capability assessments to identify consolidation targets or strategic partnerships that accelerate entry into high-value niches (e.g., FPSO skids, portable foam systems, digital monitoring).
Risk matrix and early-warning indicators
Our report includes a concise risk matrix with leading indicators that should trigger tactical reviews in 2026, including unexpected commodity spikes, accelerated NFPA or ASSE regulation changes, or a cluster of large project awards in a single supply region. Monitoring these indicators allows teams to convert reactive firefighting into proactive contingency execution.
Final note — the value of granular intelligence
The fire pump market in 2026 is a market of disciplined growth and tactical complexity: steady topline expansion provides opportunity, but winners will be those that translate standards, supply-chain realities, and vendor differentiation into robust procurement and product strategies. PW Consulting’s Fire Pump Market study provides the granular segmentation, vendor-level KPIs, and executable playbooks necessary to operationalize those insights. For organizations that need to refine supplier selection, de-risk project pipelines, or evaluate M&A, the full dataset and appendices in the report are essential.
Next steps
Access the full PW Consulting Fire Pump Market study for the complete set of segment-level breakouts, vendor scorecards, and downloadable financial models that support 2026 decision-making. The executive summary above highlights the primary levers and risks; the complete report converts them into executable plans.
For detailed analysis of this topic, please visit the official page: Fire Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Iron Ore Market 2026: Strategic Priorities and the Value of PW Consulting’s New Market Study
The global iron ore market is navigating a critical inflection point. After recovering from post‑pandemic volatility, the sector reached an estimated market value of USD 215.0 Billion in 2025 and, under the baseline trajectory modeled in our study, is projected to expand toward USD 344.8 Billion by 2032—reflecting a compound annual growth rate of 3.9% across the 2026–2032 forecast window. For corporate leaders making capital, sourcing, and commercial decisions in 2026, this study is designed to convert that macro trajectory into actionable strategy: reallocating capital, re‑sourcing feedstock, and repositioning to compete in a market shaped by concentrated supply, shifting trade policy, and evolving steelmaking technologies.
Iron Ore Market
Why this study matters for decisions made in 2026
- Clarity on near‑term vs. structural trends: The market is influenced by cyclical price swings and one‑off supply events that can obscure durable shifts—particularly the rising role of direct reduction iron (DRI) and pelletized feedstock linked to decarbonization. Our study separates transient noise from structural signals so executives can prioritize investments with multiyear paybacks.
- Concentration and counterparty risk: The market remains concentrated at the top end, requiring customer firms to rethink supplier exposure and contract design. Our analysis quantifies the competitive footprint of leading miners and translates concentration into practical counterparty scenarios.
- Policy and trade shock preparedness: Recent trade policy moves and tariffs have immediate commercial consequences for supply chains and landed costs. The study models tariff shock scenarios and their knock‑on effects to inform pricing, sourcing, and lobbying strategies.
- Capital allocation under uncertainty: With large new supply projects coming onstream and incumbent producers expanding capacity, CAPEX timing and optionality matter. We provide decision frameworks for phased investments and divestments tuned to price and demand scenarios likely to unfold from 2026 onward.
What PW Consulting’s Iron Ore Market Study delivers
- Macro market model: A bottom‑up demand and supply model calibrated to 2020–2025 historical data and projecting through 2032, with scenario toggles for demand elasticity, substitution, and technology uptake.
- Proprietary forecasting engine: Probabilistic price paths and volume scenarios that reflect capital schedules, probabilistic project deliveries, and policy shock matrices—built for integration into treasury and FP&A planning.
- Supply chain mapping: Route‑level analysis of mine-to‑port logistics, bottle‑necks, and cost drivers—delivered as an executive dashboard and a tactical playbook for procurement teams.
- Commercial playbooks: Negotiation templates and contract levers (indexing, quality premia, take‑or‑pay structures) tailored to both buyers and sellers, with play‑tested outcomes under each scenario.
- Project and asset tracker: A continuously maintained universe of greenfield and brownfield projects with milestone risk scores to support M&A, JV, or offtake decisions.
- Regulatory & policy impact modules: Policy stress tests, including tariff reimpositions and emission‑driven demand shifts, with suggested mitigation approaches for different stakeholder groups.
Competitive landscape: how the majors are reshaping the market
Understanding the strategies and execution of the major producers is central to forming competitive responses. The market’s top tier—dominated by the largest global miners—controls a significant share of seaborne supply, and their operational moves in late 2024 through 2026 have immediate implications for pricing, access to high‑grade product, and contractual leverage.
Iron Ore Market
- Rio Tinto Plc (London): Rio Tinto has delivered record Pilbara output and marked major milestones with first shipments from its Simandou project. These developments materially increase high‑grade seaborne availability and change the contestability of premium feeds.
- Vale S.A. (Rio de Janeiro): Vale’s recent production surge to a multi‑year high has tightened the competitive dynamic between Brazil‑based and Australian supply sources, altering lorry and rail logistics relationships and buyer bargaining power in certain corridors.
- BHP Group Limited (Melbourne): BHP’s sustained Pilbara production footprint and capacity optimization programs continue to underpin its global export strategy and cost position.
- Anglo American Plc (London): Anglo American’s premium concentrate output and project focus in South America and Africa underscore an intent to capture higher‑value product segments tied to steel decarbonization pathways.
- Fortescue Metals Group Ltd (Perth): Fortescue’s large‑scale Pilbara operations emphasize throughput expansion and the integration of brownfield efficiency gains as its competitive edge.
- Cleveland‑Cliffs Inc. (Cleveland): The strategic idling of select Minnesota mines and emphasis on stockpile management reflect a tactical approach to the North American cost curve and U.S. domestic demand trends.
- ArcelorMittal S.A. (Luxembourg): Vertical integration moves and new concentrator capacity in Liberia highlight the continued strategic interplay between mining investment and downstream steelmaking security.
Collectively, the top three producers account for roughly half of the seaborne competitive footprint, while the top five consolidate around 60%—a market geometry that favors scale, integrated logistics, and long‑dated offtake strategies. Our report explores how each major’s capacity trajectory and project milestones translate into commercial pressure points for buyers, traders, and mid‑tier producers.
Iron Ore Market
Market dynamics shaping near‑term decision imperatives
- Trade policy shocks: The restoration and step‑up of steel tariffs (notably a 50% tariff reinstatement in early 2025 in one large market) has immediate ramifications for import economics and reroutes global flows. The report models tariff pass‑through and competitive responses for impacted trade lanes.
- Price normalization and volatility: Spot unit values softened in 2025 relative to 2024, with the average imported fines price at Tianjin in the first nine months of 2025 notable for its decline. Our price scenarios stress‑test contractual portfolios across low, base, and upside cases.
- Domestic production shifts: Idling of mines and strategic stockpile drawdowns—such as those observed in North America—change the domestic supply cushion and create short‑run procurement stresses. We quantify the effective domestic availability gap and mitigation tactics.
- Decarbonization and feedstock mix: Accelerating adoption of DRI and shifting steel mill feed requirements are changing demand composition. The study maps feedstock quality requirements against supply readiness and investment pathways for pelletizing and sinter alternatives.
Scenarios and recommended executive actions for 2026
We present three actionable scenarios—Tariff Shock, Supply Surge, and Decarbonization Accentuation—each with a clear set of tactical responses. Below are distilled strategic moves that decision‑makers can initiate immediately:
- Re‑price and re‑structure offtake agreements: Adopt flexible indexing and corridor‑specific clauses to protect margins under tariff and price swings.
- Diversify sourcing and build optionality: Shortlist alternative supply partners and secure contingent logistics capacity to reduce single‑source exposure.
- Phase CAPEX with embedded triggers: Use staged investments with go/no‑go gates tied to price, demand, and regulatory milestones to limit downside while preserving upside.
- Hedge selectively: Combine physical and financial hedges evaluated against cash‑flow models in the report’s forecasting engine.
- Prioritize product quality and decarbonization readiness: Invest in pellet and concentrate compatibility for DRI markets, and negotiate quality premia into long‑term contracts.
- Engage on policy: Coordinate industry and government engagement where tariffs and trade policy materially alter the cost base of domestic steelmaking.
How to extract maximum strategic value from the study
For CFOs, the forecasting engine and stress tests provide forward cash‑flow envelopes to inform capital allocation and hedging. For Heads of Procurement, the supplier scorecards, logistics cost maps, and negotiation playbooks enable immediate renegotiation and contingency planning. For Strategy and Corporate Development teams, the project tracker and scenario playbooks identify priority M&A targets and partnership opportunities aligned to demand and decarbonization trajectories.
PW Consulting’s Iron Ore Market Study is intentionally structured as a decision support toolkit—combining authoritative macro forecasts, granular operational intelligence, and executable commercial playbooks. The narrative and executive dashboards are designed to be read in 60 minutes; the model and datasets are built to be integrated into your 2026 planning cycle.
Next steps
This article highlights the study’s strategic value and the principal forces shaping the iron ore market in 2026. To access the full set of datasets, interactive scenario models, supplier scorecards, and executable contract playbooks, consult the full report and downloadable dashboards on our source page. PW Consulting can also run an executive workshop to apply the report’s scenarios directly to your company’s balance sheet and strategic roadmap.
For detailed analysis of this topic, please visit the official page: Iron Ore Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Plasma Etch Market to Reach USD 344.8M by 2032 at 13.5% CAGR
By pmarketresearch, 2026-07-09
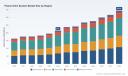
Plasma Etch System Market — Strategic Intelligence Brief for 2026 Decision-Makers
As companies finalize capital plans, supplier strategies, and regulatory compliance roadmaps for 2026, the Plasma Etch System market is entering a phase where technology choice, supply‑chain resilience, and regulatory readiness will determine winners and losers. PW Consulting’s new market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — provides the analytical scaffolding executives need to move from hypothesis to high‑confidence action.
Plasma Etch System Market
Why this research matters for 2026
-
Accelerating market growth with practical implications. The Plasma Etch System market has expanded steadily through 2020–2025 and, per our forecast framework, is set to accelerate during 2026–2032 at a compound annual growth rate of 13.5%. Translating that growth into procurement and R&D budgets requires granular scenario planning: buy vs. lease decisions on fab equipment, retrofit vs. greenfield capacity, and timing of technology upgrades for advanced nodes and heterogeneous integration.
Plasma Etch System Market -
Timing is strategic. With 2025 as the base year, the 2026 planning window is crucial for locking in pricing, lead times, and strategic partnerships. Short‑lead supplier engagements initiated in 2026 will influence production capacity and cost structures through the late 2020s.
Plasma Etch System Market -
Regulatory and input‑cost shocks require rapid adaptation. Volatility in critical specialty gases and tightening HFC/PFC regulations are already reshaping capital allocation and retrofit priorities. This report ties macro forecasts to actionable levers — what to accelerate, what to hedge, and what to defer.
Snapshot of market trajectory (select macro datapoints)
-
Historical growth: Our model captures the market evolution from 2020 through 2025, illustrating the recovery and structural expansion that preceded the 2026 decision window.
-
Near‑term sizing: Using 2025 as the base year, the market entry point for 2026 planning is explicitly modeled and validated against industry KPIs we track across equipment deployments, wafer starts, and CAPEX announcements.
-
Seven‑year outlook: Under the core scenario, the market expands at a 13.5% CAGR over 2026–2032, producing material addressable growth — a trajectory that justifies targeted investments in automation, emissions control retrofits, and specialty gas procurement strategies.
What’s inside PW Consulting’s operationally focused study
-
Market sizing and structured forecast (2020–2032) with scenario variants to stress‑test demand under different node‑transition and packaging adoption paths.
-
Technology landscape and roadmap: in‑depth treatment of ICP, RIE, DRIE and hybrid platforms with emphasis on manufacturability, throughput tradeoffs, and retrofit pathways for emissions reduction.
-
Supply‑chain vulnerability assessment: concentration and single‑source risks across high‑purity gases, chamber components, and custom RF subsystems, plus mitigation playbooks for procurement and contract design.
-
Regulatory impact modules: compliance cost modeling for AIM Act, EU F‑gas requirements and U.S. EPA emission factors, and practical retrofit sequencing to reduce emissions while maintaining uptime.
-
Commercial playbooks: vendor selection matrix, TCO templates, lease vs. buy calculators, and negotiation checklists tailored to OEMs, IDMs, and captive fabs.
-
M&A and partnership screen: candidate archetypes, valuation multipliers for software and service attachments, and integration risk matrices for roll‑up strategies.
-
Vendor profiles and benchmarking: comparative analysis of engineering capabilities, regional service footprints, and financial strength for the key equipment providers (feature summaries provided below).
-
Appendix: data sources, methodology, and a reproducible sensitivity model that allows client teams to substitute their own assumptions and produce bespoke forecasts.
Competitive landscape — what the analysis reveals
The supply base for plasma etch systems is globally distributed across specialist manufacturers and large semiconductor equipment groups. Market concentration metrics indicate a fragmented landscape (CR3 ~24.6%, CR5 ~26.2%), which has two strategic implications: procurement choice is broad, but scale matters for global service, spare parts, and rapid tool qualification.
-
Plasma Etch Inc. (Carson City, NV) — A niche supplier focused on surface‑preparation and RIE systems, including custom and refurbished models. Their flexibility and lower lead times make them a logical candidate for pilot‑line engagements and quick R&D iterations.
-
Plasma‑Therm LLC (Hauppauge, NY) — Known for premium wafer‑based etch and deposition equipment, with recent initiatives emphasizing scalable manufacturing for new application areas (notably quantum and advanced packaging). Their partnerships and content investments make them attractive for long‑term, co‑development relationships.
-
SPTS Technologies (KLA, Newport, UK) — A supplier of advanced platforms for silicon, dielectrics and compound semiconductor etch. SPTS is positioned for customers transitioning to heterogeneous substrates and who require tight process control at advanced nodes.
-
SAMCO Inc. (Kyoto, Japan) — Broad technology portfolio including high‑temperature PECVD and single‑wafer plasma systems. SAMCO’s recent product launches and trade show activity signal a push into higher‑temperature and specialty‑process segments, relevant for certain MEMS and compound‑semiconductor applications.
-
Trion Technology Inc. (Clearwater, FL) — Focused on etch, strip, and deposition solutions with particular strength in cost‑effective platforms for established logic and memory fabs.
-
Corial SA (Evry, France) — A European player emphasizing pilot‑line to production transfers. Their profile suits customers looking to localize production and de‑risk cross‑border supply chains.
-
GigaLane (Seoul, South Korea) — Regional supplier with growing capabilities for mainstream semiconductor fabs and expanding export footprints.
-
Tokyo Electron Limited; Applied Materials Inc.; Lam Research Corporation — Large OEMs that provide integrated fab solutions and have the service scale, financing options, and roadmap visibility required for advanced node and high‑volume memory customers. Their offerings are the default choice for major logic and memory IDMs, especially where system integration and long‑term support are non‑negotiable.
Recent industry developments that reshape 2026 strategy
-
SAMCO’s product moves (single‑wafer Aqua Plasma and 700°C high‑temperature PECVD) and their CS MANTECH presence underscore a pivot to high‑temperature and specialty processes. Firms planning pilot lines for MEMS, high‑power devices, or compound semiconductors should assess early access programs with SAMCO to compress time‑to‑qualification.
-
Plasma‑Therm’s 2025 review and partnership with quantum manufacturing players indicate that the market is beginning to monetize etch expertise beyond mainstream logic and memory — opening avenues for co‑investment in process development for emerging device classes.
-
Across the industry, tool suppliers are emphasizing service and retrofit packages (e.g., remote plasma chamber cleans) that materially reduce certain GHG emission factors and compliance costs. Procurement teams should treat these as differentiators, not optional add‑ons.
Regulatory and input‑cost dynamics every 2026 plan must address
-
Stringent HFC/PFC targets (e.g., AIM Act ambitions and EU F‑gas mandates) are forcing a shift toward lower‑GWP chemistries, emissions capture, and remote plasma clean strategies. These regulations will affect both equipment specifications and operating expenditures over the next decade.
-
U.S. EPA advancements — including demonstrated reductions in CF4 emission factors via remote cleans — create a clear retrofit pathway that can be modeled against non‑compliance penalties and carbon‑pricing scenarios.
-
Specialty gas supply volatility is a near‑term operational risk. For example, helium pricing has risen sharply in recent years, and limited domestic production of high‑purity gases in certain regions increases supplier risk. Companies must blend contractual hedging, dual‑sourcing, and local inventory strategies into their procurement plans.
Practical recommendations for 2026 planning
-
Embed emissions‑reduction upgrades into tool refresh cycles. Prioritize retrofits that reduce regulated emissions and secure compliance economics in CAPEX proposals.
-
Structure supplier engagements around service levels and spare‑parts SLA, not just purchase price. Given the fragmented CR metrics, the total cost of ownership and service coverage will differentiate suppliers.
-
Establish gas‑security protocols: evaluate dual‑sourcing, on‑site recovery, and contractual indexation to manage specialty‑gas exposure.
-
Create a two‑track R&D partnership approach: fast pilots with flexible, nimble suppliers for short‑cycle innovation; strategic co‑development with large OEMs for high‑volume, long‑lifecycle nodes.
-
Use scenario modeling to stress test capacity decisions against at least three demand paths (baseline, accelerated packaging adoption, and slower node transition) — the report’s reproducible models are designed for exactly this purpose.
How PW Consulting’s study supports executive decisions
Our report is explicitly structured to convert market intelligence into executable plans. It combines rigorous market-sizing (2020–2025 history; 2026–2032 forecast), vendor benchmarking, technical deep dives, regulatory cost modeling, and procurement playbooks. That combination enables cross‑functional teams — strategy, operations, procurement, and R&D — to align around a single, data‑driven plan for 2026 and beyond.
For senior teams ready to move from strategic intent to tactical execution, the complete study contains the detailed regional, type, and application splits, line‑item TCO models, vendor scorecards, and the scenario files referenced above. These granular datasets are intentionally gated to preserve the analytical integrity of the market model and to ensure clients receive a reproducible, auditable basis for board‑level decisions.
Next steps
-
Request the executive package to receive the reproducible forecasting workbook and vendor scorecards for internal stress‑testing.
-
Schedule a strategy workshop with PW Consulting to map the 2026 CAPEX cycle to emissions‑reduction investments and supplier contracts.
-
Engage on a short due‑diligence sprint if contemplating supplier consolidation or an M&A target in the plasma equipment space — our rapid diligence playbook compresses the timeline to decision.
PW Consulting’s Plasma Etch System Market study equips 2026 decision‑makers with the market context, risk‑adjusted scenarios, and commercial playbooks necessary to capture the next phase of growth while managing compliance and input‑cost shocks. For access to the complete dataset, vendor matrices, and reproducible models, contact our research team to obtain the full report and client briefing.
For detailed analysis of this topic, please visit the official page: Plasma Etch System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dashcam Market to Reach USD 344.8M by 2032 at 8.5% CAGR
By pmarketresearch, 2026-07-09
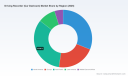
Driving Recorder (Car Dashcam) Market 2026 Outlook: Strategic Implications for Decision Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a forward-looking primer to our comprehensive Driving Recorder (Car Dashcam) Market study. This preview distills the macroeconomic trajectory, competitive dynamics, supply-chain stress points, and actionable options that matter for corporate decision-making in 2026 — while preserving the granular segment intelligence available only in the full report.
Driving Recorder (Car Dashcam) Market
Why this market matters in 2026
The driving recorder market has moved from a niche safety accessory to a strategic node linking vehicle security, telematics, ADAS integration, and fleet risk management. After a period of post‑pandemic recovery and product refresh cycles (2020–2025), the market expanded from the low hundreds of millions to an estimated USD 215.0 Million in our 2025 base year, and is forecast to grow at a robust compound annual growth rate (CAGR) of 8.5% through our 2026–2032 forecast window. By the end of the forecast period, the addressable market reaches roughly USD 345 Million — not an enormous absolute scale, but one with outsized strategic leverage for players who can convert hardware into data- and service-driven revenue streams.
Driving Recorder (Car Dashcam) Market
Key takeaways for 2026 corporate strategy
- Monetize beyond the device: Value is shifting from standalone hardware to recurring services — cloud storage, AI analytics, and fleet telematics. Companies that package subscriptions and analytics with hardware see higher lifetime revenue per unit.
- Platform partnerships trump point products: OEMs and fleet operators are increasingly demanding integrated camera + ADAS + telematics stacks. Strategic alliances or OEM supply agreements will accelerate adoption more than traditional retail channels.
- Supply-chain resilience is now a competitive moat: Memory and semiconductor availability are constraining output and driving cost volatility. Firms that secure long‑term allocations or vertically integrate critical sourcing will protect margins and delivery timelines.
- Regulation and national security considerations are shaping go-to-market routes: Export-control discussions and national security bills are increasing scrutiny on camera and chipset sourcing — a factor that impacts global distribution strategies and supplier selection.
Market dynamics: drivers, headwinds, and inflection points
Technology convergence is the primary growth driver. We see three parallel trends: image-sensor and computational upgrades enabling 4K/2K recording and low-light performance; embedded AI that powers driver coaching, object recognition, and event triage; and cloud connectivity that turns episodic recordings into longitudinal datasets for insurance, compliance, and predictive safety. These capabilities are being incorporated into both aftermarket products and OEM systems, creating cross‑pressure across channels.
Driving Recorder (Car Dashcam) Market
On the supply side, several material constraints and policy shifts are increasingly relevant for 2026 planning. Memory chip pricing surged dramatically since late 2025 due to AI data‑storage demand and allocation priorities among suppliers, while semiconductor lead times have spiked — with top-component lead times reaching levels unheard of in stable markets. Such constraints are not transient; they demand procurement redesigns, strategic buffer inventories, and sourcing diversification.
Policy and national-security trends add a layer of complexity. Legislative activity in multiple jurisdictions impacting export controls and critical-technology transfer increases transaction friction for vendors that rely on cross-border supply chains or cloud services hosted in geopolitically sensitive regions.
Competitive landscape — who matters and why
The market remains moderately fragmented: the top three incumbents capture roughly a third of market revenue, and the top five approach half. That concentration profile signals both opportunity and competition: there is room for regional specialists, differentiators built on AI and cloud services, and converged OEM solutions.
- Viofo (Shenzhen): Known for professional-grade imaging using advanced Sony sensors and multi-channel recording — strong in performance-conscious aftermarket segments.
- BlackVue / Pittasoft (Seongnam-si): Positioned at the premium end with cloud-enabled systems and parking-mode security — attractive for fleet and high-end consumer buyers seeking integrated cloud features.
- 70mai (Shanghai): Leverages AI and smart‑car integration to capture connected-device buyers and value-conscious consumers who prioritize intelligent features.
- Garmin (Olathe): Brings broad automotive electronics expertise, GPS integration and strong brand recognition — useful in channels where voice and navigation integration matter.
- Thinkware (Coquitlam): Competes in premium segments with ADAS integration, radar-assisted parking surveillance, and mobile connectivity — increasingly relevant as ADAS and dashcam functions converge.
- Vantrue, Nextbase: High-resolution recording and fleet-oriented product lines keep these vendors relevant across consumer and B2B fleets.
Recent product launches are accelerating capability expectations. Notable launches include Geotab’s AI-focused fleet camera and Thinkware’s flagship U3000 with integrated RADAR sensing and STARVIS 2 sensors — both underline the market shift toward sensor fusion, AI analytics, and fleet-grade reliability. BlackVue’s triple‑camera, cloud-compatible DR770X Box likewise strengthens parking-surveillance propositions for fleets.
Where the strategic battlegrounds will be in 2026
- Fleet telematics and safety services: Rapid risk reduction pilots and voice/alert systems are proving commercial value; fleet operators prioritize solutions that measurably lower insurance and accident costs. Expect procurement cycles focused on demonstrations of ROI, not just feature lists.
- OEM integration: Automakers are evaluating next‑gen front-camera modules that combine ADAS and recording functions. Suppliers with modular, certifiable camera+compute modules can win OEM slots and higher ASPs.
- Consumer ecosystem play: Subscription bundles that include cloud storage, theft protection, and behavioral coaching can transform unit economics for hardware-first vendors.
- Service differentiation via AI: Sophisticated analytics that triage events, reduce false positives, and enable automated claims handling will create stickiness and pricing power.
Practical implications — decisions to prioritize in 2026
- Procurement & sourcing: Reassess contracts for memory and SoC suppliers; secure allocation agreements, consider second-source qualification, and model buffer inventories into working capital forecasts.
- Product roadmap: Invest selectively in sensor fusion and onboard AI capabilities. Prioritize architectures that allow OTA upgrades and edge-cloud partitioning to enable future services.
- Commercial model: Build subscription pilots with insurers and large fleets to prove ARR pathways; use pilot results to shift channel incentives and reseller economics.
- M&A & partnerships: Target small AI analytics firms, telematics platforms, or regional distribution partners to accelerate service capabilities and market access.
- Regulatory & compliance: Establish a compliance function to track export controls and national-security legislation that could affect sourcing or cloud-hosting choices.
What PW Consulting’s full report delivers
This preview is deliberately selective. The full Driving Recorder (Car Dashcam) Market report provides the operative, transaction‑ready intelligence executives and investment teams need to act in 2026, including:
- Proprietary market-sizing with historical (2020–2025) validation and scenario forecasts (2026–2032) under multiple macroeconomic assumptions;
- GTM and pricing playbooks tailored for aftermarket, OEM, and fleet channels;
- Granular segmentation matrices across form-factor, functionality, and application — and an interactive sensitivity model for stress‑testing pricing and supply shocks;
- Detailed supplier maps and component-level cost curves to support sourcing negotiations and make-or-buy decisions;
- Commercial due-diligence templates, M&A target shortlists, and market-entry checklists;
- Risk heatmaps covering supply-chain, regulatory, and technological threats with mitigation roadmaps.
To preserve the research utility of the report, this preview omits the full segmentation tables and the detailed regional/application breakdowns that underpin our revenue forecasts. If your strategic questions require segment-level revenue, channel share, unit pricing, or a vendor-by-vendor supplier-capability comparison, the source report contains those datasets and the model files we use for scenario analysis.
Recommended next steps for executives
- Commission a short (4–6 week) commercial pilot with clearly defined KPIs (incident reduction, claims processing time, subscription uptake) if you are a fleet operator or insurer.
- For suppliers: embed component allocation clauses and negotiate lead-time protections with key vendors now; parallelize second-source qualification programs.
- For investors: request the full PW Consulting data room to evaluate M&A targets against our valuation sensitivity model — the market’s moderate concentration and rising services mix create attractive bolt-on opportunities.
- For OEMs and Tier‑1 suppliers: prioritize modular camera+compute architectures that support certification, OTA updates, and tiered service offers.
Concluding perspective
The driving recorder market in 2026 is small enough that nimbleness matters, and large enough that scale and platform plays pay. Hardware remains the entry ticket, but software, cloud services, and procurement sophistication determine margin capture. With a projected mid-single-digit to high-single-digit CAGR and concentrated but contestable leadership, companies that secure supply, build service economics, and form strategic partnerships will convert a modest market into a differentiated competitive advantage.
Access the full PW Consulting Driving Recorder (Car Dashcam) Market report for the segmentation detail, raw datasets, vendor scorecards, and execution playbooks that will make your 2026 decisions both defensible and actionable.
For detailed analysis of this topic, please visit the official page: Driving Recorder (Car Dashcam) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: EV Battery Market 2026–2032 — 3.82% CAGR Fuels Electric Mobility
By pmarketresearch, 2026-07-09
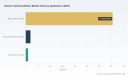
Electric Vehicles Battery Market: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As the automotive industry accelerates its transition to electrified mobility, the electric vehicle (EV) battery market is entering a phase defined by incremental growth, concentrated supply power, and disruptive technology inflection points. Our base-year analysis (2025) places the global EV battery market at approximately USD 77.0 billion, following a steady climb from the early 2020s. Under our central forecast, the market expands at a compound annual growth rate (CAGR) of roughly 3.8% through the 2026–2032 horizon, crossing the USD 100 billion threshold before the end of the forecast window. These headline figures mask meaningful differentiation beneath the surface — shifts in chemistry, manufacturing location strategy, feedstock volatility, and regulatory constraints that will determine winners and losers in 2026 and beyond.
Electric Vehicles Battery Market
Why 2026 is a pivotal year
-
Transition from volume-led to value-led competition: With headline market growth moderating versus the high-double-digit expansion of earlier years, 2026 will separate companies that compete on cost and scale from those capturing value through differentiated chemistries, fast-charge capability, safety, and integrated systems approaches.
Electric Vehicles Battery Market -
Regulatory and trade regimes are reshaping supply chains: Recent policy moves have created new sourcing and localization imperatives. Procurement teams and investors must evaluate compliance, tariff exposure, and the operational cost of localization when sizing facilities and negotiating offtake agreements.
Electric Vehicles Battery Market -
Material and technology inflection points converge: Surges in key commodity prices alongside rapid commercial rollouts of alternative chemistries force OEMs and suppliers to reassess technology roadmaps and risk exposures in 2026.
Market trajectory and what the headline numbers mean
Viewed as a whole, the EV battery market is continuing to expand but at a pace that rewards operational excellence, strategic positioning, and portfolio flexibility. The market’s progression from the low-60s billion USD level in the early 2020s to roughly USD 77 billion in 2025 — and onward toward a seven-figure growth milestone by the early 2030s — reflects a maturing industry where unit cost reductions, technology substitution, and aftermarket business models matter as much as unit volume.
For corporate strategists this implies three immediate tactical considerations: 1) prioritize investments that improve cost-per-kilowatt-hour on commercially relevant chemistries; 2) model scenarios where commodity spikes and export controls compress margins; and 3) set clear criteria for factory location and partnership choices that internalize regulatory and tariff risk.
Competitive landscape — concentrated and contested
The EV battery landscape in 2026 remains relatively concentrated among a handful of large, vertically integrated suppliers, with the top three players commanding a substantial share of market supply and the top five commanding a clear majority. This structure produces tight negotiation dynamics with OEMs, privileged access to large-scale capacity, and the ability for front-runners to subsidize R&D at scale.
Leading suppliers demonstrate complementary strategic approaches that define current best practices and emergent threats:
-
CATL (Ningde, China): Global market leadership driven by breadth of chemistry offerings — including LFP, NCM, and advanced formulations — coupled with rapid commercialization of sodium-ion and condensed cell formats targeted at range and fast-charge performance. CATL’s move into sodium-ion mass production and its latest Qilin and fast-charge products underscore a playbook that mixes scale, product differentiation, and aggressive commercialization timelines.
-
BYD (Shenzhen, China): Integrates proprietary cell and pack technologies with captive vehicle demand. Its Blade Battery narrative emphasizes safety and charging characteristics and provides a vertically coordinated advantage for both captive fleet deployment and third-party supply opportunities.
-
LG Energy Solution (Seoul, South Korea): Leverages large-scale cylindrical and pouch production with geographic diversification, notably expanded manufacturing in North America. LGES balances long-term OEM contracts with strategic capacity retooling to reflect shifting chemistry demand.
-
Panasonic Energy (Osaka, Japan): Continues to anchor cylindrical-cell leadership with multi-format programs for North American and global OEMs. Panasonic’s deep OEM partnerships and cell-format expertise make it a critical supplier in product architectures optimized around cylindrical formats.
-
SK On and Samsung SDI (Seoul, South Korea): Both firms combine chemistry R&D with regional expansion. Recent multi-year supply agreements from Samsung SDI highlight continued demand for high-performance cells for premium OEM programs.
-
EVE Energy and Northvolt: Represent targeted regional plays — one anchored in domestic prismatic technologies and the other emphasizing clean-energy production and European supply sovereignty — both attractive to OEMs pursuing differentiated sustainability and localization narratives.
Dynamics shaping 2026 decision-making
-
Regulatory tailwinds and headwinds: Policy changes in 2025–2026 have materially affected procurement strategies. For example, trade measures and sourcing conditions in major markets have altered the economics of imported cells and encouraged a reassessment of onshore capacity. Companies must model not just tariff rates but also the administrative and compliance costs associated with evolving incentive programs.
-
Material price volatility: The industry experienced marked swings in critical feedstocks. Cobalt supply constraints and policy actions in key producer nations led to sharp price movements, while lithium markets rebounded significantly in early 2026 compared to 2025 levels. These dynamics increase the value of supply agreements, downstream integration options, and alternative chemistry adoption.
-
Chemistry substitution and manufacturing reallocation: Large-scale retooling toward different chemistries — including reallocations toward LFP in 2025 — demonstrates that manufacturing footprints are now more plastic. Sodium-ion moving into mass production further expands the technology toolkit available to OEMs and fleets seeking cost-performance trade-offs.
-
Technology performance vectors: Range per charge, charge speed, safety characteristics, lifecycle degradation, and total cost of ownership remain the dominant decision criteria for OEMs and fleet operators. Recent product launches underscore a premium on fast-charge and condensed energy-density solutions.
Practical content included in our full report
The comprehensive PW Consulting market study is designed for executives who need to translate macro trends into executable 2026 plans. Key deliverables include:
-
Robust market sizing and scenario forecasts, with transparent methodology and sensitivity testing to alternative demand, commodity, and policy assumptions.
-
Supply-chain heatmaps and bottleneck risk scoring that identify critical nodes and contingency options.
-
Technology roadmaps and deployment timelines for incumbent and emergent chemistries, including commercialization timelines and cost curves.
-
Competitive intelligence dossiers for tier-1 suppliers — coverage includes commercial strategies, capacity expansion roadmaps, partnership matrices, and likely responses to OEM sourcing shifts.
-
Commercial playbooks for OEMs and investors: negotiation checklists, contract structures, offtake calibration tools, and go-to-market templates for captive vs. third-party supply strategies.
-
M&A and JV decision frameworks that prioritize value creation levers under different regulatory and commodity scenarios.
Recommended strategic actions for 2026
-
Lock flexible capacity and secure feedstock optionality: Structure offtake and supply agreements to preserve flexibility across chemistry formats and geographic sources; where possible, negotiate clauses that hedge against extreme commodity swings.
-
Prioritize modular investment in manufacturing: Favor modular, reconfigurable lines that enable chemistry switches without multi-year production gaps.
-
Build regulatory playbooks: Invest in capabilities to rapidly assess incentive eligibility, tariff exposure, and localization requirements; prioritize markets where policy alignment yields outsized total-cost advantages.
-
Differentiate through system-level integration: Suppliers and some OEMs will capture premium value by integrating thermal management, cell-to-pack designs, and differentiated warranties rather than competing solely on cell cost.
-
Stress-test partnerships and M&A with scenario-driven valuation: Use scenario P&L stress tests that incorporate raw material shocks and regulatory permutations — transact where synergies are resilient across these regimes.
Implications for corporate planners and investors
2026 will not be a year for passive portfolio allocations. The combination of moderate headline growth, concentrated supplier power, and disruptive material and chemistry shifts elevates the returns to active strategic management. Boards should expect procurement teams to present multi-scenario sourcing plans, CFOs to demand commodity-hedging strategies, and business development teams to prioritize partnerships that reduce execution risk.
For investors, the concentration metrics in the sector point to asymmetric opportunity: a small number of integrated suppliers will likely preserve margin and market access, while nimble challengers can win share regionally by aligning with local OEMs and sustainability narratives. The winners will be those who couple capital discipline with a clear play for pricing power, differentiation, or structural cost advantage.
Next steps — where to find the full intelligence
This article is a strategic preview intended to communicate the practical value of full, proprietary analysis contained in our Electric Vehicles Battery Market report. The complete study includes granular sensitivity models, a downloadable dataset, and a full competitive matrix that expands on the supplier dossiers summarized here. For procurement leaders, R&D heads, and C-suite decision-makers planning 2026 capital and commercial moves, the full report provides the actionable depth necessary to convert uncertainty into advantage.
Contact PW Consulting or visit our report page to access the full dataset and scenario-builders, and to schedule a bespoke briefing tailored to your portfolio and operational footprint.
For detailed analysis of this topic, please visit the official page: Electric Vehicles Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
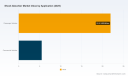
Shock Absorber Market: Strategic Outlook for 2026 Decision-Making
Executive summary
As PW Consulting’s lead industry analyst, I present a concise strategic preface to our comprehensive Shock Absorber Market study (base year 2025). The market has expanded steadily over the past half-decade, increasing from USD 21.47 Million in 2020 to USD 27.4 Million in 2025. Our forecast period (2026–2032) anticipates continued expansion at a compound annual growth rate (CAGR) of 5.0%, reaching roughly USD 38.55 Million by 2032 (all figures in USD Million). For 2026 corporate planning cycles, the implications are clear: steady topline growth accompanies selective disruption driven by electrification, adaptive systems, raw-material volatility, and tightening safety and emissions regulation.
Shock Absorber Market
Why this report matters for 2026 strategic planning
-
Timing: The 2026 planning horizon aligns with several regulatory and OEM product cycles that will determine supplier qualification and platform selection for the next generation of vehicles. Delays or misreads here can lock suppliers out of multi-year programs.
Shock Absorber Market -
Predictability vs. disruption: A predictable macro trajectory (5.0% CAGR) masks asymmetric risk. Material cost shocks, software-driven damping systems, and OEM-level system integration create windows for both margin compression and premiumization.
Shock Absorber Market -
Resource allocation: With a measured market growth rate, firms must choose between volume-led scale plays, targeted premiumization (adaptive/EV-specific dampers), or aftermarket expansion. Each choice demands different capex, R&D, and M&A profiles.
-
Competitive positioning: The market exhibits moderate consolidation—our concentration metrics indicate a fragmented landscape with the top three players accounting for approximately a quarter of value and the top five approximately one-third—creating opportunities for mid-tier players to pursue consolidation or niche specialization.
Key dynamics shaping supplier economics in 2026
-
Regulatory acceleration: Safety and emissions rules—both regionally specific and globally aligned—are increasingly influencing damper design. Regulatory moves such as new NHTSA guidelines and strengthened EPA GHG standards through model year 2026 create indirect support for advanced damping solutions that improve vehicle efficiency and active safety integration.
-
Technology shift: Adoption of adaptive, electronically controlled dampers (including AI-enabled tuning for EV platforms) is progressing from flagship models into high-volume segments. Suppliers who can deliver verified systems engineering and production-ready electronics/software stacks will secure higher margins.
-
Input-cost volatility: Steel and hydraulic fluid price inflation, exacerbated by sustained supply disruptions linked to geopolitical events, remain a near-term margin headwind. Cost pass-through mechanisms, hedging strategies, and material substitution will be key levers.
-
Trade and tariff dynamics: Preferential trade agreements and supply-chain realignments are enabling cross-border OEM-supplier collaboration; firms with flexible manufacturing footprints stand to benefit from reduced friction in trans-regional platform sourcing.
Strategic implications by corporate function
-
R&D and product roadmap: Prioritize modular platforms that support both passive and active damping architectures. Invest in validated control software and sensor integration to reduce system-level qualification timelines with OEMs.
-
Supply chain & procurement: Establish strategic hedges for key commodities and qualify alternate suppliers for hydraulic fluids and critical steel grades. Shorten lead-times for high-cost components via nearshoring where economically sensible.
-
Commercial & OEM engagement: Align product demonstrations around system-level benefits—fuel economy gains, NVH improvements, and safety compliance—rather than component specifications alone. Early engagement in OEM calibration cycles yields outsized program share.
-
M&A and corporate development: Given moderate market concentration, acquisitive growth can be achieved through targeted buys—capability gaps (electronics, software, EV-adapted dampers) offer the highest strategic uplift per dollar.
-
Aftermarket strategy: With passenger vehicle parc aging in several markets, differentiated aftermarket propositions (smart retrofits, digitally enhanced warranty & diagnostics) offer recurring revenue streams that cushion OEM cycle exposure.
What PW Consulting’s report delivers (practical content highlights)
-
Actionable demand model: A calibrated topline model from 2020–2032 (base year 2025) that allows scenario testing against commodity shocks, EV adoption curves, and regulatory trajectories.
-
Decision-ready playbooks: Function-specific recommendations for procurement, R&D prioritization, go-to-market tactics, and M&A screening filters tuned for 2026 execution.
-
Risk heatmaps: Short- and medium-term risk matrices covering input-price volatility, regulatory timing, and program de-risking steps for supplier qualification.
-
Commercial modeling templates: Margin and pricing impact simulators that show the sensitivity of profit pools to different product-mix and pass-through strategies.
-
Benchmarking and KPIs: Operational benchmarks for cycle-time to qualification, warranty rates, and manufacturing productivity that inform near-term operational improvements.
-
Executive-ready briefings: Summarized scenarios that map each strategic choice to likely market outcomes through 2032.
Competitive landscape—who matters and why
The competitive field contains global OEM suppliers and regional specialists. Leading names maintain broad OEM relationships and are accelerating capabilities in adaptive and EV-specific systems. Below is a high-level strategic read on the core players covered in the report:
-
KYB Corporation (Tokyo, Japan) — Global OEM scale in hydraulic shock absorbers and increasing investment in electronic suspension subsystems. Strength: deep OEM engineering relationships and global manufacturing footprint.
-
ZF Friedrichshafen AG (Friedrichshafen, Germany) — Focused on high-performance and adaptive dampers; positions itself as a systems integrator for OEM platforms, particularly where mechatronics and software play a role.
-
Tenneco / Monroe (Northville, Michigan, USA) — Strong aftermarket and light-vehicle OEM presence; recent product initiatives underscore a push to reclaim performance and comfort leadership.
-
thyssenkrupp Bilstein (Ennepetal, Germany) — Known for premium performance products with pronounced OEM and replacement market credibility; leverages technology cachet to sustain margin premium.
-
KONI B.V. (Oud-Beijerland, Netherlands) — Niche premium and motorsport-derived technology translated into road-car performance applications; a go-to for performance-calibrated dampers.
-
Showa Corporation & Hitachi Astemo (Japan) — Both investing in eco- and software-forward developments; Showa’s recent eco-hydraulic fluid announcement signals a sustainability push among component suppliers.
-
Mando Corporation (South Korea) — Emphasizing AI-enabled and EV-targeted adaptive systems; strong ties to domestic OEM programs provide a launchpad for global expansion.
-
Other relevant players — A mix of legacy brands and regional manufacturers continue to serve aftermarket and regional OEMs; their scale and proximity to localized supply chains make them meaningful in procurement and competitive scenarios.
Recent developments & near-term triggers
-
Product innovation: In March 2026, Monroe Ride Solutions announced advancements in passive damper valve technology that claim both improved ride comfort and handling—illustrative of the incremental innovation that will shape mainstream product cycles.
-
Sustainability push: Showa’s 2025 announcement of an eco-friendly hydraulic fluid highlights the dual pressures of regulatory compliance and customer demand for decarbonization across supply chains.
-
Regulatory and trade catalysts: New guidelines from NHTSA and tightened EPA GHG standards, coupled with trade agreements that reduce cross-border frictions, create both compliance obligations and new commercial pathways for suppliers able to scale regionally.
Risk profile and contingency considerations
-
Commodity shocks can rapidly compress margins in a market with moderate growth; proactive hedging and material-efficiency engineering are essential.
-
Software and electronic integration failure modes introduce program risk; suppliers must invest in systems engineering and supplier-of-record practices early in OEM timelines.
-
Geopolitical supply disruptions and sudden tariff shifts can upend sourcing strategies; flexible manufacturing footprint and alternative-sourcing plans are recommended.
Conclusion — how to act in 2026
For executive teams building 2026 plans, the choice is not between growth or protection—both are required. The market’s steady 5.0% CAGR through 2032 offers a predictable foundation, but the growth pathway will be uneven across technologies, channels, and geographies. Firms that combine disciplined supply-chain risk management, targeted investments in adaptive/EV-capable damping technologies, and commercially minded OEM engagement will convert a modest market expansion into outsized strategic returns.
PW Consulting’s full Shock Absorber Market report provides the detailed segment-level data, vendor benchmarking, and executable playbooks needed to convert these strategic imperatives into 2026 actions. For access to the complete segmentation, granular forecasts, and proprietary decision tools, please visit our report page or contact our strategy team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Shock Absorber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com