

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Market Insight: Vinylphosphonic Acid Market to Grow at 8.7% CAGR Through 2032
By pmarketresearch, 2026-07-09
Vinylphosphonic Acid Market — Executive Preview for 2026 Decisions
As global chemical supply chains stabilize after recent raw-material shocks, vinylphosphonic acid (VPA) is re-emerging as a strategic monomer and specialty intermediate across coatings, water treatment, fuel-cell membranes, medical polymers and niche functional applications. This executive preview, prepared by PW Consulting’s senior strategy team, synthesizes the report’s most consequential insights for boardrooms and investment committees planning 2026 priorities. It demonstrates how a compact set of macro metrics—anchored in a measured historical series and a robust forecast—translates into actionable choices on capacity, sourcing, product positioning and M&A prioritization.
Vinylphosphonic Acid Market
Why this market matters in 2026
From 2020 through the 2025 base year the VPA market showed steady expansion. Our top-line historical series indicates a recovery and re-rating of demand drivers into 2025, and we project continued momentum through the end of the forecast window. Specifically, the global market grew from a low-double-digit base in 2020 to a larger base by 2025 (base year) and is expected to follow an 8.7% compound annual growth rate in the 2026–2032 forecast period. By 2032 we project the market to approach nearly three times the size of the early-2020s baseline in nominal USD terms, underscoring meaningful commercial upside for firms that time capacity, product quality and go-to-market correctly.
Vinylphosphonic Acid Market
What the full report delivers — practical, transaction-ready intelligence
- Market-sizing and forecast methodology with transparent assumptions, sensitivity analysis and upside/downside scenarios tied to raw-material price paths and regulation stress tests.
- Segment-focused playbooks (by product-grade, end-use cluster and value-chain position) that translate demand curves into required manufacturing scale, quality controls and pricing strategy.
- Supply-chain heatmaps and risk scores that quantify exposure to phosphorus-based feedstock volatility and logistics constraints.
- Competitive benchmarking and capability matrices for incumbent producers and emerging regional players, mapped against certification, grade breadth and downstream application wins.
- Regulatory impact matrix with cost-to-comply estimates for hazardous-chemical storage, transportation and environmental reporting—presented as decision thresholds for greenfield vs. brownfield investment.
- M&A and partnership shortlist with acquisition rationale, integration risk profile and expected payback windows under multiple demand scenarios.
- Tactical commercial levers—pricing plays, channel segmentation, and co-development templates for strategic customers in coatings, water treatment and advanced membranes.
Data-driven snapshot (what executives can rely on)
Our work builds on a consistent historical series (2020–2025) and a structured forecast (2026–2032). The headline growth rate for the forecast window is 8.7% CAGR—sufficient to support new capacity investments, provided firms mitigate input volatility and regulatory risk. Market concentration metrics show a moderately fragmented supplier base: the top three suppliers account for roughly 28.5% of reported market volumes and the top five for about 35.2%, indicating room for consolidation but also the existence of meaningful niche specialists who retain client loyalties through grade purity and service.
Vinylphosphonic Acid Market
Supply-side dynamics and near-term risks
- Raw-material volatility: Approximately half of global producers report exposure to price swings in phosphorus-based feedstocks. This creates a variable-cost environment that can distort short-term margins and make long-lead capex decisions riskier unless hedging or long-term feedstock contracts are in place.
- Regulatory and logistics friction: A significant share of manufacturers report higher compliance costs from hazardous-storage requirements, and many logistics providers face tightened transportation safety standards—both factors that increase landed cost and compress the economics for lower-margin grades.
- Labor and operating-cost pressure: Specialized handling requirements for hazardous intermediates continue to elevate labor and safety costs, affecting the unit economics of smaller or single-site producers.
Combined, these dynamics mean that in 2026 executives should prioritize secure feedstock arrangements, invest in compliance and logistics resiliency, and assess whether premium-grade product offerings can generate margin leverage to offset higher operating expenses.
Competitive landscape — what matters to buyers and investors
The VPA ecosystem is anchored by a mix of specialty chemical producers and fine-chemicals houses. A short list of representative players illustrates the strategic differentiation in the market:
- Curia (Frankfurt, Germany) — A specialist in high-purity VPA grades with ISO 9001 certification. Curia’s explicit focus on monomer and polymer-grade offerings for coatings, corrosion inhibition and adhesion positions it as a high-value supplier to customers demanding quality and reliability.
- BASF SE (Ludwigshafen, Germany) — Leverages global reach and integrated specialty-chemicals capability to serve polymer modification and water-treatment segments where scale and technical service are decisive.
- Solvay S.A. (Brussels, Belgium) — Supplies targeted grades for metal pre-treatment and corrosion inhibition; recent product-grade upgrades in the market indicate continued innovation orientation in this incumbent.
- TCI Chemicals (India/Tokyo footprint) — Serves laboratory and specialty markets with very-high-purity liquid grades; their presence highlights the importance of reliable small-batch supply for R&D and pharma-facing applications.
- Euticals S.r.l. (Italy) — Represents regional manufacturing with an orientation toward both industrial and pharmaceutical chemistries, often emphasizing flexible production and customized purity profiles.
Recent discrete developments further signal how competition is unfolding: a leading incumbent introduced a high-purity 92% grade with materially lower impurities (April 2024), a European manufacturer executed supply-chain optimizations that cut lead times across multiple distribution centers (October 2024), and an Asia-Pacific producer upgraded polymer-modification testing throughput late in 2025. These moves collectively point to two near-term competitive axes: grade/impurity differentiation and delivery reliability. Firms that can couple high-quality grades with shorter, more predictable lead times will command pricing power in 2026.
Strategic implications — a 2026 decision framework
- Capacity and Capex: Before committing to brownfield or greenfield expansions, stress-test projects against three feedstock-price scenarios (baseline, upside, and downside). With an 8.7% CAGR expected during 2026–2032, selective new capacity can be accretive, but only when paired with long-term feedstock contracts or backward integration strategies that reduce variable-cost exposure.
- Product strategy: Differentiate through grade purity and application-specific formulations. Investment in QA throughput and polymer-modification testing is a high-ROI lever—evidenced by recent quality-driven product introductions and lab-to-scale upgrades.
- Sourcing and logistics: Lock in multi-year logistics partners and explore regional buffer inventories or additional distribution nodes to mitigate transport-restriction impacts. The firms that shortened lead times saw quantifiable commercial benefit in customer retention.
- Compliance and operating model: Allocate capital to hazardous-storage upgrades and compliance automation now to avoid larger retrofitting costs once regulatory inspections intensify. For buyers, preference will shift toward suppliers who demonstrate auditable compliance systems.
- M&A and partnerships: Given a moderately fragmented supplier base (CR3 ~28.5%, CR5 ~35.2%), M&A can be an effective route to consolidate specialty grades and regional footprint. Prioritize targets that offer technology uplift (e.g., lower-impurity grades or faster QA throughput) and logistical advantages.
Use-cases for 2026 corporate actions
Boardrooms should consider the following tactical plays in 2026:
- For producers: Fast-follower strategy—invest in incremental purity improvements and shorten delivery windows rather than race to build large-scale new plants without feedstock security.
- For downstream consumers (coatings, water treatment, membrane makers): Negotiate multi-year supply contracts with quality and service SLAs, and include escalation clauses to share feedstock-cost volatility with suppliers.
- For private equity: Target bolt-on acquisitions that improve product-grade capability or geographic distribution, with a focus on assets that can be upgraded with limited capital to meet higher-purity specifications.
Conclusion — how this preview helps you act in 2026
This preview synthesizes the practical thrust of PW Consulting’s full VPA market study: clear historical growth, a robust forecast (8.7% CAGR for 2026–2032), and a competitive environment where quality, delivery and regulatory resilience determine winners. The full report expands each of these themes into transaction-ready analyses—detailed segment economics, supplier scorecards, regulatory-cost estimates and acquisition target profiles—tools designed to support decisive actions in 2026. For teams that need to convert macro momentum into defensible, near-term commercial and capital allocation moves, the complete study delivers the empirical, operational and competitive detail that boards and strategy teams require.
To review the granular segmentation tables, supplier scorecards and the full set of scenario-modeled P&Ls, access the complete report on our site or contact PW Consulting for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Vinylphosphonic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Silver-based Antimicrobial Market to Hit USD 344.8M by 2032 (6.98% CAGR)
By pmarketresearch, 2026-07-09
Silver-based Antimicrobial Agent Market: Strategic Brief for 2026 Decision-Makers
Executive snapshot
As PW Consulting’s lead industry analyst, I present a concise lens on the silver-based antimicrobial agent market to inform executive decisions in 2026. This market has demonstrated steady expansion through the recent historical period and is projected to continue growing at a compound annual growth rate of approximately 6.98% across the 2026–2032 forecast window. Measured on the report's base-year footing (2025), the global market rose from about USD 153.4 million in 2020 to USD 215.0 million in 2025, and our modelling points to a trajectory that reaches roughly USD 344.8 million by 2032. The structure of the market remains fragmented (CR3 ~24.6%, CR5 ~26.2%), creating simultaneous opportunities for focused incumbents and disciplined new entrants.
Silver-based Antimicrobial Agent Market
Why this briefing matters for 2026 strategy
-
Timing: 2026 is a hinge year—raw material shocks, new regulatory thresholds, and accelerated product adoption in hygiene-sensitive applications are forcing recalibrations of pricing, sourcing, and certification strategies.
Silver-based Antimicrobial Agent Market -
Risk-reward asymmetry: modest overall market size but attractive growth and high margin potential for performance-differentiated chemistries create clear value-capture pathways for players that manage feedstock exposure and regulatory compliance effectively.
Silver-based Antimicrobial Agent Market -
Fragmentation benefits: with the top firms controlling less than one-third of the market, targeted M&A, licensing, or co-development can materially increase scale and margin without requiring broad, cost-intensive consolidation.
Key market dynamics shaping 2026 choices
-
Feedstock volatility: Silver commodity dynamics matter. A pronounced price surge during 2024–2025 pushed spot prices materially higher, elevating input costs for silver-based formulations and sharpening the need for hedging or alternative carrier strategies.
-
Regulatory tightening: In major end markets, registration and compliance frameworks are becoming more prescriptive. For example, U.S. regulatory authorities require registration data for silver ionic treatments in textiles, and several national standards now restrict certain antimicrobial additives in recycled polymer streams.
-
Supply-side fragility: Short-term production and export shifts for silver nitrate and related intermediates in 2025 produced price and availability volatility—drivers that will influence procurement and inventory strategy in 2026.
What our full report delivers (practical, transaction-ready content)
-
Robust market-sizing and validated forecasting model covering 2020–2032, including sensitivity tests against silver price scenarios and policy shocks.
-
Go-to-market playbooks tailored to key end-use clusters, with channel prioritization, value-proposition templates, and margin models.
-
Regulatory compliance map and certification checklist for priority jurisdictions, including pre-clearance timelines and data submission templates.
-
Supply-chain risk matrix identifying single-point-of-failure suppliers, recommended hedging structures, and alternative carrier pathways to reduce silver-loading intensity.
-
Competitive benchmarking and capability heatmaps: technical differentiators, IP posture, commercial reach, and likely strategic moves for market leaders and challenger specialists.
-
M&A and partnership screening framework that ranks targets on technology fit, customer overlap, and integration complexity—designed for rapid due-diligence prioritization.
-
Practical cost-to-serve models to evaluate price premium feasibility across product families and geographies under multiple regulatory scenarios.
Competitive landscape—what to watch from incumbent and specialist players
The market features a mix of specialty chemical majors, inorganic specialist manufacturers, and additive-focused formulators. Each category brings different strategic advantages: scale and distribution from the majors, niche technical IP from specialists, and application know-how from additive houses. Notable players include manufacturers from Japan and Europe with inorganic carrier expertise, North American and European formulators with strong textile and polymer channels, and several chemistry-specialist firms focused on healthcare and hygiene segments.
-
Major chemical companies: These firms can leverage global channels and capital to invest in capacity expansions and acquisitions to broaden portfolios. Recent strategic activity—such as completion of a biocide business transaction in early 2026—signals continued consolidation-minded moves among larger firms seeking to round out antimicrobial offerings.
-
Specialist manufacturers: Players with proprietary inorganic carrier technologies (e.g., glass, zeolite or silicate carriers) maintain technical barriers to entry and can command premium positions in regulated applications where leaching behavior, longevity, and safety data are critical.
-
Additive formulators and textile-focused suppliers: These participants excel at application engineering and downstream certification support, making them preferred partners for OEMs demanding ease-of-integration and validated performance.
-
Cohort developments: Brand repositioning and focused marketing—evident in recent rebranding activity by some specialist firms—reflect a shift toward end-market narratives (e.g., food hygiene, healthcare) that increase willingness to pay for validated antimicrobial claims.
Strategic implications and recommended plays for 2026
-
Short-term (next 6–12 months): Secure feedstock resilience. Lock in forward contracts for silver intermediates where feasible; evaluate tolling or third-party conversion agreements to mitigate capex while ensuring supply continuity.
-
Near-term (12–24 months): Accelerate regulatory readiness. Allocate resources to generate registrable efficacy and environmental fate data for priority jurisdictions and product lines; early submission creates first-mover advantages for textile and medical applications.
-
Commercial (12–36 months): Deploy premium product strategies in tightly regulated end-use verticals. Focus on validated performance and lifecycle claims, where buyers are less price-sensitive and more concerned with certification and traceability.
-
M&A and partnership lens: Pursue bolt-on acquisitions that add carrier technologies, test laboratories, or regional manufacturing footprints. Given the market’s fragmentation, disciplined tuck-ins can lift market share without broad horizontal consolidation.
-
R&D & product strategy: Invest in silver-efficiency technologies and alternative carriers to reduce silver loadings while preserving efficacy—this is a high-return hedge against commodity price cycles and regulatory pressure on silver release.
-
Commercial risk management: Implement tiered pricing and contract structures that allow for commodity pass-throughs or shared upside in the event of further silver price volatility.
How to use our forecast and scenario outputs for board-level decisions
-
Use the CAGR and full forecast series to size investment envelopes and to stress-test internal projections under conservative and aggressive uptake scenarios.
-
Run hedging vs. vertical-integration decision trees using our supply-cost sensitivity models—these quantify payback periods for strategic inventory, backward integration, and alternative carrier adoption.
-
Apply our regulatory timelines to prioritize product launches and to sequence compliance spending: early movers in compliance-constrained segments consistently capture premium placements with OEMs and contract manufacturers.
-
Leverage our competitive scoring when prioritizing acquisition targets: target companies that fill capability gaps (e.g., long-lasting carriers, validated clinical data) rather than only those that increase raw volume.
Risks to monitor closely
-
Commodity-driven margin compression if silver prices remain elevated or continue to spike without corresponding pricing mechanisms.
-
Regulatory shocks—particularly restrictions on additive types in recycled polymers or stricter environmental release thresholds—that can abruptly reclassify route-to-market economics.
-
Technical substitution from non-silver antimicrobial technologies that could pressure demand in specific low-barrier applications.
Concluding note — why invest further in this intelligence
This brief outlines the strategic levers and risk landscape for silver-based antimicrobial agents in 2026. The full PW Consulting study converts these thematic insights into operational tools: granular regional and application splits, supplier-level cost curves, vendor benchmarking matrices, and proprietary scoring models that support acquisition diligence, pricing strategy, and R&D prioritization. Given the market’s projected growth path and the intersection of commodity, regulatory, and application forces, executives who act on high-confidence, scenario-based intelligence in 2026 will materially outpace peers.
Next steps
-
Access the complete report to view the detailed segment analyses, regional demand models, and vendor scorecards that underpin the strategic recommendations summarized here.
-
Contact PW Consulting to schedule a tailored briefing where we walk through scenario outputs, perform a custom sensitivity analysis using your cost structure, and outline an actionable 90-day plan for procurement, compliance, and commercial activation.
For detailed analysis of this topic, please visit the official page: Silver-based Antimicrobial Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Chloromethane Market to Reach USD 5,347M by 2032 at 4.8% CAGR
By pmarketresearch, 2026-07-09
Chloromethane Market: Strategic Imperatives for 2026
Executive snapshot
By the close of our base year (2025) the global chloromethane market reached approximately USD 3,880 million. PW Consulting projects this market to expand at a compound annual growth rate (CAGR) of roughly 4.8% through 2032, reaching an expected market size in the order of USD 5,346 million by the end of the forecast period. That trajectory reflects steady demand from industrial intermediates and specialty applications, offset by regulatory headwinds and feedstock-cost volatility. For corporate decision-makers planning 2026 moves — procurement, capital allocation, M&A, or regulatory compliance — the timing for decisive action is now.
Chloromethane Market
What this study delivers (practical, decision-focused)
- Proprietary topline market sizing and a transparent methodology covering 2020–2025 history and 2026–2032 forecasts, enabling peer benchmarking and scenario testing.
- Supply-side intelligence: plant-level capacity mapping, recent capacity events, and a forward-looking production model that captures idlings, expansions, and acquisition impacts.
- Demand-side segmentation by application and region using a demand-synthesis approach, with modular outputs for commercial planning (note: granular splits are embargoed in this summary to protect proprietary modelling; full segmentation is available in the report).
- Regulatory-impact modelling that quantifies the effects of major rules and exposure-limit changes on commercially permitted uses and manufacturing compliance costs.
- Price and margin sensitivity matrices that link methanol feedstock dynamics and tariff shifts to downstream contract negotiations and short-term hedging decisions.
- A commercially actionable competitor matrix and M&A playbook identifying value pools, integration risks, and five prioritized strategic moves for market leaders and challengers.
Market trajectory and the key drivers
Chloromethanes occupy a middle position between commodity halogen chemistry and specialty intermediates. Growth to 2025 has been underpinned by steady industrial demand (notably in silicone intermediates, specialty solvents and selected refrigerant/intermediate streams) alongside pockets of higher-margin specialty manufacture. Our base-year sizing shows the market expanded consistently over 2020–2025 before entering a phase of bifurcated dynamics driven by three structural forces:
Chloromethane Market
- Regulatory tightening on certain grades — particularly measures that impact consumer and non-essential uses — which reshape addressable demand for specific chloromethanes and raise compliance costs for producers and buyers.
- Feedstock cost cycles — chloromethane production is closely tied to methanol and HCl inputs; spikes in methanol pricing materially compress margins or require passing through higher costs to buyers in contract renegotiations.
- Trade and tariff dynamics — recent changes in tariff policy have shifted global methyl chloride flows and prompted buyers to diversify sourcing and inventory strategies to protect continuity of supply.
Regulatory and operational environment — implications for 2026
2025–2026 has been a watershed for regulatory intervention in key markets. Notably, U.S. risk management actions have effectively removed certain consumer uses and imposed tighter workplace exposure controls for methylene chloride; some commercial uses become restricted with compliance programs required for permitted industrial applications. Exposure limits have been lowered, and the practical effect is twofold: (1) elevated operating costs for downstream users who must invest in engineering controls and monitoring; and (2) a shrinkage of addressable demand segments for some grades, creating both substitution risk and concentrated demand pockets that favor specialist suppliers.
Chloromethane Market
For procurement and operations teams, regulatory moves translate into immediate tactical actions: re-evaluate supplier qualification criteria around certifications and compliance protocols; audit existing inventories against permitted uses; and accelerate substitution assessments where feasible. For upstream producers, the calculus for continuing production versus idling or repurposing assets has changed — a trend already visible in recent capacity re-alignments.
Supply-side shocks and recent market events
Two recent developments crystallize the supply-side rebalancing:
- An acquisition by a major specialty chemicals player expanded regional production capacity and altered competitive positioning, creating scale advantages in certain channels and tightening availability in others.
- A strategic idling of a regional facility by a sizable incumbent reflects a shift toward operational concentration and efficiency — an intentional move to optimize footprint and reallocate investment to higher-return sites.
Combined with methanol-cost inflation observed in late 2025 (which contributed to modest price increases in some markets), these events create a near-term environment where buyers must be pragmatic about contract durations, optionality, and contingency stock levels, while sellers can selectively use capacity discipline to protect margins.
Competitive landscape — what matters to strategy
The chloromethane sector sits at a moderate level of market concentration, where a handful of integrated and regional players exert meaningful influence over supply balances and technical grades. Our competitive analysis focuses on capability differentiation rather than headline market shares. Key strategic archetypes we identify include:
- Integrated global producers with downstream integration into chlorine and methanol-based chemistries — these players leverage feedstock integration and scale to serve large silicone and solvent markets and can offer technical-grade variants for industrial intermediates.
- Regional champions with strong domestic footprints — they prioritize import substitution, secure local distribution channels, and close customer relationships in domestic specialties.
- Specialists with sustainability- or certification-led propositions — firms offering ISCC+ or otherwise certified sustainable grades capture premium segments in environmentally sensitive applications.
Representative companies typifying these archetypes include long-standing integrated incumbents, US-based specialty manufacturers with technical-grade focus, India-centric producers serving domestic markets, and European specialists offering certified sustainable lines. The recent capacity transactions and operational adjustments discussed above change the competitive map by concentrating certain supply streams and opening pockets of opportunity for nimble entrants or contracted offtake partners.
Practical strategic moves for 2026
Based on our modelling and client engagements, the highest-impact actions for executives in 2026 fall into six pragmatic categories:
- Refine sourcing strategies: move from single-supplier contracts to layered supply agreements that combine long-term commitments for critical grades with short-term spot access to manage price volatility.
- Stress-test capex plans: incorporate regulatory-exit scenarios and feedstock-price sensitivity into investment approvals; prioritize flexible assets or debottlenecking projects with short payback horizons.
- Reposition product portfolios: accelerate development or commercialization of alternative chemistries where regulatory constraints make traditional grades less bankable; pursue co-development with end-users who require low-exposure formulations.
- Embed regulatory compliance into commercial terms: update contract language for permitted industrial use, audit rights, and cost-recovery clauses tied to compliance-related capital expenditures.
- Use M&A opportunistically: pursue bolt-on acquisitions that add certified or specialty grades, regional distribution capability, or feedstock integration to de-risk procurement exposure.
- Operationalize sustainability: secure certified feedstock pathways (where available), document chain-of-custody for sustainable grades, and use certifications to defend premium pricing in selective channels.
How PW Consulting’s toolkit de-risks 2026 choices
Our chloromethane study is built to translate market intelligence into executable steps. Tools we provide clients include:
- Scenario models that quantify P&L impacts under different regulatory and feedstock-price pathways.
- Supplier stress-test templates and an approved-supplier requalification playbook for rapid deployment.
- A commercial negotiation toolkit with indexed pricing clauses, force majeure playbooks, and compliance-cost pass-through language tailored to chloromethane contracts.
- An M&A scorecard and quick diligence checklist highlighting asset-level integration risks specific to chlorine/methanol-based production routes.
Why PW Consulting’s study matters for your 2026 planning
Three practical reasons senior leaders tell us this work changes decisions:
- Timing: regulatory deadlines and the lag on compliance capital mean that procurement and capex decisions made in 2026 will determine competitive posture well into the late 2020s.
- Precision: a relatively modest overall CAGR masks uneven growth across grades, regions, and end-markets — precise, proprietary segmentation informs where to invest versus divest.
- Optionality: the combination of tariff-driven trade pattern changes and targeted capacity moves by incumbents creates windows for both defensive and offensive plays; the study quantifies the size and duration of those windows.
Next steps — getting the full picture
This briefing is designed as a strategic trailer: it outlines the drivers, risks, and high-leverage responses for 2026 while preserving the granular datasets and scenario outputs that underpin actionable plans. The full PW Consulting Chloromethane Market report contains the plant-level mapping, regional and application splits, price-curve projections, and supplier scorecards required to operationalize the strategies summarised here. For directors and functional heads preparing 2026 budgets, the report supplies the decision-grade inputs you will need to finalize sourcing, capex, and M&A commitments.
To access the complete dataset, modelling files, and the five prioritized playbooks for market participants, please reach out to PW Consulting or visit our report page where the full study and interactive tools are available.
For detailed analysis of this topic, please visit the official page: Chloromethane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Organic Elemental Analyzer (OEA) Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present a forward-looking strategic primer designed to orient executives, product leaders, and investors as they plan for 2026. This piece synthesizes the core quantitative trajectory of the Organic Elemental Analyzer (OEA) market, interprets structural dynamics that will matter most to buyers and suppliers, and previews the practical, decision-ready tools contained in our full market study. Consider this a high-fidelity trailer: it demonstrates the analytical rigor and actionable framing inside the report while deliberately withholding proprietary granular segment tables to guide you to the source for the complete dataset and supplier scorecards.
Organic Elemental Analyzer (OEA) Market
Market trajectory: the headline numbers that shape strategy
The OEA market reached USD 215.0 Million in the base year (2025) and is projected to expand at a compound annual growth rate (CAGR) of 6.98% through our forecast window (2026–2032). By 2032 the market size is modeled to approach USD 344.8 Million under our central scenario. These headline metrics reflect a market that is neither niche nor commoditized — it is growing steadily, with clear pockets of premiumization driven by accuracy, throughput and integration with downstream analytics (e.g., CHNS/O tools coupling with mass spectrometry and IRMS workflows).
Organic Elemental Analyzer (OEA) Market
Why 2026 is a strategic inflection point
-
Recovery-plus-optimization: Following a period of steady expansion through 2020–2025, 2026 is when capital allocation shifts from catch-up procurement to productivity investment. Organizations will increasingly demand OEA platforms that lower total cost-per-analysis through automation and connectivity.
Organic Elemental Analyzer (OEA) Market -
Regulatory and supply-chain shocks are becoming persistent features. Rather than sporadic, they now influence equipment lifecycles and service models — prompting buyers to prioritize modular, serviceable systems and manufacturers to rethink aftermarket revenue streams.
-
Platform convergence: Expect buyers to favor solutions that are interoperable with analytics stacks (sample prep robotics, chromatography, IRMS, LIMS), favoring suppliers who can deliver validated integration packages over point-product vendors.
Structural characteristics and competitive intensity
The market exhibits a fragmented supplier landscape: the three-largest players account for under one-quarter of revenue and the five-largest share a little over one-quarter, which leaves substantial opportunity for specialized vendors, regional champions, and application-focused newcomers. This dispersion creates tactical openings for fast-followers to win share via focused value propositions (e.g., verticalized applications, consumables-as-a-service, or contract analysis partnerships).
Key capability battlegrounds include analytical precision across micro-to-macro sample ranges, sample throughput and automation, consumables and service economics, and regulatory validation for regulated industries (pharma, food safety, environmental monitoring, and semiconductor fabrication). Suppliers investing in digital service platforms and consumable lock-ins will accelerate margin recovery and lengthen customer lifetime value.
Drivers, friction points and emerging accelerants
-
End-market demand diversification. Applications in life sciences, food & feed, environmental, and advanced materials each present differing value-per-analysis and adoption curves. Strategic entrants should map go-to-market motions to the highest-margin, quickest-adoption use cases first, then scale horizontally.
-
Automation and integration. Buyers signal increasing willingness to pay for validated automation packages that reduce operator variability and improve throughput. This is a durable source of premiumization.
-
Consumables and aftermarket services. Consumable lifecycles and calibration services are a sustained revenue lever. Leading vendors are shifting to bundled or subscription pricing to smooth revenue and deepen customer lock-in.
-
Regulatory clarity and analytical traceability. Stricter documentation and traceable workflows in regulated sectors increase procurement cycles but also raise switching costs for validated systems.
Operational and supply-chain considerations for 2026
-
Component sourcing risk. Critical modules—detectors, furnace assemblies, and high-purity gases—remain potential single-point risks. Manufacturers that diversify suppliers or qualify Tier-2 redundancies will have a resiliency advantage.
-
Service and spare-parts footprint. For global customers, local service presence materially affects procurement decisions. Suppliers expanding regional service hubs will shorten deployment times and convert trials to long-term contracts.
What our report delivers — practical content you can use immediately
The full PW Consulting OEA Market study is structured to be operationally actionable for both buyers and sellers. Highlights include:
-
A concise market model from 2020–2032 with scenario variants (base, conservative, and upside) and explicit assumptions explained so CFOs and strategy teams can run sensitivity tests against CAPEX schedules.
-
Commercial playbooks: segmented go-to-market strategies and pricing templates for OEMs, third-party service providers, and analytical labs.
-
Supplier benchmarking: capability matrices and risk heat maps to support procurement RFPs. (Note: the public primer omits the detailed scorecards and supplier-specific revenue splits; these are available in the paid report.)
-
Regulatory mapping and validation checklists tailored to pharma, food & feed, environmental, and semiconductor verticals—intended for regulatory affairs and QA teams preparing 2026 procurement justifications.
-
Buy-vs-lease and consumables-subscription decision tools with NPV calculators to quantify TCO across common procurement paths.
Competitive landscape — who matters and why
The OEA competitive set is a mix of global instrument OEMs, specialized analyzer manufacturers, and consumables/service specialists. The firms we highlight in the study are representative of distinct strategic archetypes:
-
Thermo Fisher Scientific (Waltham, MA, USA) — A broad industrial and laboratory portfolio combined with validated CHNS/O platforms (e.g., FlashSmart and FLASH 2000 Series). Thermo Fisher competes on integrated workflows and channel depth, making it a default option for large laboratories and regulated environments. ( https://www.thermofisher.com)
-
LECO Corporation (St. Joseph, MI, USA) — Known for macro-combustion analyzers (e.g., the 828 Series) and a strong presence in food and feed testing. LECO’s strength lies in verticalized application support and established service networks in targeted segments. ( https://www.leco.com)
-
Elementar Analysensysteme (Langenselbold, Germany) — Offers multi-element simultaneous analyzers (e.g., vario EL cube) that appeal to labs needing extended-element capability (including oxygen and halogens). Elementar’s engineering focus and European footprint are competitive differentiators. ( https://www.elementar.com)
-
OEA Laboratories (Exeter, UK) — A specialist supplier of elemental analysis consumables and accessories, crucial for labs seeking cost-effective supply and calibration materials. Niche specialists like OEA Labs can capture aftermarket share without selling instruments. ( https://www.oealabs.com)
-
PerkinElmer (Waltham, MA, USA) — A legacy analytics firm offering CHNS/O platforms (e.g., 2400 series) with strong channel and service capabilities in multiple regulated sectors. PerkinElmer competes on validated applications and long-term service contracts. ( https://www.perkinelmer.com)
Each supplier archetype maps to specific buyer needs: global systems vendors for validated, end‑to‑end deployments; specialist OEMs for technical differentiation; and consumables/service providers for aftermarket capture. Our full report contains comparative capability matrices and RFP-ready vendor questions to accelerate procurement diligence.
Strategic moves we recommend for 2026
-
Buyers (corporate labs, contract labs, OEMs): Treat 2026 as an optimization year. Prioritize platforms that reduce per-test variability and integrate with your LIMS/IRMS stack. Insist on consumable and service SLAs in procurement contracts.
-
Sellers (OEMs and service providers): Differentiate through validated automation packages, subscription-based consumable models, and regional service expansion. Invest in digital tools that prove value (downtime reduction, traceability) during pilot phases.
-
Investors: The market’s sub-30% three-firm concentration and modest growth rate (CAGR ~7% across 2026–2032) signal opportunities for specialist consolidation, bolt-on acquisitions that add consumables or services, and software-enabled aftermarket plays.
How to use this primer — and where to get the full intelligence
This preview is designed to give you the strategic orientation needed to prioritize 2026 projects: CAPEX approvals, vendor shortlists, M&A screening, and product roadmap adjustments. To convert these strategic priorities into executable plans, access the full PW Consulting OEA Market Report, which includes:
-
Complete, downloadable market models and interactive scenario tools;
-
Vendor scorecards with supplier-specific advantages, validated integrations and pricing bands;
-
Sample RFP templates and technical validation protocols for procurement teams;
-
Actionable three- to five-year roadmaps for both buyers and sellers.
We intentionally withhold granular segment tables and supplier revenue splits in this public primer to protect the competitive value of the analytics and to invite a direct engagement where we can deliver tailored extracts for your specific use case.
Final thought
The OEA market in 2026 is a growth market defined by technical differentiation, aftermarket economics, and systems integration. Whether you are buying, selling, or investing, success hinges on aligning product and commercial models with customers’ growing demand for validated, automated, and serviceable platforms. PW Consulting’s full study equips decision-makers with the models, vendor diagnostics, and playbooks to make those alignments with confidence.
For detailed analysis of this topic, please visit the official page: Organic Elemental Analyzer (OEA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HVDC Transmission Market to Grow at 6.98% CAGR through 2032
By pmarketresearch, 2026-07-09
HVDC Transmission System Market 2026: Strategic Imperatives for Senior Decision‑Makers
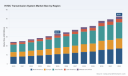
As PW Consulting releases its new HVDC Transmission System Market study, this briefing synthesizes the strategic value of that research for executive teams planning capital allocation, vendor strategy, and grid modernization roadmaps in 2026. Built on a base year of 2025 and a detailed historical window (2020–2025), the study projects the market forward through 2032. The headline: the HVDC market is on a steady, investment‑grade growth path — rising from USD 24.35 Million in 2020 to USD 33.11 Million in 2025 and forecast to reach USD 52.51 Million by 2032, reflecting a 6.98% compound annual growth rate across the forecast period. This trajectory, combined with evolving regulatory guidance and supply‑chain constraints, creates a narrow window for strategic advantage that decision‑makers must not ignore.
HVDC Transmission System Market
Why this matters in 2026
-
Timing for large capital projects is converging with technology inflection points. The mid‑2020s mark a shift where VSC (Voltage Source Converter) and advanced LCC (Line Commutated Converter) deployments are transitioning from proof‑of‑concept to repeatable, utility‑scale implementations. Procurement schedules, permitting timelines, and financing terms established in 2026 will determine which projects capture early upside from the forecasted market expansion.
HVDC Transmission System Market -
Regulatory standardization is accelerating. New recommendations and technical reports are being published to harmonize planning, documentation, and interconnection practices for HVDC. These frameworks reduce engineering uncertainty for well‑prepared sponsors but also raise the bar for compliance and system integration capability during procurement.
HVDC Transmission System Market -
Supply‑chain dynamics are increasingly decisive. Cable and converter equipment costs remain sensitive to raw material trends (notably copper for cable conductors), while certain manufactured subassemblies — assembled circuit breakers, for example — are emerging as critical path items for project schedules. Procurement strategies that do not explicitly mitigate long lead items risk schedule slippage and cost escalation.
What PW Consulting’s report delivers (operational, transaction‑ready content)
-
Market sizing and scenarios: validated historical series (2020–2025), base year calibration (2025), and probabilistic forecasts through 2032. Readers will find top‑line trajectories and multiple demand scenarios tied to policy and technology adoption paths.
-
Technology deep‑dive: comparative evaluation of VSC and LCC architectures, multi‑terminal and back‑to‑back configurations, converter station design considerations, and the systems‑level tradeoffs that drive Opex and availability outcomes.
-
Supplier benchmarking toolkit: multi‑attribute scorecards covering technical footprint, installed capacity, delivery track record, warranty provisions, and interoperability. This toolkit is built to be applied directly in RFP preparation and vendor scoring workshops.
-
Procurement and contracting playbook: model tender documents, recommended contract clauses addressing long lead items, liquidated damages, performance guarantees, and intellectual property considerations for multi‑vendor integration.
-
Supply‑chain risk maps and mitigation options: component‑level lead time heatmaps, alternative sourcing pathways, and pre‑qualification checklists for critical subassemblies.
-
Project economic models: CAPEX/OPEX templates, TCO calculators, and payback scenarios under multiple tariff and congestion assumptions to support financial close and investor due diligence.
-
Regulatory and stakeholder roadmaps: scenario playbooks for the adoption of emerging standards and regional permitting practices, plus stakeholder engagement templates for cross‑border interconnects and city‑center infeeds.
Competitive landscape — strategic takeaways
The HVDC supplier ecosystem combines global system integrators, converter and transformer specialists, and cable manufacturers. Market leadership has consolidated around a handful of system suppliers and cable houses; top firms capture a material share of market volumes while a wider set of regional and vertically integrated vendors competes on cost, speed, and localization.
-
Siemens Energy (Germany) — positions itself with flexible symmetric monopole and bipole architectures suitable for point‑to‑point, multi‑terminal and back‑to‑back systems. Expect Siemens to compete where architectural flexibility and global project execution capability matter most.
-
Hitachi Energy (Switzerland) — active across VSC (HVDC Light®) and classic LCC systems, with strong control and protection stacks tailored for offshore wind and dense urban infeeds. Recent large turn‑ons and transportation milestones demonstrate both operational maturity and a capability to handle outsized equipment logistics.
-
ABB (Switzerland) — continues to leverage pioneering converter innovations and a strong offshore track record. ABB is likely to lead in projects where converter efficiency and long‑distance bulk transfer dominate selection criteria.
-
GE Vernova (United States) — with a sizeable installed base, it competes on customization and proven scale, particularly for large utility corridors and integrated transmission‑generation programs.
-
Mitsubishi Electric (Japan) — focuses on VSC solutions aimed at renewable integration and grid stabilization, making it a natural contender for projects prioritizing dynamic response and black‑start capabilities.
-
Cable specialists (NKT, Nexans, Prysmian, ZTT) — these players are indispensable for subsea and land link deliveries. Their project‑execution risk profiles and marine engineering competence will often dictate the feasibility of long‑distance offshore links.
-
Regional and vertical integrators (LS Electric, NR Electric, others) — these vendors provide attractive local content solutions and rapid project mobilization; however, integration risk and interoperability with global converters remain due diligence areas for buyers.
Strategically, buyers in 2026 should embrace multi‑vendor sourcing for converters and cables where possible, insist on clear interface management, and prioritize vendors with demonstrated multi‑terminal experience. The market’s competitive structure means large suppliers command scale advantages, but regional challengers can win by shortening lead times and offering favourable localization terms.
Recent market signals and supply‑side noise
-
Operational wins and deliveries observed in 2025–2026 signal accelerating commercial maturity — including major city‑infeed switch‑ons and deliveries of transformer hardware of record size — reinforcing that projects once scoped as R&D are now mainstream executions.
-
Raw‑material dynamics: cable cost exposure to copper remains a factor. Published analyses indicate that while global copper markets are susceptible to price swings, demand from HVDC projects alone is not expected to materially reshape regional copper requirements; nevertheless, procurement teams should monitor hedging and supplier pass‑through mechanisms.
-
Standards and regulatory updates are converging on shared planning recommendations for HVDC systems. Anticipate accelerated adoption of harmonized documentation practices that will improve comparability across bids but increase upfront compliance work.
-
Component shortages — assembled circuit breakers and other specialized switchgear — are emerging as critical path constraints. Projects without explicit mitigation strategies are likely to experience the most acute schedule risk.
How executives should use this report in 2026 (practical next steps)
-
Embed the market forecast directly into capital planning cycles. Use the provided scenario outputs to stress‑test project IRRs against higher procurement cost and longer lead‑time permutations.
-
Re‑shape procurement into a capability‑based evaluation. Beyond price, assess vendors on interface management, installed base on similar topologies, ability to meet newly emerging standards, and resilience of supply chains for critical subcomponents.
-
Launch an early supplier alignment program for long lead items. Pre‑négotiation of conditional purchase orders, allocation agreements, and secondary sourcing options will materially reduce schedule risk.
-
Adopt a standards‑first integration plan. Align internal engineering and documentation practices to anticipated regulatory guidance to minimize rework at permitting and interconnection stages.
-
Consider strategic partnerships and M&A selectively. Given the market’s moderate concentration, bolt‑on acquisitions can accelerate capability gaps (e.g., cable manufacturing, converter control software), while partnerships with cable houses can derisk offshore delivery timelines.
Methodology note and access to granular intelligence
This briefing is a strategic synthesis of our full report. PW Consulting’s underlying study is built from proprietary primary interviews, transaction screening, technology assessments, and a bottom‑up project pipeline model calibrated to the 2025 base year. The full report contains the granular regional and application splits, vendor share tables, and project‑level datasets that underpin the topline forecasts cited above. In keeping with our “trailer” approach, those detailed tables and actionable, downloadable templates are gated on the report page — designed to convert strategic interest into operational decisions.
For executives preparing investments, procurements, or strategic partnerships in 2026, this research is intended to be the single most practical, implementable source of HVDC market truth. The next step: access the full PW Consulting HVDC Transmission System Market study to extract the vendor scorecards, contract templates, and project‑level models that directly inform transaction documents and board‑level approvals.
For detailed analysis of this topic, please visit the official page: HVDC Transmission System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Irrigation Controllers Market to Reach USD 465.56M by 2032
By pmarketresearch, 2026-07-09
Irrigation Controllers Market 2026: Strategic Preview for Executive Decision‑Making
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a curated, high‑value preview of our Irrigation Controllers Market research—designed specifically to inform boardroom conversations and capital allocation choices in 2026. This briefing synthesizes the market’s trajectory, competitive dynamics, regulatory inflections, and actionable strategic options while preserving the granular segment data that are contained exclusively in the full report.
Irrigation Controllers Market
Why this research matters for 2026 decisions
- Companies facing product portfolio, channel, or M&A decisions need a clear view of demand growth, concentration, and the policy forces shaping adoption. Our study situates those variables within an empirically grounded forecast informed by historical trends (2020–2025) and scenarios through 2032.
- Infrastructure and ag‑tech investors require defensible assumptions about revenue growth and margin pressure from input cost shocks. We quantify market scale and translate growth into plausible revenue pools for adjacent capabilities (connectivity, analytics, sensors, services).
- Procurement and public sector actors must balance water‑efficiency goals against procurement complexity—this work maps how rebate programs, certification changes, and federal guidance alter procurement economics in 2026 and beyond.
Market trajectory—what the numbers tell us
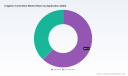
The irrigation controllers market has transitioned from a niche control hardware market into a fast‑growing platform market. In absolute terms, PW Consulting’s topline model shows the global market expanding from roughly USD 200 million in 2020 to about USD 260 million in the 2025 base year, with our baseline forecast projecting a compound annual growth rate of 8.82% over the 2026–2032 horizon. Under this baseline, overall market value approaches the mid‑hundreds of millions by 2032, driven by accelerated adoption of smart, connected, and standards‑certified controllers.
Irrigation Controllers Market
Key growth drivers reflected in our model include: rising municipal and federal water efficiency mandates; expanding rebate and incentive programs that lower adoption friction; increased micro‑irrigation and precision‑agriculture deployments; and steady product migration from legacy timer controllers to weather‑ and sensor‑integrated platforms. At the same time, the market exhibits moderate‑to‑high concentration: the top three vendors account for the majority share, and the top five capture a clear supermajority—an important signal for prospective entrants, channel partners, and technology integrators.
Irrigation Controllers Market
Segmentation and the “what we publish vs. what we reserve” principle
Our research disaggregates the market by product type, application, and region, and provides granular forecasts, price decks, and unit shipment estimates. In keeping with the “trailer” principle of this executive preview, I will highlight the structure of the segmentation and the strategic conclusions you can draw from it—without publishing the detailed split figures that form the core intellectual property of the study. The full dataset behind this preview includes:
- Type segmentation (weather‑based, sensor‑based, legacy/others) with multi‑scenario adoption curves and implied installed base turnover rates;
- Application segmentation (agriculture vs. non‑agriculture) reflecting differential replacement cycles and service revenue potential;
- Regional roll‑up with demand drivers and rebate/regulatory overlays for major markets;
- Channel and buyer archetypes—OEM, retrofit installers, water authorities, and farm consolidators—each with unique procurement behaviors and margin expectations.
If you need the precise split tables, unit pricing matrices, or downloadable model, the full report provides them in Excel‑native format along with a walk‑through of assumptions and sensitivity levers.
Competitive landscape: who matters and how they’re positioned
The competitive field combines legacy irrigation OEMs, ag‑tech platform providers, and software‑centric entrants. A few firms anchor the market and set technological and channel norms; others compete by vertical specialization or software differentiation. Our report profiles each of the major players and evaluates strategic levers for 2026:
- Hunter Industries (Tualatin, Oregon) — a leader in Wi‑Fi and internet‑connected controllers with established product lines and Hydrawise integration. Positioning strengths include channel reach into residential and landscape segments and a clear brand in smart consumer installs.
- Rain Bird Corporation (Glendora, California) — notable for modular controllers and weather‑based platforms; deep relationships with professional installers and landscape architects give Rain Bird leverage in retrofit and commercial projects.
- The Toro Company (Bloomington, Minnesota) — competes across residential, commercial, and central control systems. Toro’s DXi central control and Irritrol Rain Master portfolios reinforce its presence in large‑site installations and municipal contracts.
- Netafim (global; North American operations) — brings precision‑agriculture pedigree and drip system integration, which is particularly relevant as growers seek water‑use efficiency and data‑driven irrigation management.
- Galcon (Israel; global) — focuses on advanced smart controllers across residential, agricultural, and specialty segments (e.g., golf), often emphasizing flexible connectivity and modular deployment.
- HydroPoint Data Systems (Santa Barbara, California) — differentiates on software and analytics, emphasizing weather‑based scheduling and enterprise‑grade integrations for commercial customers.
Strategic implications: incumbents are extending into SaaS and services, while software‑first entrants are pursuing hardware partnerships. Margins will increasingly bifurcate between commodity controller sales and recurring services (analytics, remote management, subscription connectivity). For acquirers, tuck‑ins that add analytics, channel access, or certification expertise score highest in our decision matrix.
Regulatory and programmatic tailwinds & headwinds
Regulation and public programs are shaping adoption curves in 2026 more strongly than in prior years. Notable developments that we model explicitly:
- US EPA WaterSense criteria updates (effective March 2026) now require independent certification for certain smart controllers. This creates a near‑term certification runway for compliant vendors and a procurement advantage where rebates require WaterSense labeling.
- Municipal rebate programs in multiple US jurisdictions provide meaningful downward pressure on effective purchase price for end users, raising ROI and shortening payback for smart upgrades—our baseline scenario quantifies the aggregate effect of active rebate programs on adoption velocity.
- Tariff changes announced in 2025 (steel and aluminum) introduce manufacturing cost pressure for hardware‑heavy producers and component suppliers. We quantify the pass‑through risk to ASPs and evaluate hedging and in‑sourcing strategies.
- Federal guidance (FEMP) and public sector deployments demonstrate that advanced controllers can deliver 15%–40% water reduction in institutional applications—an important justification for capital projects and efficiency programs.
For manufacturers and channel partners, the policy environment implies two immediate priorities for 2026: secure WaterSense or equivalent certification where it materially affects rebate eligibility, and build pricing models that reflect higher input costs and possible tariff volatility.
Actionable strategic options for 2026
Based on our scenario modeling and vendor benchmarking, PW Consulting recommends executives consider the following prioritized actions this year:
- Fast‑track certification and rebate‑alignment. Certification is a gate to many public and utility rebate programs. Firms that fail to certify risk losing retrofit and municipal pipeline opportunities.
- Shift portfolio emphasis toward recurring revenue. Product roadmaps should incorporate cloud management, analytics subscriptions, or contracted services—these improve valuation multiples and mitigate hardware margin compression.
- Harden supply chains and diversify components. Given recent tariff-driven input cost shocks, near‑term sourcing strategies (regionalization, long‑term component agreements, and design for lower‑cost materials) reduce exposure.
- Pursue targeted partnerships or bolt‑on M&A. Buyers should prioritize deals that deliver software capabilities, channel reach into commercial/municipal buyers, or certification expertise—each has outsized value in accelerating adoption.
- Differentiate on verification and outcomes. With buyers increasingly focused on water savings (and regulators requiring measurable performance), vendors that provide verifiable outcome reporting will be preferred partners in utility and federal projects.
What the full PW Consulting report contains (practical workbook for teams)
The full market study is built to be operationalized across strategy, commercial, and product teams. Key deliverables include:
- End‑to‑end market model (2020–2032) with scenario toggles, downloadable in Excel.
- Price and ASP matrices by controller class and deployment type, plus margin sensitivity analyses.
- Vendor scorecards (technology, channel, financial profile) and a short‑list of likely acquirers for each vendor class.
- Regulatory tracker and rebate database tied to adoption impact models suitable for business case development.
- Go‑to‑market playbooks for three archetypal companies (incumbent OEM, software platform entrant, and regional integrator) with recommended KPIs and 18‑month roadmaps.
These materials are designed so that leadership teams can run “what‑if” scenarios during strategy offsites and produce investment memos with supporting evidence.
Conclusion — the 2026 strategic imperative
Market growth, concentrated vendor power, and accelerating regulation converge to create a high‑stakes environment in 2026. The opportunity is real—but it is time‑sensitive. Vendors and investors that move early to align products with certification requirements, design for service‑led economics, and shore up supply lines will capture disproportionate value as the market expands at nearly a single‑digit double‑digit CAGR through 2032.
PW Consulting’s full Irrigation Controllers Market report contains the granular forecasts, playbooks, and vendor intelligence to convert these strategic imperatives into executable plans. For decision‑ready insights, model access, and a bespoke briefing for your executive team, consult the full study at our report page.
For detailed analysis of this topic, please visit the official page: Irrigation Controllers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Stationery market to hit USD 230.16M by 2032, growing at 4.85% CAGR — PW Consulting
By pmarketresearch, 2026-07-09
Stationery Market 2026: Strategic Preview for Decision Makers
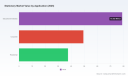
As organizations recalibrate portfolios and supply chains for the post-pandemic, inflation-aware era, stationery—long perceived as a mature, low-growth category—has re-emerged as a strategic arena for margin recovery, brand differentiation, and sustainability-led innovation. This preview synthesizes the most consequential signals from our full Stationery Market study (base year 2025) to help executives prioritize choices for 2026. It demonstrates why this market, valued at USD 165.87 Million in 2025 and forecast to expand at a 4.85% CAGR to reach roughly USD 230.16 Million by 2032, deserves active management rather than passive acceptance.
Stationery Market
Why this study matters to 2026 strategy
-
Timing: With key geopolitical and trade shifts crystallizing in 2025–2026, the stationery sector is at an inflection point where input-cost shocks, shifting channel economics and sustainability compliance will reshape supplier footprints and pricing power.
Stationery Market -
Profit pool opportunity: Modest aggregate growth masks divergent performance across product tiers and channels—premium, sustainable and digitally-enabled SKUs are consistently outperforming commoditized assortments. Companies that reallocate investment to these pockets can materially improve gross margins and brand equity.
Stationery Market -
Actionability: The full report translates market sizing, competitive positioning and supply-chain stress tests into a prioritized set of tactical moves—SKU rationalization, channel-specific pricing, and targeted capex for sustainable materials—that can be implemented in 6–12 months.
Market trajectory at a glance
Between 2020 and 2025 the category recovered from pandemic-era disruptions and recorded accelerated expansion, reaching USD 165.87 Million in 2025 (our base year). The forecast horizon (2026–2032) embeds observable drivers—steady demand in education and corporate segments, selective premiumization, and rising adoption of eco-conscious products—and yields a compound annual growth rate of approximately 4.85%. By 2032 the market is expected to approach USD 230.16 Million under the baseline scenario. For corporations, the key implication is not just top-line growth but structural margin improvement potential through product and channel engineering.
Report contents — practical modules that guide 2026 decisions
-
Market sizing and rolling forecast (2026–2032) with scenario overlays: baseline, disruption and accelerated premiumization.
-
Demand drivers and elasticity models for education, corporate and retail channels—translated into SKU-level prioritization and SKU retirement triggers.
-
Supply-chain vulnerability map with near-, mid- and long-term mitigations: supplier diversification, nearshoring sensitivity, and inventory policy trade-offs under tariff pressure.
-
Commercial playbook: channel-specific go-to-market rules, optimized pricing ladders, promotional cadence, and assortment rebalancing templates to lift gross margins.
-
ESG and regulatory impact toolkit: compliance checkpoints, cost-to-implement estimates for sustainable sourcing, and consumer willingness-to-pay benchmarks for eco-labeled products.
-
Competitive benchmarking and strategic moves matrix: capabilities heatmaps for global and regional players, partnership/bolt-on M&A targets, and potential white-space innovation opportunities.
-
Five-year product roadmap scenarios and investment cases—complete with NPV ranges and sensitivity to key inputs such as raw-material price swings and tariff regimes.
Competitive landscape—what incumbents and challengers signal for 2026
The stationery market remains moderately consolidated: the top three players account for roughly one-quarter of revenue while the top five capture around two-fifths of the market. This structure produces meaningful opportunities both for scale-driven incumbents and for agile challengers that can exploit whitespace through branding, channel innovation or niche product leadership.
-
BIC (Clichy, France) continues to blend scale with a sharper sustainability narrative—its 2025 Sustainability Report (published May 2026) and a national school-supply campaign launched the same month underline a dual approach: protect mass-market share while building ESG differentiation.
-
Faber-Castell (Würselen, Germany) and Staedtler (Nuremberg, Germany) remain reference points in premium and professional stationery, where brand heritage and quality command steady pricing power.
-
Japanese producers (Pilot, Pentel, Zebra, Mitsubishi Pencil) maintain competitive strength via product innovation and category variety, particularly in writing instruments where performance and feel matter.
-
China- and India-based manufacturers (e.g., M&G Stationery, Deli Group, Kokuyo Camlin, Beifa) are increasingly important for cost-competitive supply and fast-follower product cycles, but face differentiation pressure absent stronger brand propositions.
-
Newell Brands and legacy US players maintain downstream distribution reach but must contend with input-cost inflation and tariff-driven margin compression.
For 2026, the tactical takeaway is clear: consolidation or scale alone will not guarantee outperformance. Market leaders that combine cost discipline with targeted premium and sustainable product investments—and that can execute agile promotional mechanics in education and corporate channels—will capture disproportionate upside.
Dynamics reshaping 2026 priorities
-
Tariff and trade adjustments: New tariff policies introduced in 2025 have elevated input costs for import-dependent sectors globally. In the US, import cargo volumes are projected to decline, pressuring companies that rely on long, cross-border supply chains. Strategic responses include selective nearshoring, multi-sourcing contracts with indexed pricing, and hedging raw-material exposure.
-
Sustainability as competitive table stakes: Recent corporate disclosures and campaigns—exemplified by several large players—signal that sustainable product attributes are moving from niche to mainstream. Expect procurement contracts and large institutional buyers (education systems, corporate procurement) to incorporate ESG scorecards as a bid qualifier in 2026.
-
Channel bifurcation and premiumization: E-commerce and value-based retail channels continue to expand share, while institutional buyers prioritize total cost of ownership. Brands that tailor assortments and pricing to channel economics unlock margin expansion without relying solely on volume growth.
-
Product innovation vectors: Material substitution (recycled and bio-based inputs), longevity and refillability, and digital augmentation (smart pens, education-linked microservices) are areas where modest R&D investment produces outsized differentiation.
Strategic playbook for 2026 (priority moves)
-
Re-segment portfolios: Immediately identify the top 20% of SKUs driving 80% of profit and implement a phased SKU optimization program to retire low-margin tail SKUs within 9–12 months.
-
Cost-to-serve recalibration: Reprice channels based on true cost-to-serve and introduce differentiated margin floors for institutional vs retail distribution.
-
Supply resilience: Negotiate flexible multi-year purchase agreements with key suppliers that include volume-flex clauses and indexation to raw-material baskets, and pilot nearshoring for high-risk SKUs.
-
Sustainability monetization: Launch a focused, consumer-facing sustainability line with a clear value proposition and measurable KPIs; track payback over a 24–36 month window.
-
M&A and partnerships: Target bolt-on acquisitions that add route-to-market strengths in prioritized geographies or that provide capabilities in sustainable materials and digital services.
How to use the full report
Consider this preview a strategic compass. The full PW Consulting Stationery Market study converts these directional insights into executable artifacts—detailed supplier scorecards, SKU-level margin models, channel-specific promotional playbooks, and acquisition target lists—so that leadership teams can move from intent to implementation within the fiscal year. For procurement and commercial leaders, the report provides pricing ladders and negotiation scripting; for product and R&D teams, it lays out prioritized materials roadmaps and cost-to-implement matrices.
Final note
Stationery in 2026 is not a legacy cost center; it is a modular set of opportunities—supply resilience, premium product growth, and sustainability monetization—that companies can orchestrate to deliver measurable financial and reputational returns. PW Consulting’s full study contains the granular splits, scenario models and playbooks necessary to translate this positioning into 12–36 month results. For executives evaluating investment priorities in 2026, the structured evidence and tactical roadmaps in the full report will materially reduce execution risk and accelerate outcomes.
For detailed analysis of this topic, please visit the official page: Stationery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Construction PM Software Set for 13.82% CAGR Through 2032
By pmarketresearch, 2026-07-09
Construction Project Management Software Market — Strategic Preview for 2026 Decision-Makers
As construction organizations confront accelerating complexity—distributed teams, tighter regulatory oversight, and relentless margin pressure—the software stack that coordinates projects has moved from “nice to have” to mission critical. PW Consulting’s latest market study, anchored on a 2025 base year and projecting through 2032, quantifies this shift and translates it into actionable choices for executives preparing 2026 budgets, procurement roadmaps, and M&A agendas.
Construction Project Management Software Market
Why this study matters for 2026
-
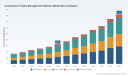
A rapidly expanding opportunity. The market for construction project management software is no longer nascent: having grown steadily across the 2020–2025 period, it is forecast to expand at a compound annual growth rate of approximately 13.82% over the 2026–2032 horizon. Our topline projections show a marked step-up in absolute scale through the forecast window, driven by digital transformation programs, regulatory mandates for digital documentation, and a wave of cloud and AI-enabled product enhancements.
Construction Project Management Software Market -
Strategic timing. For boards and C-suite teams planning 2026 spend, the research identifies inflection points where incremental investment in project management platforms delivers outsized returns: reducing rework from design clashes, shortening approval cycles on change orders, and improving field-to-office cash conversion. The value calculus in 2026 is less about ‘if’ to adopt and more about ‘how aggressively’ to standardize on integrated toolchains.
Construction Project Management Software Market -
Decision-useful framing. Rather than a static vendor scorecard, the study frames supplier selection and investment through practical scenarios (greenfield digital transformation, brownfield incremental upgrades, and bolt-on acquisitions). Each scenario maps to expected timeline, risk profile, and ROI thresholds relevant to 2026 capital planning cycles.
Market trajectory — a data-driven narrative
PW Consulting’s model draws on historical observations from 2020–2025 and a scenario-rich forecasting engine for 2026–2032. The result: a clear trajectory from a mid-market footprint in 2025 toward a materially larger opportunity by the early 2030s. That growth is not uniform—our qualitative analysis identifies pockets of accelerated adoption (notably projects with mandated BIM or sophisticated sustainability reporting) alongside slower-moving segments where legacy workflows and client procurement constraints persist. Importantly, the forecast recognizes the monetization potential of adjacent capabilities—AI-driven schedule risk analytics, integrated safety and compliance modules, and digital twin-enabled lifecycle services—that are driving incremental vendor revenue beyond basic project controls.
What the report contains — operationally relevant deliverables
-
Executive playbooks: concise, role-specific recommendations for CIOs, heads of construction, and procurement leads, including sequencing of capabilities to prioritize in 2026 (document control, RFI/change management automation, field mobility, and real-time schedule-risk dashboards).
-
Investment-grade forecasting: topline and scenario forecasts from 2026–2032, with transparent assumptions and sensitivity testing for input variables such as cloud migration rates, AI feature adoption, and public-sector BIM mandates.
-
Vendor benchmarking toolkit: an assessment framework that combines functional capability, deployment flexibility, integration posture, and go-to-market strength—designed to be used directly in vendor selection RFPs or due diligence checklists.
-
Implementation playbooks and ROI calculators: practical templates for pilot-to-scale sequencing, resource plans, and short/medium-term benefits realization metrics tailored to contractor, owner, and engineer/operator models.
-
Regulatory and compliance mapper: distilled implications of BIM mandates, safety training requirements, and public procurement rules that matter for software scope and contract obligations.
Competitive landscape — synthesis and strategic implications
The vendor ecosystem blends global software platforms, specialist construction cloud players, and ERP-focused incumbents. Market concentration metrics indicate a moderate level of consolidation: the leading three vendors account for a meaningful portion of vendor revenue, with the top five widening that footprint further. This structure creates a dual dynamic: sizable incumbents can leverage integrated suites and enterprise sales motion, while specialist vendors exploit vertical depth and agility to win niche use-cases.
-
Procore Technologies: A cloud-native platform with end-to-end construction workflows. Its strengths lie in mobile field execution, document control, and a broad partner ecosystem. For 2026 strategy, Procore remains a benchmark for cloud-first deployments and wide-scale contractor adoption.
-
Autodesk (Construction): Leveraging BIM and design-to-construction continuity, Autodesk’s offering positions well where architectural and engineering workflows must remain tightly coupled to execution. For public infrastructure and projects with strict digital delivery mandates, Autodesk’s integrated BIM advantage is material.
-
Bentley Systems: Strong in infrastructure and 4D planning with digital twin capabilities. Bentley’s positioning favors large civil and infrastructure projects that value high-fidelity modeling and lifecycle asset management.
-
Trimble: Focused on field-to-office data capture and resource tracking. Trimble’s product suite is attractive for firms that prioritize geospatial accuracy and integrated field hardware/software workflows.
-
Sage Group: Traditionally an accounting and ERP specialist that has extended into construction lifecycle management. Sage is relevant for organizations seeking tighter financial controls and profitability tracking embedded in project software.
-
Buildertrend, CMiC, Jonas: These vendors illustrate divergent go-to-market strategies—Buildertrend targets residential and smaller commercial builders with cloud simplicity, CMiC and Jonas emphasize ERP-grade project accounting and enterprise continuity for larger contractors.
Recent product moves in 2026—ranging from document workflow upgrades to mobile releases—underscore the market’s practical focus. Vendor updates in the first half of 2026 emphasize better PDF/document handling, improved RFI/change order workflows, and mobile experience refinements—features that directly reduce day-to-day friction in contractor operations. These incremental advancements are meaningful because they accelerate user adoption and shorten payback periods for deployments.
Technology and regulatory dynamics shaping 2026 choices
-
BIM and procurement: Regulatory regimes in several jurisdictions now mandate BIM or equivalent digital collaboration on many public projects. This continues to push buyers toward platforms that can demonstrate clash detection, versioned documentation, and audit-ready records.
-
Safety and compliance integration: Training and certification requirements—such as OSHA and national site management standards—make safety tracking and workforce credentialing an operational prerequisite. Platforms that incorporate compliance workflows reduce administrative overhead and contractual risk.
-
AI and predictive analytics: AI adoption has moved from experimentation to embedded functionality; a meaningful share of platforms already shipped AI-driven analytics for schedule and cost risk by 2025. In 2026, buyers will evaluate AI not as an add-on but as a differential factor for real-time decision support.
-
Cloud-first economics: Cloud adoption continues to be the dominant deployment approach because it supports distributed teams, rapid feature delivery, and integration with other enterprise systems. Expect cloud-native offerings to accelerate product innovation and partner integrations in 2026.
Implications for investment, M&A, and procurement
For investors and corporate development teams, the combination of solid CAGR dynamics and moderate market concentration suggests two enduring strategies: (1) bolt-on acquisitions to fill capability gaps (AI analytics, compliance modules, field data capture), and (2) roll-up strategies that consolidate niche regional or vertical specialists into broader platform plays. For enterprise procurement teams, the imperative is to adopt a modular roadmap: secure core project controls and document management in the near term, then phase in higher-value components (AI risk engines, digital twin integrations) aligned with measurable KPIs.
How to use the full report in a 2026 planning cycle
-
Use the scenario forecasts to stress-test procurement budgets under different migration timelines and regulatory impact assumptions.
-
Run vendor shortlists through our benchmark framework to prioritize pilots that validate integration, user adoption, and benefits realization within a 6–12 month window.
-
Leverage the implementation playbooks and ROI templates to convert vendor promises into contractual SLAs and milestone-based payments.
Final note — what we intentionally withhold here
This preview shares the strategic conclusions, market trajectory, and vendor implications that matter for 2026 decisions. To preserve the value of the full study as an operational tool, detailed segment-level splits, regional allocations, precise vendor revenue shares by segment, and the complete financial model are available exclusively in the full report. Those datasets power the granular supplier scorecards and the scenario-specific ROI calculators that procurement teams and investors will require to finalize 2026 commitments.
PW Consulting’s Construction Project Management Software Market study is crafted for leaders who must convert market understanding into executable plans. If you are preparing technology budgets, evaluating acquisition targets, or leading a transformation program in 2026, the full report provides the evidence base, templates, and vendor intelligence you will need to move from intent to impact.
For detailed analysis of this topic, please visit the official page: Construction Project Management Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com