

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Chloromethane Market to Reach USD 5,347M by 2032 at 4.8% CAGR

Chloromethane Market: Strategic Imperatives for 2026
Executive snapshot
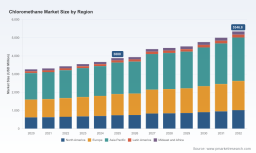
By the close of our base year (2025) the global chloromethane market reached approximately USD 3,880 million. PW Consulting projects this market to expand at a compound annual growth rate (CAGR) of roughly 4.8% through 2032, reaching an expected market size in the order of USD 5,346 million by the end of the forecast period. That trajectory reflects steady demand from industrial intermediates and specialty applications, offset by regulatory headwinds and feedstock-cost volatility. For corporate decision-makers planning 2026 moves — procurement, capital allocation, M&A, or regulatory compliance — the timing for decisive action is now.
Chloromethane Market
What this study delivers (practical, decision-focused)
- Proprietary topline market sizing and a transparent methodology covering 2020–2025 history and 2026–2032 forecasts, enabling peer benchmarking and scenario testing.
- Supply-side intelligence: plant-level capacity mapping, recent capacity events, and a forward-looking production model that captures idlings, expansions, and acquisition impacts.
- Demand-side segmentation by application and region using a demand-synthesis approach, with modular outputs for commercial planning (note: granular splits are embargoed in this summary to protect proprietary modelling; full segmentation is available in the report).
- Regulatory-impact modelling that quantifies the effects of major rules and exposure-limit changes on commercially permitted uses and manufacturing compliance costs.
- Price and margin sensitivity matrices that link methanol feedstock dynamics and tariff shifts to downstream contract negotiations and short-term hedging decisions.
- A commercially actionable competitor matrix and M&A playbook identifying value pools, integration risks, and five prioritized strategic moves for market leaders and challengers.
Market trajectory and the key drivers
Chloromethanes occupy a middle position between commodity halogen chemistry and specialty intermediates. Growth to 2025 has been underpinned by steady industrial demand (notably in silicone intermediates, specialty solvents and selected refrigerant/intermediate streams) alongside pockets of higher-margin specialty manufacture. Our base-year sizing shows the market expanded consistently over 2020–2025 before entering a phase of bifurcated dynamics driven by three structural forces:
Chloromethane Market
- Regulatory tightening on certain grades — particularly measures that impact consumer and non-essential uses — which reshape addressable demand for specific chloromethanes and raise compliance costs for producers and buyers.
- Feedstock cost cycles — chloromethane production is closely tied to methanol and HCl inputs; spikes in methanol pricing materially compress margins or require passing through higher costs to buyers in contract renegotiations.
- Trade and tariff dynamics — recent changes in tariff policy have shifted global methyl chloride flows and prompted buyers to diversify sourcing and inventory strategies to protect continuity of supply.
Regulatory and operational environment — implications for 2026
2025–2026 has been a watershed for regulatory intervention in key markets. Notably, U.S. risk management actions have effectively removed certain consumer uses and imposed tighter workplace exposure controls for methylene chloride; some commercial uses become restricted with compliance programs required for permitted industrial applications. Exposure limits have been lowered, and the practical effect is twofold: (1) elevated operating costs for downstream users who must invest in engineering controls and monitoring; and (2) a shrinkage of addressable demand segments for some grades, creating both substitution risk and concentrated demand pockets that favor specialist suppliers.
Chloromethane Market
For procurement and operations teams, regulatory moves translate into immediate tactical actions: re-evaluate supplier qualification criteria around certifications and compliance protocols; audit existing inventories against permitted uses; and accelerate substitution assessments where feasible. For upstream producers, the calculus for continuing production versus idling or repurposing assets has changed — a trend already visible in recent capacity re-alignments.
Supply-side shocks and recent market events
Two recent developments crystallize the supply-side rebalancing:
- An acquisition by a major specialty chemicals player expanded regional production capacity and altered competitive positioning, creating scale advantages in certain channels and tightening availability in others.
- A strategic idling of a regional facility by a sizable incumbent reflects a shift toward operational concentration and efficiency — an intentional move to optimize footprint and reallocate investment to higher-return sites.
Combined with methanol-cost inflation observed in late 2025 (which contributed to modest price increases in some markets), these events create a near-term environment where buyers must be pragmatic about contract durations, optionality, and contingency stock levels, while sellers can selectively use capacity discipline to protect margins.
Competitive landscape — what matters to strategy
The chloromethane sector sits at a moderate level of market concentration, where a handful of integrated and regional players exert meaningful influence over supply balances and technical grades. Our competitive analysis focuses on capability differentiation rather than headline market shares. Key strategic archetypes we identify include:
- Integrated global producers with downstream integration into chlorine and methanol-based chemistries — these players leverage feedstock integration and scale to serve large silicone and solvent markets and can offer technical-grade variants for industrial intermediates.
- Regional champions with strong domestic footprints — they prioritize import substitution, secure local distribution channels, and close customer relationships in domestic specialties.
- Specialists with sustainability- or certification-led propositions — firms offering ISCC+ or otherwise certified sustainable grades capture premium segments in environmentally sensitive applications.
Representative companies typifying these archetypes include long-standing integrated incumbents, US-based specialty manufacturers with technical-grade focus, India-centric producers serving domestic markets, and European specialists offering certified sustainable lines. The recent capacity transactions and operational adjustments discussed above change the competitive map by concentrating certain supply streams and opening pockets of opportunity for nimble entrants or contracted offtake partners.
Practical strategic moves for 2026
Based on our modelling and client engagements, the highest-impact actions for executives in 2026 fall into six pragmatic categories:
- Refine sourcing strategies: move from single-supplier contracts to layered supply agreements that combine long-term commitments for critical grades with short-term spot access to manage price volatility.
- Stress-test capex plans: incorporate regulatory-exit scenarios and feedstock-price sensitivity into investment approvals; prioritize flexible assets or debottlenecking projects with short payback horizons.
- Reposition product portfolios: accelerate development or commercialization of alternative chemistries where regulatory constraints make traditional grades less bankable; pursue co-development with end-users who require low-exposure formulations.
- Embed regulatory compliance into commercial terms: update contract language for permitted industrial use, audit rights, and cost-recovery clauses tied to compliance-related capital expenditures.
- Use M&A opportunistically: pursue bolt-on acquisitions that add certified or specialty grades, regional distribution capability, or feedstock integration to de-risk procurement exposure.
- Operationalize sustainability: secure certified feedstock pathways (where available), document chain-of-custody for sustainable grades, and use certifications to defend premium pricing in selective channels.
How PW Consulting’s toolkit de-risks 2026 choices
Our chloromethane study is built to translate market intelligence into executable steps. Tools we provide clients include:
- Scenario models that quantify P&L impacts under different regulatory and feedstock-price pathways.
- Supplier stress-test templates and an approved-supplier requalification playbook for rapid deployment.
- A commercial negotiation toolkit with indexed pricing clauses, force majeure playbooks, and compliance-cost pass-through language tailored to chloromethane contracts.
- An M&A scorecard and quick diligence checklist highlighting asset-level integration risks specific to chlorine/methanol-based production routes.
Why PW Consulting’s study matters for your 2026 planning
Three practical reasons senior leaders tell us this work changes decisions:
- Timing: regulatory deadlines and the lag on compliance capital mean that procurement and capex decisions made in 2026 will determine competitive posture well into the late 2020s.
- Precision: a relatively modest overall CAGR masks uneven growth across grades, regions, and end-markets — precise, proprietary segmentation informs where to invest versus divest.
- Optionality: the combination of tariff-driven trade pattern changes and targeted capacity moves by incumbents creates windows for both defensive and offensive plays; the study quantifies the size and duration of those windows.
Next steps — getting the full picture
This briefing is designed as a strategic trailer: it outlines the drivers, risks, and high-leverage responses for 2026 while preserving the granular datasets and scenario outputs that underpin actionable plans. The full PW Consulting Chloromethane Market report contains the plant-level mapping, regional and application splits, price-curve projections, and supplier scorecards required to operationalize the strategies summarised here. For directors and functional heads preparing 2026 budgets, the report supplies the decision-grade inputs you will need to finalize sourcing, capex, and M&A commitments.
To access the complete dataset, modelling files, and the five prioritized playbooks for market participants, please reach out to PW Consulting or visit our report page where the full study and interactive tools are available.
For detailed analysis of this topic, please visit the official page: Chloromethane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com