

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: HVDC Transmission Market to Grow at 6.98% CAGR through 2032

HVDC Transmission System Market 2026: Strategic Imperatives for Senior Decision‑Makers
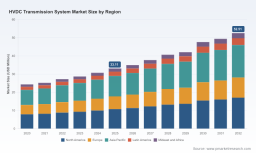
As PW Consulting releases its new HVDC Transmission System Market study, this briefing synthesizes the strategic value of that research for executive teams planning capital allocation, vendor strategy, and grid modernization roadmaps in 2026. Built on a base year of 2025 and a detailed historical window (2020–2025), the study projects the market forward through 2032. The headline: the HVDC market is on a steady, investment‑grade growth path — rising from USD 24.35 Million in 2020 to USD 33.11 Million in 2025 and forecast to reach USD 52.51 Million by 2032, reflecting a 6.98% compound annual growth rate across the forecast period. This trajectory, combined with evolving regulatory guidance and supply‑chain constraints, creates a narrow window for strategic advantage that decision‑makers must not ignore.
HVDC Transmission System Market
Why this matters in 2026
-
Timing for large capital projects is converging with technology inflection points. The mid‑2020s mark a shift where VSC (Voltage Source Converter) and advanced LCC (Line Commutated Converter) deployments are transitioning from proof‑of‑concept to repeatable, utility‑scale implementations. Procurement schedules, permitting timelines, and financing terms established in 2026 will determine which projects capture early upside from the forecasted market expansion.
HVDC Transmission System Market -
Regulatory standardization is accelerating. New recommendations and technical reports are being published to harmonize planning, documentation, and interconnection practices for HVDC. These frameworks reduce engineering uncertainty for well‑prepared sponsors but also raise the bar for compliance and system integration capability during procurement.
HVDC Transmission System Market -
Supply‑chain dynamics are increasingly decisive. Cable and converter equipment costs remain sensitive to raw material trends (notably copper for cable conductors), while certain manufactured subassemblies — assembled circuit breakers, for example — are emerging as critical path items for project schedules. Procurement strategies that do not explicitly mitigate long lead items risk schedule slippage and cost escalation.
What PW Consulting’s report delivers (operational, transaction‑ready content)
-
Market sizing and scenarios: validated historical series (2020–2025), base year calibration (2025), and probabilistic forecasts through 2032. Readers will find top‑line trajectories and multiple demand scenarios tied to policy and technology adoption paths.
-
Technology deep‑dive: comparative evaluation of VSC and LCC architectures, multi‑terminal and back‑to‑back configurations, converter station design considerations, and the systems‑level tradeoffs that drive Opex and availability outcomes.
-
Supplier benchmarking toolkit: multi‑attribute scorecards covering technical footprint, installed capacity, delivery track record, warranty provisions, and interoperability. This toolkit is built to be applied directly in RFP preparation and vendor scoring workshops.
-
Procurement and contracting playbook: model tender documents, recommended contract clauses addressing long lead items, liquidated damages, performance guarantees, and intellectual property considerations for multi‑vendor integration.
-
Supply‑chain risk maps and mitigation options: component‑level lead time heatmaps, alternative sourcing pathways, and pre‑qualification checklists for critical subassemblies.
-
Project economic models: CAPEX/OPEX templates, TCO calculators, and payback scenarios under multiple tariff and congestion assumptions to support financial close and investor due diligence.
-
Regulatory and stakeholder roadmaps: scenario playbooks for the adoption of emerging standards and regional permitting practices, plus stakeholder engagement templates for cross‑border interconnects and city‑center infeeds.
Competitive landscape — strategic takeaways
The HVDC supplier ecosystem combines global system integrators, converter and transformer specialists, and cable manufacturers. Market leadership has consolidated around a handful of system suppliers and cable houses; top firms capture a material share of market volumes while a wider set of regional and vertically integrated vendors competes on cost, speed, and localization.
-
Siemens Energy (Germany) — positions itself with flexible symmetric monopole and bipole architectures suitable for point‑to‑point, multi‑terminal and back‑to‑back systems. Expect Siemens to compete where architectural flexibility and global project execution capability matter most.
-
Hitachi Energy (Switzerland) — active across VSC (HVDC Light®) and classic LCC systems, with strong control and protection stacks tailored for offshore wind and dense urban infeeds. Recent large turn‑ons and transportation milestones demonstrate both operational maturity and a capability to handle outsized equipment logistics.
-
ABB (Switzerland) — continues to leverage pioneering converter innovations and a strong offshore track record. ABB is likely to lead in projects where converter efficiency and long‑distance bulk transfer dominate selection criteria.
-
GE Vernova (United States) — with a sizeable installed base, it competes on customization and proven scale, particularly for large utility corridors and integrated transmission‑generation programs.
-
Mitsubishi Electric (Japan) — focuses on VSC solutions aimed at renewable integration and grid stabilization, making it a natural contender for projects prioritizing dynamic response and black‑start capabilities.
-
Cable specialists (NKT, Nexans, Prysmian, ZTT) — these players are indispensable for subsea and land link deliveries. Their project‑execution risk profiles and marine engineering competence will often dictate the feasibility of long‑distance offshore links.
-
Regional and vertical integrators (LS Electric, NR Electric, others) — these vendors provide attractive local content solutions and rapid project mobilization; however, integration risk and interoperability with global converters remain due diligence areas for buyers.
Strategically, buyers in 2026 should embrace multi‑vendor sourcing for converters and cables where possible, insist on clear interface management, and prioritize vendors with demonstrated multi‑terminal experience. The market’s competitive structure means large suppliers command scale advantages, but regional challengers can win by shortening lead times and offering favourable localization terms.
Recent market signals and supply‑side noise
-
Operational wins and deliveries observed in 2025–2026 signal accelerating commercial maturity — including major city‑infeed switch‑ons and deliveries of transformer hardware of record size — reinforcing that projects once scoped as R&D are now mainstream executions.
-
Raw‑material dynamics: cable cost exposure to copper remains a factor. Published analyses indicate that while global copper markets are susceptible to price swings, demand from HVDC projects alone is not expected to materially reshape regional copper requirements; nevertheless, procurement teams should monitor hedging and supplier pass‑through mechanisms.
-
Standards and regulatory updates are converging on shared planning recommendations for HVDC systems. Anticipate accelerated adoption of harmonized documentation practices that will improve comparability across bids but increase upfront compliance work.
-
Component shortages — assembled circuit breakers and other specialized switchgear — are emerging as critical path constraints. Projects without explicit mitigation strategies are likely to experience the most acute schedule risk.
How executives should use this report in 2026 (practical next steps)
-
Embed the market forecast directly into capital planning cycles. Use the provided scenario outputs to stress‑test project IRRs against higher procurement cost and longer lead‑time permutations.
-
Re‑shape procurement into a capability‑based evaluation. Beyond price, assess vendors on interface management, installed base on similar topologies, ability to meet newly emerging standards, and resilience of supply chains for critical subcomponents.
-
Launch an early supplier alignment program for long lead items. Pre‑négotiation of conditional purchase orders, allocation agreements, and secondary sourcing options will materially reduce schedule risk.
-
Adopt a standards‑first integration plan. Align internal engineering and documentation practices to anticipated regulatory guidance to minimize rework at permitting and interconnection stages.
-
Consider strategic partnerships and M&A selectively. Given the market’s moderate concentration, bolt‑on acquisitions can accelerate capability gaps (e.g., cable manufacturing, converter control software), while partnerships with cable houses can derisk offshore delivery timelines.
Methodology note and access to granular intelligence
This briefing is a strategic synthesis of our full report. PW Consulting’s underlying study is built from proprietary primary interviews, transaction screening, technology assessments, and a bottom‑up project pipeline model calibrated to the 2025 base year. The full report contains the granular regional and application splits, vendor share tables, and project‑level datasets that underpin the topline forecasts cited above. In keeping with our “trailer” approach, those detailed tables and actionable, downloadable templates are gated on the report page — designed to convert strategic interest into operational decisions.
For executives preparing investments, procurements, or strategic partnerships in 2026, this research is intended to be the single most practical, implementable source of HVDC market truth. The next step: access the full PW Consulting HVDC Transmission System Market study to extract the vendor scorecards, contract templates, and project‑level models that directly inform transaction documents and board‑level approvals.
For detailed analysis of this topic, please visit the official page: HVDC Transmission System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com