

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
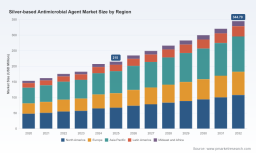
PW Consulting: Silver-based Antimicrobial Market to Hit USD 344.8M by 2032 (6.98% CAGR)

Silver-based Antimicrobial Agent Market: Strategic Brief for 2026 Decision-Makers
Executive snapshot
As PW Consulting’s lead industry analyst, I present a concise lens on the silver-based antimicrobial agent market to inform executive decisions in 2026. This market has demonstrated steady expansion through the recent historical period and is projected to continue growing at a compound annual growth rate of approximately 6.98% across the 2026–2032 forecast window. Measured on the report's base-year footing (2025), the global market rose from about USD 153.4 million in 2020 to USD 215.0 million in 2025, and our modelling points to a trajectory that reaches roughly USD 344.8 million by 2032. The structure of the market remains fragmented (CR3 ~24.6%, CR5 ~26.2%), creating simultaneous opportunities for focused incumbents and disciplined new entrants.
Silver-based Antimicrobial Agent Market
Why this briefing matters for 2026 strategy
-
Timing: 2026 is a hinge year—raw material shocks, new regulatory thresholds, and accelerated product adoption in hygiene-sensitive applications are forcing recalibrations of pricing, sourcing, and certification strategies.
Silver-based Antimicrobial Agent Market -
Risk-reward asymmetry: modest overall market size but attractive growth and high margin potential for performance-differentiated chemistries create clear value-capture pathways for players that manage feedstock exposure and regulatory compliance effectively.
Silver-based Antimicrobial Agent Market -
Fragmentation benefits: with the top firms controlling less than one-third of the market, targeted M&A, licensing, or co-development can materially increase scale and margin without requiring broad, cost-intensive consolidation.
Key market dynamics shaping 2026 choices
-
Feedstock volatility: Silver commodity dynamics matter. A pronounced price surge during 2024–2025 pushed spot prices materially higher, elevating input costs for silver-based formulations and sharpening the need for hedging or alternative carrier strategies.
-
Regulatory tightening: In major end markets, registration and compliance frameworks are becoming more prescriptive. For example, U.S. regulatory authorities require registration data for silver ionic treatments in textiles, and several national standards now restrict certain antimicrobial additives in recycled polymer streams.
-
Supply-side fragility: Short-term production and export shifts for silver nitrate and related intermediates in 2025 produced price and availability volatility—drivers that will influence procurement and inventory strategy in 2026.
What our full report delivers (practical, transaction-ready content)
-
Robust market-sizing and validated forecasting model covering 2020–2032, including sensitivity tests against silver price scenarios and policy shocks.
-
Go-to-market playbooks tailored to key end-use clusters, with channel prioritization, value-proposition templates, and margin models.
-
Regulatory compliance map and certification checklist for priority jurisdictions, including pre-clearance timelines and data submission templates.
-
Supply-chain risk matrix identifying single-point-of-failure suppliers, recommended hedging structures, and alternative carrier pathways to reduce silver-loading intensity.
-
Competitive benchmarking and capability heatmaps: technical differentiators, IP posture, commercial reach, and likely strategic moves for market leaders and challenger specialists.
-
M&A and partnership screening framework that ranks targets on technology fit, customer overlap, and integration complexity—designed for rapid due-diligence prioritization.
-
Practical cost-to-serve models to evaluate price premium feasibility across product families and geographies under multiple regulatory scenarios.
Competitive landscape—what to watch from incumbent and specialist players
The market features a mix of specialty chemical majors, inorganic specialist manufacturers, and additive-focused formulators. Each category brings different strategic advantages: scale and distribution from the majors, niche technical IP from specialists, and application know-how from additive houses. Notable players include manufacturers from Japan and Europe with inorganic carrier expertise, North American and European formulators with strong textile and polymer channels, and several chemistry-specialist firms focused on healthcare and hygiene segments.
-
Major chemical companies: These firms can leverage global channels and capital to invest in capacity expansions and acquisitions to broaden portfolios. Recent strategic activity—such as completion of a biocide business transaction in early 2026—signals continued consolidation-minded moves among larger firms seeking to round out antimicrobial offerings.
-
Specialist manufacturers: Players with proprietary inorganic carrier technologies (e.g., glass, zeolite or silicate carriers) maintain technical barriers to entry and can command premium positions in regulated applications where leaching behavior, longevity, and safety data are critical.
-
Additive formulators and textile-focused suppliers: These participants excel at application engineering and downstream certification support, making them preferred partners for OEMs demanding ease-of-integration and validated performance.
-
Cohort developments: Brand repositioning and focused marketing—evident in recent rebranding activity by some specialist firms—reflect a shift toward end-market narratives (e.g., food hygiene, healthcare) that increase willingness to pay for validated antimicrobial claims.
Strategic implications and recommended plays for 2026
-
Short-term (next 6–12 months): Secure feedstock resilience. Lock in forward contracts for silver intermediates where feasible; evaluate tolling or third-party conversion agreements to mitigate capex while ensuring supply continuity.
-
Near-term (12–24 months): Accelerate regulatory readiness. Allocate resources to generate registrable efficacy and environmental fate data for priority jurisdictions and product lines; early submission creates first-mover advantages for textile and medical applications.
-
Commercial (12–36 months): Deploy premium product strategies in tightly regulated end-use verticals. Focus on validated performance and lifecycle claims, where buyers are less price-sensitive and more concerned with certification and traceability.
-
M&A and partnership lens: Pursue bolt-on acquisitions that add carrier technologies, test laboratories, or regional manufacturing footprints. Given the market’s fragmentation, disciplined tuck-ins can lift market share without broad horizontal consolidation.
-
R&D & product strategy: Invest in silver-efficiency technologies and alternative carriers to reduce silver loadings while preserving efficacy—this is a high-return hedge against commodity price cycles and regulatory pressure on silver release.
-
Commercial risk management: Implement tiered pricing and contract structures that allow for commodity pass-throughs or shared upside in the event of further silver price volatility.
How to use our forecast and scenario outputs for board-level decisions
-
Use the CAGR and full forecast series to size investment envelopes and to stress-test internal projections under conservative and aggressive uptake scenarios.
-
Run hedging vs. vertical-integration decision trees using our supply-cost sensitivity models—these quantify payback periods for strategic inventory, backward integration, and alternative carrier adoption.
-
Apply our regulatory timelines to prioritize product launches and to sequence compliance spending: early movers in compliance-constrained segments consistently capture premium placements with OEMs and contract manufacturers.
-
Leverage our competitive scoring when prioritizing acquisition targets: target companies that fill capability gaps (e.g., long-lasting carriers, validated clinical data) rather than only those that increase raw volume.
Risks to monitor closely
-
Commodity-driven margin compression if silver prices remain elevated or continue to spike without corresponding pricing mechanisms.
-
Regulatory shocks—particularly restrictions on additive types in recycled polymers or stricter environmental release thresholds—that can abruptly reclassify route-to-market economics.
-
Technical substitution from non-silver antimicrobial technologies that could pressure demand in specific low-barrier applications.
Concluding note — why invest further in this intelligence
This brief outlines the strategic levers and risk landscape for silver-based antimicrobial agents in 2026. The full PW Consulting study converts these thematic insights into operational tools: granular regional and application splits, supplier-level cost curves, vendor benchmarking matrices, and proprietary scoring models that support acquisition diligence, pricing strategy, and R&D prioritization. Given the market’s projected growth path and the intersection of commodity, regulatory, and application forces, executives who act on high-confidence, scenario-based intelligence in 2026 will materially outpace peers.
Next steps
-
Access the complete report to view the detailed segment analyses, regional demand models, and vendor scorecards that underpin the strategic recommendations summarized here.
-
Contact PW Consulting to schedule a tailored briefing where we walk through scenario outputs, perform a custom sensitivity analysis using your cost structure, and outline an actionable 90-day plan for procurement, compliance, and commercial activation.
For detailed analysis of this topic, please visit the official page: Silver-based Antimicrobial Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com