

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Stationery market to hit USD 230.16M by 2032, growing at 4.85% CAGR — PW Consulting

Stationery Market 2026: Strategic Preview for Decision Makers
As organizations recalibrate portfolios and supply chains for the post-pandemic, inflation-aware era, stationery—long perceived as a mature, low-growth category—has re-emerged as a strategic arena for margin recovery, brand differentiation, and sustainability-led innovation. This preview synthesizes the most consequential signals from our full Stationery Market study (base year 2025) to help executives prioritize choices for 2026. It demonstrates why this market, valued at USD 165.87 Million in 2025 and forecast to expand at a 4.85% CAGR to reach roughly USD 230.16 Million by 2032, deserves active management rather than passive acceptance.
Stationery Market
Why this study matters to 2026 strategy
-
Timing: With key geopolitical and trade shifts crystallizing in 2025–2026, the stationery sector is at an inflection point where input-cost shocks, shifting channel economics and sustainability compliance will reshape supplier footprints and pricing power.
Stationery Market -
Profit pool opportunity: Modest aggregate growth masks divergent performance across product tiers and channels—premium, sustainable and digitally-enabled SKUs are consistently outperforming commoditized assortments. Companies that reallocate investment to these pockets can materially improve gross margins and brand equity.
Stationery Market -
Actionability: The full report translates market sizing, competitive positioning and supply-chain stress tests into a prioritized set of tactical moves—SKU rationalization, channel-specific pricing, and targeted capex for sustainable materials—that can be implemented in 6–12 months.
Market trajectory at a glance
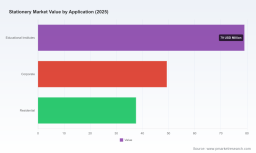
Between 2020 and 2025 the category recovered from pandemic-era disruptions and recorded accelerated expansion, reaching USD 165.87 Million in 2025 (our base year). The forecast horizon (2026–2032) embeds observable drivers—steady demand in education and corporate segments, selective premiumization, and rising adoption of eco-conscious products—and yields a compound annual growth rate of approximately 4.85%. By 2032 the market is expected to approach USD 230.16 Million under the baseline scenario. For corporations, the key implication is not just top-line growth but structural margin improvement potential through product and channel engineering.
Report contents — practical modules that guide 2026 decisions
-
Market sizing and rolling forecast (2026–2032) with scenario overlays: baseline, disruption and accelerated premiumization.
-
Demand drivers and elasticity models for education, corporate and retail channels—translated into SKU-level prioritization and SKU retirement triggers.
-
Supply-chain vulnerability map with near-, mid- and long-term mitigations: supplier diversification, nearshoring sensitivity, and inventory policy trade-offs under tariff pressure.
-
Commercial playbook: channel-specific go-to-market rules, optimized pricing ladders, promotional cadence, and assortment rebalancing templates to lift gross margins.
-
ESG and regulatory impact toolkit: compliance checkpoints, cost-to-implement estimates for sustainable sourcing, and consumer willingness-to-pay benchmarks for eco-labeled products.
-
Competitive benchmarking and strategic moves matrix: capabilities heatmaps for global and regional players, partnership/bolt-on M&A targets, and potential white-space innovation opportunities.
-
Five-year product roadmap scenarios and investment cases—complete with NPV ranges and sensitivity to key inputs such as raw-material price swings and tariff regimes.
Competitive landscape—what incumbents and challengers signal for 2026
The stationery market remains moderately consolidated: the top three players account for roughly one-quarter of revenue while the top five capture around two-fifths of the market. This structure produces meaningful opportunities both for scale-driven incumbents and for agile challengers that can exploit whitespace through branding, channel innovation or niche product leadership.
-
BIC (Clichy, France) continues to blend scale with a sharper sustainability narrative—its 2025 Sustainability Report (published May 2026) and a national school-supply campaign launched the same month underline a dual approach: protect mass-market share while building ESG differentiation.
-
Faber-Castell (Würselen, Germany) and Staedtler (Nuremberg, Germany) remain reference points in premium and professional stationery, where brand heritage and quality command steady pricing power.
-
Japanese producers (Pilot, Pentel, Zebra, Mitsubishi Pencil) maintain competitive strength via product innovation and category variety, particularly in writing instruments where performance and feel matter.
-
China- and India-based manufacturers (e.g., M&G Stationery, Deli Group, Kokuyo Camlin, Beifa) are increasingly important for cost-competitive supply and fast-follower product cycles, but face differentiation pressure absent stronger brand propositions.
-
Newell Brands and legacy US players maintain downstream distribution reach but must contend with input-cost inflation and tariff-driven margin compression.
For 2026, the tactical takeaway is clear: consolidation or scale alone will not guarantee outperformance. Market leaders that combine cost discipline with targeted premium and sustainable product investments—and that can execute agile promotional mechanics in education and corporate channels—will capture disproportionate upside.
Dynamics reshaping 2026 priorities
-
Tariff and trade adjustments: New tariff policies introduced in 2025 have elevated input costs for import-dependent sectors globally. In the US, import cargo volumes are projected to decline, pressuring companies that rely on long, cross-border supply chains. Strategic responses include selective nearshoring, multi-sourcing contracts with indexed pricing, and hedging raw-material exposure.
-
Sustainability as competitive table stakes: Recent corporate disclosures and campaigns—exemplified by several large players—signal that sustainable product attributes are moving from niche to mainstream. Expect procurement contracts and large institutional buyers (education systems, corporate procurement) to incorporate ESG scorecards as a bid qualifier in 2026.
-
Channel bifurcation and premiumization: E-commerce and value-based retail channels continue to expand share, while institutional buyers prioritize total cost of ownership. Brands that tailor assortments and pricing to channel economics unlock margin expansion without relying solely on volume growth.
-
Product innovation vectors: Material substitution (recycled and bio-based inputs), longevity and refillability, and digital augmentation (smart pens, education-linked microservices) are areas where modest R&D investment produces outsized differentiation.
Strategic playbook for 2026 (priority moves)
-
Re-segment portfolios: Immediately identify the top 20% of SKUs driving 80% of profit and implement a phased SKU optimization program to retire low-margin tail SKUs within 9–12 months.
-
Cost-to-serve recalibration: Reprice channels based on true cost-to-serve and introduce differentiated margin floors for institutional vs retail distribution.
-
Supply resilience: Negotiate flexible multi-year purchase agreements with key suppliers that include volume-flex clauses and indexation to raw-material baskets, and pilot nearshoring for high-risk SKUs.
-
Sustainability monetization: Launch a focused, consumer-facing sustainability line with a clear value proposition and measurable KPIs; track payback over a 24–36 month window.
-
M&A and partnerships: Target bolt-on acquisitions that add route-to-market strengths in prioritized geographies or that provide capabilities in sustainable materials and digital services.
How to use the full report
Consider this preview a strategic compass. The full PW Consulting Stationery Market study converts these directional insights into executable artifacts—detailed supplier scorecards, SKU-level margin models, channel-specific promotional playbooks, and acquisition target lists—so that leadership teams can move from intent to implementation within the fiscal year. For procurement and commercial leaders, the report provides pricing ladders and negotiation scripting; for product and R&D teams, it lays out prioritized materials roadmaps and cost-to-implement matrices.
Final note
Stationery in 2026 is not a legacy cost center; it is a modular set of opportunities—supply resilience, premium product growth, and sustainability monetization—that companies can orchestrate to deliver measurable financial and reputational returns. PW Consulting’s full study contains the granular splits, scenario models and playbooks necessary to translate this positioning into 12–36 month results. For executives evaluating investment priorities in 2026, the structured evidence and tactical roadmaps in the full report will materially reduce execution risk and accelerate outcomes.
For detailed analysis of this topic, please visit the official page: Stationery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com