

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: OEA Market to Reach USD 344.8M by 2032 at 6.98% CAGR

Organic Elemental Analyzer (OEA) Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present a forward-looking strategic primer designed to orient executives, product leaders, and investors as they plan for 2026. This piece synthesizes the core quantitative trajectory of the Organic Elemental Analyzer (OEA) market, interprets structural dynamics that will matter most to buyers and suppliers, and previews the practical, decision-ready tools contained in our full market study. Consider this a high-fidelity trailer: it demonstrates the analytical rigor and actionable framing inside the report while deliberately withholding proprietary granular segment tables to guide you to the source for the complete dataset and supplier scorecards.
Organic Elemental Analyzer (OEA) Market
Market trajectory: the headline numbers that shape strategy
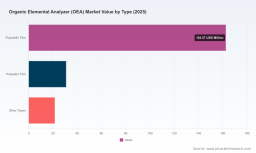
The OEA market reached USD 215.0 Million in the base year (2025) and is projected to expand at a compound annual growth rate (CAGR) of 6.98% through our forecast window (2026–2032). By 2032 the market size is modeled to approach USD 344.8 Million under our central scenario. These headline metrics reflect a market that is neither niche nor commoditized — it is growing steadily, with clear pockets of premiumization driven by accuracy, throughput and integration with downstream analytics (e.g., CHNS/O tools coupling with mass spectrometry and IRMS workflows).
Organic Elemental Analyzer (OEA) Market
Why 2026 is a strategic inflection point
-
Recovery-plus-optimization: Following a period of steady expansion through 2020–2025, 2026 is when capital allocation shifts from catch-up procurement to productivity investment. Organizations will increasingly demand OEA platforms that lower total cost-per-analysis through automation and connectivity.
Organic Elemental Analyzer (OEA) Market -
Regulatory and supply-chain shocks are becoming persistent features. Rather than sporadic, they now influence equipment lifecycles and service models — prompting buyers to prioritize modular, serviceable systems and manufacturers to rethink aftermarket revenue streams.
-
Platform convergence: Expect buyers to favor solutions that are interoperable with analytics stacks (sample prep robotics, chromatography, IRMS, LIMS), favoring suppliers who can deliver validated integration packages over point-product vendors.
Structural characteristics and competitive intensity
The market exhibits a fragmented supplier landscape: the three-largest players account for under one-quarter of revenue and the five-largest share a little over one-quarter, which leaves substantial opportunity for specialized vendors, regional champions, and application-focused newcomers. This dispersion creates tactical openings for fast-followers to win share via focused value propositions (e.g., verticalized applications, consumables-as-a-service, or contract analysis partnerships).
Key capability battlegrounds include analytical precision across micro-to-macro sample ranges, sample throughput and automation, consumables and service economics, and regulatory validation for regulated industries (pharma, food safety, environmental monitoring, and semiconductor fabrication). Suppliers investing in digital service platforms and consumable lock-ins will accelerate margin recovery and lengthen customer lifetime value.
Drivers, friction points and emerging accelerants
-
End-market demand diversification. Applications in life sciences, food & feed, environmental, and advanced materials each present differing value-per-analysis and adoption curves. Strategic entrants should map go-to-market motions to the highest-margin, quickest-adoption use cases first, then scale horizontally.
-
Automation and integration. Buyers signal increasing willingness to pay for validated automation packages that reduce operator variability and improve throughput. This is a durable source of premiumization.
-
Consumables and aftermarket services. Consumable lifecycles and calibration services are a sustained revenue lever. Leading vendors are shifting to bundled or subscription pricing to smooth revenue and deepen customer lock-in.
-
Regulatory clarity and analytical traceability. Stricter documentation and traceable workflows in regulated sectors increase procurement cycles but also raise switching costs for validated systems.
Operational and supply-chain considerations for 2026
-
Component sourcing risk. Critical modules—detectors, furnace assemblies, and high-purity gases—remain potential single-point risks. Manufacturers that diversify suppliers or qualify Tier-2 redundancies will have a resiliency advantage.
-
Service and spare-parts footprint. For global customers, local service presence materially affects procurement decisions. Suppliers expanding regional service hubs will shorten deployment times and convert trials to long-term contracts.
What our report delivers — practical content you can use immediately
The full PW Consulting OEA Market study is structured to be operationally actionable for both buyers and sellers. Highlights include:
-
A concise market model from 2020–2032 with scenario variants (base, conservative, and upside) and explicit assumptions explained so CFOs and strategy teams can run sensitivity tests against CAPEX schedules.
-
Commercial playbooks: segmented go-to-market strategies and pricing templates for OEMs, third-party service providers, and analytical labs.
-
Supplier benchmarking: capability matrices and risk heat maps to support procurement RFPs. (Note: the public primer omits the detailed scorecards and supplier-specific revenue splits; these are available in the paid report.)
-
Regulatory mapping and validation checklists tailored to pharma, food & feed, environmental, and semiconductor verticals—intended for regulatory affairs and QA teams preparing 2026 procurement justifications.
-
Buy-vs-lease and consumables-subscription decision tools with NPV calculators to quantify TCO across common procurement paths.
Competitive landscape — who matters and why
The OEA competitive set is a mix of global instrument OEMs, specialized analyzer manufacturers, and consumables/service specialists. The firms we highlight in the study are representative of distinct strategic archetypes:
-
Thermo Fisher Scientific (Waltham, MA, USA) — A broad industrial and laboratory portfolio combined with validated CHNS/O platforms (e.g., FlashSmart and FLASH 2000 Series). Thermo Fisher competes on integrated workflows and channel depth, making it a default option for large laboratories and regulated environments. ( https://www.thermofisher.com)
-
LECO Corporation (St. Joseph, MI, USA) — Known for macro-combustion analyzers (e.g., the 828 Series) and a strong presence in food and feed testing. LECO’s strength lies in verticalized application support and established service networks in targeted segments. ( https://www.leco.com)
-
Elementar Analysensysteme (Langenselbold, Germany) — Offers multi-element simultaneous analyzers (e.g., vario EL cube) that appeal to labs needing extended-element capability (including oxygen and halogens). Elementar’s engineering focus and European footprint are competitive differentiators. ( https://www.elementar.com)
-
OEA Laboratories (Exeter, UK) — A specialist supplier of elemental analysis consumables and accessories, crucial for labs seeking cost-effective supply and calibration materials. Niche specialists like OEA Labs can capture aftermarket share without selling instruments. ( https://www.oealabs.com)
-
PerkinElmer (Waltham, MA, USA) — A legacy analytics firm offering CHNS/O platforms (e.g., 2400 series) with strong channel and service capabilities in multiple regulated sectors. PerkinElmer competes on validated applications and long-term service contracts. ( https://www.perkinelmer.com)
Each supplier archetype maps to specific buyer needs: global systems vendors for validated, end‑to‑end deployments; specialist OEMs for technical differentiation; and consumables/service providers for aftermarket capture. Our full report contains comparative capability matrices and RFP-ready vendor questions to accelerate procurement diligence.
Strategic moves we recommend for 2026
-
Buyers (corporate labs, contract labs, OEMs): Treat 2026 as an optimization year. Prioritize platforms that reduce per-test variability and integrate with your LIMS/IRMS stack. Insist on consumable and service SLAs in procurement contracts.
-
Sellers (OEMs and service providers): Differentiate through validated automation packages, subscription-based consumable models, and regional service expansion. Invest in digital tools that prove value (downtime reduction, traceability) during pilot phases.
-
Investors: The market’s sub-30% three-firm concentration and modest growth rate (CAGR ~7% across 2026–2032) signal opportunities for specialist consolidation, bolt-on acquisitions that add consumables or services, and software-enabled aftermarket plays.
How to use this primer — and where to get the full intelligence
This preview is designed to give you the strategic orientation needed to prioritize 2026 projects: CAPEX approvals, vendor shortlists, M&A screening, and product roadmap adjustments. To convert these strategic priorities into executable plans, access the full PW Consulting OEA Market Report, which includes:
-
Complete, downloadable market models and interactive scenario tools;
-
Vendor scorecards with supplier-specific advantages, validated integrations and pricing bands;
-
Sample RFP templates and technical validation protocols for procurement teams;
-
Actionable three- to five-year roadmaps for both buyers and sellers.
We intentionally withhold granular segment tables and supplier revenue splits in this public primer to protect the competitive value of the analytics and to invite a direct engagement where we can deliver tailored extracts for your specific use case.
Final thought
The OEA market in 2026 is a growth market defined by technical differentiation, aftermarket economics, and systems integration. Whether you are buying, selling, or investing, success hinges on aligning product and commercial models with customers’ growing demand for validated, automated, and serviceable platforms. PW Consulting’s full study equips decision-makers with the models, vendor diagnostics, and playbooks to make those alignments with confidence.
For detailed analysis of this topic, please visit the official page: Organic Elemental Analyzer (OEA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com