

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Irrigation Controllers Market to Reach USD 465.56M by 2032

Irrigation Controllers Market 2026: Strategic Preview for Executive Decision‑Making
As PW Consulting’s Senior Strategy Advisor and Lead Industry Analyst, I present a curated, high‑value preview of our Irrigation Controllers Market research—designed specifically to inform boardroom conversations and capital allocation choices in 2026. This briefing synthesizes the market’s trajectory, competitive dynamics, regulatory inflections, and actionable strategic options while preserving the granular segment data that are contained exclusively in the full report.
Irrigation Controllers Market
Why this research matters for 2026 decisions
- Companies facing product portfolio, channel, or M&A decisions need a clear view of demand growth, concentration, and the policy forces shaping adoption. Our study situates those variables within an empirically grounded forecast informed by historical trends (2020–2025) and scenarios through 2032.
- Infrastructure and ag‑tech investors require defensible assumptions about revenue growth and margin pressure from input cost shocks. We quantify market scale and translate growth into plausible revenue pools for adjacent capabilities (connectivity, analytics, sensors, services).
- Procurement and public sector actors must balance water‑efficiency goals against procurement complexity—this work maps how rebate programs, certification changes, and federal guidance alter procurement economics in 2026 and beyond.
Market trajectory—what the numbers tell us
The irrigation controllers market has transitioned from a niche control hardware market into a fast‑growing platform market. In absolute terms, PW Consulting’s topline model shows the global market expanding from roughly USD 200 million in 2020 to about USD 260 million in the 2025 base year, with our baseline forecast projecting a compound annual growth rate of 8.82% over the 2026–2032 horizon. Under this baseline, overall market value approaches the mid‑hundreds of millions by 2032, driven by accelerated adoption of smart, connected, and standards‑certified controllers.
Irrigation Controllers Market
Key growth drivers reflected in our model include: rising municipal and federal water efficiency mandates; expanding rebate and incentive programs that lower adoption friction; increased micro‑irrigation and precision‑agriculture deployments; and steady product migration from legacy timer controllers to weather‑ and sensor‑integrated platforms. At the same time, the market exhibits moderate‑to‑high concentration: the top three vendors account for the majority share, and the top five capture a clear supermajority—an important signal for prospective entrants, channel partners, and technology integrators.
Irrigation Controllers Market
Segmentation and the “what we publish vs. what we reserve” principle
Our research disaggregates the market by product type, application, and region, and provides granular forecasts, price decks, and unit shipment estimates. In keeping with the “trailer” principle of this executive preview, I will highlight the structure of the segmentation and the strategic conclusions you can draw from it—without publishing the detailed split figures that form the core intellectual property of the study. The full dataset behind this preview includes:
- Type segmentation (weather‑based, sensor‑based, legacy/others) with multi‑scenario adoption curves and implied installed base turnover rates;
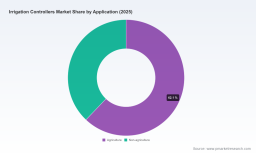
- Application segmentation (agriculture vs. non‑agriculture) reflecting differential replacement cycles and service revenue potential;
- Regional roll‑up with demand drivers and rebate/regulatory overlays for major markets;
- Channel and buyer archetypes—OEM, retrofit installers, water authorities, and farm consolidators—each with unique procurement behaviors and margin expectations.
If you need the precise split tables, unit pricing matrices, or downloadable model, the full report provides them in Excel‑native format along with a walk‑through of assumptions and sensitivity levers.
Competitive landscape: who matters and how they’re positioned
The competitive field combines legacy irrigation OEMs, ag‑tech platform providers, and software‑centric entrants. A few firms anchor the market and set technological and channel norms; others compete by vertical specialization or software differentiation. Our report profiles each of the major players and evaluates strategic levers for 2026:
- Hunter Industries (Tualatin, Oregon) — a leader in Wi‑Fi and internet‑connected controllers with established product lines and Hydrawise integration. Positioning strengths include channel reach into residential and landscape segments and a clear brand in smart consumer installs.
- Rain Bird Corporation (Glendora, California) — notable for modular controllers and weather‑based platforms; deep relationships with professional installers and landscape architects give Rain Bird leverage in retrofit and commercial projects.
- The Toro Company (Bloomington, Minnesota) — competes across residential, commercial, and central control systems. Toro’s DXi central control and Irritrol Rain Master portfolios reinforce its presence in large‑site installations and municipal contracts.
- Netafim (global; North American operations) — brings precision‑agriculture pedigree and drip system integration, which is particularly relevant as growers seek water‑use efficiency and data‑driven irrigation management.
- Galcon (Israel; global) — focuses on advanced smart controllers across residential, agricultural, and specialty segments (e.g., golf), often emphasizing flexible connectivity and modular deployment.
- HydroPoint Data Systems (Santa Barbara, California) — differentiates on software and analytics, emphasizing weather‑based scheduling and enterprise‑grade integrations for commercial customers.
Strategic implications: incumbents are extending into SaaS and services, while software‑first entrants are pursuing hardware partnerships. Margins will increasingly bifurcate between commodity controller sales and recurring services (analytics, remote management, subscription connectivity). For acquirers, tuck‑ins that add analytics, channel access, or certification expertise score highest in our decision matrix.
Regulatory and programmatic tailwinds & headwinds
Regulation and public programs are shaping adoption curves in 2026 more strongly than in prior years. Notable developments that we model explicitly:
- US EPA WaterSense criteria updates (effective March 2026) now require independent certification for certain smart controllers. This creates a near‑term certification runway for compliant vendors and a procurement advantage where rebates require WaterSense labeling.
- Municipal rebate programs in multiple US jurisdictions provide meaningful downward pressure on effective purchase price for end users, raising ROI and shortening payback for smart upgrades—our baseline scenario quantifies the aggregate effect of active rebate programs on adoption velocity.
- Tariff changes announced in 2025 (steel and aluminum) introduce manufacturing cost pressure for hardware‑heavy producers and component suppliers. We quantify the pass‑through risk to ASPs and evaluate hedging and in‑sourcing strategies.
- Federal guidance (FEMP) and public sector deployments demonstrate that advanced controllers can deliver 15%–40% water reduction in institutional applications—an important justification for capital projects and efficiency programs.
For manufacturers and channel partners, the policy environment implies two immediate priorities for 2026: secure WaterSense or equivalent certification where it materially affects rebate eligibility, and build pricing models that reflect higher input costs and possible tariff volatility.
Actionable strategic options for 2026
Based on our scenario modeling and vendor benchmarking, PW Consulting recommends executives consider the following prioritized actions this year:
- Fast‑track certification and rebate‑alignment. Certification is a gate to many public and utility rebate programs. Firms that fail to certify risk losing retrofit and municipal pipeline opportunities.
- Shift portfolio emphasis toward recurring revenue. Product roadmaps should incorporate cloud management, analytics subscriptions, or contracted services—these improve valuation multiples and mitigate hardware margin compression.
- Harden supply chains and diversify components. Given recent tariff-driven input cost shocks, near‑term sourcing strategies (regionalization, long‑term component agreements, and design for lower‑cost materials) reduce exposure.
- Pursue targeted partnerships or bolt‑on M&A. Buyers should prioritize deals that deliver software capabilities, channel reach into commercial/municipal buyers, or certification expertise—each has outsized value in accelerating adoption.
- Differentiate on verification and outcomes. With buyers increasingly focused on water savings (and regulators requiring measurable performance), vendors that provide verifiable outcome reporting will be preferred partners in utility and federal projects.
What the full PW Consulting report contains (practical workbook for teams)
The full market study is built to be operationalized across strategy, commercial, and product teams. Key deliverables include:
- End‑to‑end market model (2020–2032) with scenario toggles, downloadable in Excel.
- Price and ASP matrices by controller class and deployment type, plus margin sensitivity analyses.
- Vendor scorecards (technology, channel, financial profile) and a short‑list of likely acquirers for each vendor class.
- Regulatory tracker and rebate database tied to adoption impact models suitable for business case development.
- Go‑to‑market playbooks for three archetypal companies (incumbent OEM, software platform entrant, and regional integrator) with recommended KPIs and 18‑month roadmaps.
These materials are designed so that leadership teams can run “what‑if” scenarios during strategy offsites and produce investment memos with supporting evidence.
Conclusion — the 2026 strategic imperative
Market growth, concentrated vendor power, and accelerating regulation converge to create a high‑stakes environment in 2026. The opportunity is real—but it is time‑sensitive. Vendors and investors that move early to align products with certification requirements, design for service‑led economics, and shore up supply lines will capture disproportionate value as the market expands at nearly a single‑digit double‑digit CAGR through 2032.
PW Consulting’s full Irrigation Controllers Market report contains the granular forecasts, playbooks, and vendor intelligence to convert these strategic imperatives into executable plans. For decision‑ready insights, model access, and a bespoke briefing for your executive team, consult the full study at our report page.
For detailed analysis of this topic, please visit the official page: Irrigation Controllers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com