

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Iron Ore Market Poised for 3.9% CAGR Through 2032

Iron Ore Market 2026: Strategic Priorities and the Value of PW Consulting’s New Market Study
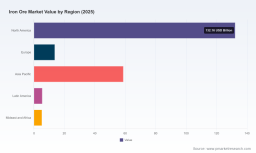
The global iron ore market is navigating a critical inflection point. After recovering from post‑pandemic volatility, the sector reached an estimated market value of USD 215.0 Billion in 2025 and, under the baseline trajectory modeled in our study, is projected to expand toward USD 344.8 Billion by 2032—reflecting a compound annual growth rate of 3.9% across the 2026–2032 forecast window. For corporate leaders making capital, sourcing, and commercial decisions in 2026, this study is designed to convert that macro trajectory into actionable strategy: reallocating capital, re‑sourcing feedstock, and repositioning to compete in a market shaped by concentrated supply, shifting trade policy, and evolving steelmaking technologies.
Iron Ore Market
Why this study matters for decisions made in 2026
- Clarity on near‑term vs. structural trends: The market is influenced by cyclical price swings and one‑off supply events that can obscure durable shifts—particularly the rising role of direct reduction iron (DRI) and pelletized feedstock linked to decarbonization. Our study separates transient noise from structural signals so executives can prioritize investments with multiyear paybacks.
- Concentration and counterparty risk: The market remains concentrated at the top end, requiring customer firms to rethink supplier exposure and contract design. Our analysis quantifies the competitive footprint of leading miners and translates concentration into practical counterparty scenarios.
- Policy and trade shock preparedness: Recent trade policy moves and tariffs have immediate commercial consequences for supply chains and landed costs. The study models tariff shock scenarios and their knock‑on effects to inform pricing, sourcing, and lobbying strategies.
- Capital allocation under uncertainty: With large new supply projects coming onstream and incumbent producers expanding capacity, CAPEX timing and optionality matter. We provide decision frameworks for phased investments and divestments tuned to price and demand scenarios likely to unfold from 2026 onward.
What PW Consulting’s Iron Ore Market Study delivers
- Macro market model: A bottom‑up demand and supply model calibrated to 2020–2025 historical data and projecting through 2032, with scenario toggles for demand elasticity, substitution, and technology uptake.
- Proprietary forecasting engine: Probabilistic price paths and volume scenarios that reflect capital schedules, probabilistic project deliveries, and policy shock matrices—built for integration into treasury and FP&A planning.
- Supply chain mapping: Route‑level analysis of mine-to‑port logistics, bottle‑necks, and cost drivers—delivered as an executive dashboard and a tactical playbook for procurement teams.
- Commercial playbooks: Negotiation templates and contract levers (indexing, quality premia, take‑or‑pay structures) tailored to both buyers and sellers, with play‑tested outcomes under each scenario.
- Project and asset tracker: A continuously maintained universe of greenfield and brownfield projects with milestone risk scores to support M&A, JV, or offtake decisions.
- Regulatory & policy impact modules: Policy stress tests, including tariff reimpositions and emission‑driven demand shifts, with suggested mitigation approaches for different stakeholder groups.
Competitive landscape: how the majors are reshaping the market
Understanding the strategies and execution of the major producers is central to forming competitive responses. The market’s top tier—dominated by the largest global miners—controls a significant share of seaborne supply, and their operational moves in late 2024 through 2026 have immediate implications for pricing, access to high‑grade product, and contractual leverage.
Iron Ore Market
- Rio Tinto Plc (London): Rio Tinto has delivered record Pilbara output and marked major milestones with first shipments from its Simandou project. These developments materially increase high‑grade seaborne availability and change the contestability of premium feeds.
- Vale S.A. (Rio de Janeiro): Vale’s recent production surge to a multi‑year high has tightened the competitive dynamic between Brazil‑based and Australian supply sources, altering lorry and rail logistics relationships and buyer bargaining power in certain corridors.
- BHP Group Limited (Melbourne): BHP’s sustained Pilbara production footprint and capacity optimization programs continue to underpin its global export strategy and cost position.
- Anglo American Plc (London): Anglo American’s premium concentrate output and project focus in South America and Africa underscore an intent to capture higher‑value product segments tied to steel decarbonization pathways.
- Fortescue Metals Group Ltd (Perth): Fortescue’s large‑scale Pilbara operations emphasize throughput expansion and the integration of brownfield efficiency gains as its competitive edge.
- Cleveland‑Cliffs Inc. (Cleveland): The strategic idling of select Minnesota mines and emphasis on stockpile management reflect a tactical approach to the North American cost curve and U.S. domestic demand trends.
- ArcelorMittal S.A. (Luxembourg): Vertical integration moves and new concentrator capacity in Liberia highlight the continued strategic interplay between mining investment and downstream steelmaking security.
Collectively, the top three producers account for roughly half of the seaborne competitive footprint, while the top five consolidate around 60%—a market geometry that favors scale, integrated logistics, and long‑dated offtake strategies. Our report explores how each major’s capacity trajectory and project milestones translate into commercial pressure points for buyers, traders, and mid‑tier producers.
Iron Ore Market
Market dynamics shaping near‑term decision imperatives
- Trade policy shocks: The restoration and step‑up of steel tariffs (notably a 50% tariff reinstatement in early 2025 in one large market) has immediate ramifications for import economics and reroutes global flows. The report models tariff pass‑through and competitive responses for impacted trade lanes.
- Price normalization and volatility: Spot unit values softened in 2025 relative to 2024, with the average imported fines price at Tianjin in the first nine months of 2025 notable for its decline. Our price scenarios stress‑test contractual portfolios across low, base, and upside cases.
- Domestic production shifts: Idling of mines and strategic stockpile drawdowns—such as those observed in North America—change the domestic supply cushion and create short‑run procurement stresses. We quantify the effective domestic availability gap and mitigation tactics.
- Decarbonization and feedstock mix: Accelerating adoption of DRI and shifting steel mill feed requirements are changing demand composition. The study maps feedstock quality requirements against supply readiness and investment pathways for pelletizing and sinter alternatives.
Scenarios and recommended executive actions for 2026
We present three actionable scenarios—Tariff Shock, Supply Surge, and Decarbonization Accentuation—each with a clear set of tactical responses. Below are distilled strategic moves that decision‑makers can initiate immediately:
- Re‑price and re‑structure offtake agreements: Adopt flexible indexing and corridor‑specific clauses to protect margins under tariff and price swings.
- Diversify sourcing and build optionality: Shortlist alternative supply partners and secure contingent logistics capacity to reduce single‑source exposure.
- Phase CAPEX with embedded triggers: Use staged investments with go/no‑go gates tied to price, demand, and regulatory milestones to limit downside while preserving upside.
- Hedge selectively: Combine physical and financial hedges evaluated against cash‑flow models in the report’s forecasting engine.
- Prioritize product quality and decarbonization readiness: Invest in pellet and concentrate compatibility for DRI markets, and negotiate quality premia into long‑term contracts.
- Engage on policy: Coordinate industry and government engagement where tariffs and trade policy materially alter the cost base of domestic steelmaking.
How to extract maximum strategic value from the study
For CFOs, the forecasting engine and stress tests provide forward cash‑flow envelopes to inform capital allocation and hedging. For Heads of Procurement, the supplier scorecards, logistics cost maps, and negotiation playbooks enable immediate renegotiation and contingency planning. For Strategy and Corporate Development teams, the project tracker and scenario playbooks identify priority M&A targets and partnership opportunities aligned to demand and decarbonization trajectories.
PW Consulting’s Iron Ore Market Study is intentionally structured as a decision support toolkit—combining authoritative macro forecasts, granular operational intelligence, and executable commercial playbooks. The narrative and executive dashboards are designed to be read in 60 minutes; the model and datasets are built to be integrated into your 2026 planning cycle.
Next steps
This article highlights the study’s strategic value and the principal forces shaping the iron ore market in 2026. To access the full set of datasets, interactive scenario models, supplier scorecards, and executable contract playbooks, consult the full report and downloadable dashboards on our source page. PW Consulting can also run an executive workshop to apply the report’s scenarios directly to your company’s balance sheet and strategic roadmap.
For detailed analysis of this topic, please visit the official page: Iron Ore Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com