

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Fire Pump Market to Reach USD 482 Million in 2025, Growing at 4.96% CAGR

Fire Pump Market 2026: Strategic Imperatives for Executive Decision-Making
Executive summary
As organizations finalize capital plans and supplier strategies for 2026, the fire pump sector presents a measured growth opportunity shaped by regulatory rigidity, raw-material volatility, and concentrated vendor dynamics. PW Consulting’s latest Fire Pump Market study (base year 2025; historical series 2020–2025; forecast 2026–2032) synthesizes market sizing, scenario forecasts, and executable playbooks to help C-suite and procurement teams convert technical compliance and project-driven demand into defensible commercial outcomes.
Fire Pump Market
Why this research matters for 2026
Fire protection equipment is no longer a purely compliance-driven purchase. For building owners, EPC contractors, and industrial asset operators, fire pump selection affects lifecycle Opex, site reliability, and insurance cost profiles. The dataset underpinning our report shows the market expanding from a 2025 baseline to materially higher levels by the end of the forecast window—consistent with a mid-single-digit compound annual growth rate. Translating that macro growth into actionable decisions requires triangulating standards updates, supply-chain pressure points, and vendor capability differentials; that is precisely what our study delivers.
Fire Pump Market
Market outlook — the numbers that inform strategy
PW Consulting’s topline market sizing tracks a clear trajectory: steady recovery after pandemic-era disruption and a predictable ramp driven by refurbishment cycles, new construction, and specific industrial projects. The modeled forecast (2026–2032) uses a point estimate CAGR that reflects both demand-side drivers and supply constraints. These topline results form the backbone of scenario-based planning in our report, enabling finance and operations leaders to stress-test CapEx timing, spare-parts inventory policies, and supplier diversification plans across a range of plausible market states.
Fire Pump Market
Key dynamics shaping 2026 decisions
- Regulatory continuity with tactical change: NFPA 20 remains the dominant framework governing pump selection and installation; concurrent revisions and evolving certification processes (including updates to ASSE 15010 for inspection and testing) are forcing vendors and end-users to revisit acceptance testing protocols and maintenance contracts. These changes may drive short-term retrofit activity and alter service-contract scopes.
- Raw-material sensitivity: Steel price fluctuations have direct, quantifiable impacts on pump BOM costs and lead times. Procurement teams that modeled steel-price scenarios and hedged supplier agreements in 2025 found measurable protection against margin erosion in early 2026. Our study quantifies the pass-through sensitivity for common pump configurations and offers decision thresholds for switching procurement tactics.
- Project-driven concentrated demand: A number of large offshore and industrial projects awarded in recent quarters have temporary but significant effects on factory utilization and lead times. These episodic spikes make near-term supplier capacity and delivery performance as material to project economics as unit price.
- Service economics and digitalization: Manufacturers increasingly position monitoring and predictive maintenance services as margin-rich attachments. Buyers should evaluate total cost of ownership across both hardware and software/service bundles rather than comparing purchase price alone.
Competitive landscape — what executives must know
The market exhibits moderate concentration at the top: a small set of global manufacturers accounts for a meaningful share of revenue, with the three- and five-firm concentration ratios indicating that leading vendors maintain sizable—but not monopolistic—positions. This structure creates opportunities for mid-tier specialists and regional manufacturers to secure niches where local codes, rapid response, or tailored engineering matter most.
- Pentair (United States) — A global player offering both horizontal and vertical configurations through recognizable sub-brands; strong channel relationships in commercial and institutional projects.
- Grundfos (Denmark) — Integrates fire pumps into a broader pump portfolio; strengths in systems thinking and global aftermarket organization.
- NAFFCO (UAE) — Regional heavyweight that combines equipment and integrated fire-protection solutions for commercial and industrial projects across the Middle East.
- Flowserve (United States) and Sulzer (Switzerland) — Industrial incumbents with capabilities in engineered solutions and large-scale skid integrations, the latter having recently secured FPSO pump skid contracts that underscore its capability in oil & gas projects.
- Kirloskar Brothers (India) , SPP Pumps (UK) , Peerless Pump Company (US) , Armstrong Fluid Technology (Canada) , Rosenbauer (Austria) , Waterous (US) , CET Fire Pumps (Canada) , and Xylem (US) — A mix of specialist and diversified players that compete across segments defined by configuration, mobility (stationary vs. portable), and aftermarket service offerings.
Recent vendor activity highlights tactical shifts you should track: Armstrong launched a new constant-speed vertical-in-line series in early 2026 targeted at high-pressure applications across frequency markets; Sulzer’s contract awards in late 2025 for FPSO pump skids underscore how large energy projects can skew near-term orderbooks. These moves illustrate two trends: product refresh cycles aimed at specific use-cases, and project-level wins that reallocate supplier capacity.
What the PW Consulting study contains — practical, ready-to-use deliverables
Our report is structured to move readers from insight to action. It contains:
- Topline market sizing and an audit of the 2020–2025 historical period, anchored on the 2025 base year.
- Scenario-based forecasts for 2026–2032 with sensitivity to commodity inputs, regulation shifts, and project pipelines.
- Vendor scorecards that evaluate manufacturing footprint, lead-time reliability, aftermarket strength, digital offerings, and compliance track record.
- Operational playbooks for procurement and engineering: supplier evaluation matrices, clause templates for lead-time protection, and spare-parts stocking heuristics tied to pump configurations.
- Project-level case studies that unpack supplier selection in complex environments (offshore FPSOs, large commercial campuses, industrial retrofit programs).
- M&A and partnership heatmaps for corporates and PE investors identifying adjacencies and bolt-on targets.
- Financial models and executive dashboards to run “what-if” analyses (CapEx phasing, maintenance contract bundling, and warranty exposure).
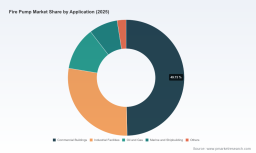
To preserve strategic leverage for buyers and suppliers, this overview deliberately omits detailed segment-level breakout tables and region/application percentages. The full report provides those granulated views, enabling you to align procurement levers and investment timing to specific end-market exposures.
How leading organizations should use these findings in 2026
- Procurement leaders: Rebase supplier scorecards against the updated standards and raw-material scenarios; prioritize dual-sourcing for critical configurations and negotiate lead-time-linked price collars.
- Plant and asset managers: Reassess spare-parts stocks and service agreements in light of evolving inspection standards and the increasing role of remote monitoring to reduce downtime risk.
- OEMs and distributors: Differentiate with integrated services and modular skids to capture project-led opportunities and insulate margins from commodity-driven price pressure.
- Investors and strategics: Use the concentration metrics and vendor capability assessments to identify consolidation targets or strategic partnerships that accelerate entry into high-value niches (e.g., FPSO skids, portable foam systems, digital monitoring).
Risk matrix and early-warning indicators
Our report includes a concise risk matrix with leading indicators that should trigger tactical reviews in 2026, including unexpected commodity spikes, accelerated NFPA or ASSE regulation changes, or a cluster of large project awards in a single supply region. Monitoring these indicators allows teams to convert reactive firefighting into proactive contingency execution.
Final note — the value of granular intelligence
The fire pump market in 2026 is a market of disciplined growth and tactical complexity: steady topline expansion provides opportunity, but winners will be those that translate standards, supply-chain realities, and vendor differentiation into robust procurement and product strategies. PW Consulting’s Fire Pump Market study provides the granular segmentation, vendor-level KPIs, and executable playbooks necessary to operationalize those insights. For organizations that need to refine supplier selection, de-risk project pipelines, or evaluate M&A, the full dataset and appendices in the report are essential.
Next steps
Access the full PW Consulting Fire Pump Market study for the complete set of segment-level breakouts, vendor scorecards, and downloadable financial models that support 2026 decision-making. The executive summary above highlights the primary levers and risks; the complete report converts them into executable plans.
For detailed analysis of this topic, please visit the official page: Fire Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com