

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Aspheric Lens Market to Hit USD 16,593M by 2032 at 8.4% CAGR - PW Consulting
By pmarketresearch, 2026-07-08
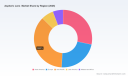
Aspheric Lens Market 2026: Strategic Preview for Executive Decision-Making
Aspheric optics are at the center of a convergence between precision manufacturing, photonics-driven applications and high-volume consumer demands. This market preview, prepared by PW Consulting, synthesizes macro trends and practical levers that corporate leaders must know as they set strategy in 2026. Our full market study (base year 2025) combines quantitative forecasts, supply‑chain stress tests, and actionable playbooks for commercialization, but this introduction emphasizes the strategic implications while omitting the granular segmentation tables reserved for the full report.
Aspheric Lens Market
Why this study matters for 2026 decisions
-
Accelerating scale and structural growth: The global aspheric lens market expanded materially in the early 2020s and reached USD 9,487 Million in 2025. Under our central forecast, the market is expected to grow to approximately USD 16,593 Million by 2032, reflecting a compound annual growth rate (CAGR) of 8.4% across the 2026–2032 forecast horizon. That trajectory creates a multi-year window for revenue capture—but also intensifies competition for high‑precision capacity and qualified supply.
Aspheric Lens Market -
Decision timeframe alignment: For executives planning 12–36 month product roadmaps or 3–5 year capital investments, the interplay between near-term supply constraints and medium-term demand expansion is the critical planning parameter. Our research translates market-level growth into investment thresholds, break-even horizons, and capacity utilization scenarios tailored to different manufacturing approaches (glass molding, polymer injection, diamond turning, CNC grinding).
Aspheric Lens Market -
Risk-adjusted opportunity mapping: Growth alone is not a sufficient signal. We examine where premium value accrues (performance, manufacturability, integration) and where commoditization pressures compress margins. The result is a set of prioritized strategic moves—supply diversification, automation-led cost reduction, M&A targets, or vertical integration—calibrated to company-size and capability profiles.
What the full report delivers (practical content highlights)
-
Decision-ready market model: A living demand-supply model (interactive workbook) that converts the reported market growth into demand volumes by manufacturing method and product-performance tier. The model includes sensitivity levers (pricing, yield, lead time, labor cost) so executives can simulate scenarios quickly.
-
Manufacturing playbook: Comparative cost and throughput benchmarks for diamond turning, precision glass molding, and polymer injection; capex and OPEX schedules; recommended floor plans for mixed‑mode production; and a roadmap for automation investments that materially improve yield and reduce skilled labor dependency.
-
Procurement and supplier strategy: A supplier scoring matrix and audit checklist, tailored contract templates, and a phased supplier-onboarding timeline for rapid qualification under ISO 10110 documentation requirements.
-
Go-to-market and product roadmap guidance: Segment-specific release strategies, platformization templates to reduce SKU proliferation, and commercialization checklists for integrating aspheric optics into systems (camera modules, LiDAR, medical imaging).
-
Competitive and M&A playbook: Profiles for leading players, capability overlap maps, and valuation heuristics for tuck-in acquisitions targeting niche capabilities (ultra-precision metrology, hybrid aspherics, polymer molding). This includes scenario planning for both defensive and offensive M&A.
-
Risk register and mitigation matrices: Practical mitigations for raw-material bottlenecks, carbon-border regulatory exposure (e.g., CBAM implications), and talent scarcity in precision optics manufacturing.
Market structure and concentration — what executives must internalize
The market is neither fully consolidated nor atomized. The top three players account for a significant portion of industry revenue (CR3 ~47.1%), and the top five capture roughly 63.8%. That concentration creates clear implications: scale confers bargaining power with component suppliers and customers, but differentiated technical capabilities still allow focused specialists to command premium margins. For mid-sized incumbents and new entrants, the strategic question is whether to pursue specialization (high-value niche optical solutions) or invest to scale through automation and strategic partnerships.
Competitive landscape: capability map and strategic levers
-
Global optics leaders (e.g., multinational camera and precision optics firms) bring deep integration across lens design, coatings, and system-level optics. Their competitive advantage lies in R&D scale, IP portfolios, and customer lock-in in camera and semiconductor optics supply chains.
-
Mid-tier and specialized vendors (manufacturers of molded glass, diamond‑turned parts, and hybrid aspherics) differentiate on manufacturing innovation, lead-time, and customization. They are frequently preferred suppliers for medical imaging, LiDAR, and defense applications where performance-to-cost trade-offs are highly specific.
-
Electro-optics distribution and systems integrators add value through systems-level service (optical assembly, metrology, and testing), accelerating time‑to‑market for OEMs that lack in‑house optics expertise.
Representative strategic implications for each cluster:
-
Tier-1 multinational optics firms: prioritize system lock-in, expand into sensor/algorithms integration, and protect margin through IP and coatings specialization.
-
Mid-tier specialists: focus on manufacturing process IP (e.g., ultra-precision CNC, diamond turning) and pursue selective partnerships with OEMs in automotive and medical segments.
-
New entrants and scale-ups: consider asset-light service models (co-design + outsourced manufacturing) while building metrology and QA capabilities as a barrier to entry.
Operational dynamics and industry “noise” that influence timing
-
Production cost / labor: Complex grinding and polishing techniques continue to drive up per-unit labor cost and constrain throughput. Automation and in‑process metrology are not optional if organizations are targeting sustainable margins at scale.
-
Raw-material supply: The limited availability of certain high-grade optical glasses and specialty polymers remains a key gating factor. Executives should model procurement lead times and secure material options via long-term contracts or local sourcing where feasible.
-
Regulation and standards: ISO 10110 remains the lingua franca for documenting aspheric lens specifications; compliance reduces rework risk and accelerates qualification cycles for system integrators and OEMs.
-
Geopolitical and carbon regulation: Emerging trade and carbon-adjustment policies (for example, regional carbon border mechanisms) may inflate costs for certain imported inputs and require scenario stress‑testing in supply chain models.
Recent signal events and their implications
-
Technical publications and knowledge sharing: A January 2026 application note from a specialized optics firm emphasized polymer injection molding and integrated supply-chain approaches to reduce lead times—underscoring that process engineering advances are shifting where value is captured in the value chain.
-
Industry convenings and metrology focus: Events focused on manufacturing and metrology indicate industry attention on tolerancing, measurement repeatability and yield improvements. Leaders who invest early in metrology and closed‑loop manufacturing will shorten qualification cycles and secure premium customers.
Where to compete — strategic options for 2026
-
Operational excellence: Invest in automation and in‑line metrology to convert labor- and tolerance-driven disadvantages into predictable, scalable manufacturing. This path suits players targeting higher volume, lower variety segments.
-
Specialization and performance premium: Concentrate on hybrid aspherics, ultra-precision optics for LiDAR and medical imaging, and deepen certification capabilities for regulated markets. This route preserves margin in an otherwise competitive growth environment.
-
Partnership and platform strategies: Build modular optical sub-systems and co-development partnerships with sensor and semiconductor players to lock-in customers and expose new cross-selling channels.
-
Vertical integration: For firms exposed to material or process risk, integrating upstream (glass suppliers, coating houses) or downstream (assembly and testing) can stabilize margins but requires careful ROI discipline.
Immediate actions for executives (first 12 months)
-
Run a 90‑day supply‑chain stress test: model lead‑times for critical glass types and polymer resins under three disruption scenarios, and identify two alternative qualified suppliers for each critical input.
-
Prioritize metrology investments: pilot in‑line interferometry and automated surface inspection on one production line to benchmark yield improvements and cycle time reductions.
-
Customer portfolio review: segment customers by margin-to-effort and develop targeted commercialization playbooks for the two highest-margin segments where aspherics are mission‑critical.
-
Capability gap audit: map internal competencies vs. target profiles (precision molding, diamond turning, coating, assembly) and define a 12–24 month capability investment plan tied to explicit revenue triggers.
What we withhold here — and why you should access the full report
This preview intentionally omits the detailed regional and application-level splits, granular pricing curves, and the full company-by-company revenue benchmarking that underpin our recommendations. Those segmented datasets and interactive models are core deliverables in the full Aspheric Lens Market report and are necessary to translate the strategic options above into executable business plans and financial models. If you are planning capital allocation, M&A screening, or a product commercialization timeline in 2026, the actionable datasets in the complete study are indispensable.
Closing: the strategic imperative
The aspheric lens market offers sustained growth driven by higher‑value imaging systems, automotive sensing, and medical instrumentation. But growth will favor organizations that move beyond product-centered competition to control critical manufacturing capabilities, secure supply for high‑grade materials, and embed rigorous metrology and standards into their workflows. Our full report provides the detailed, transaction‑ready intelligence—forecasts, supplier matrices, and investment cases—required to translate this market expansion into defensible, profitable scale.
For access to the full dataset, segmentation tables, company valuations and decision-ready models, consult the PW Consulting Aspheric Lens Market report and its interactive appendices.
For detailed analysis of this topic, please visit the official page: Aspheric Lens Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Silica Gel Desiccant Market to Reach USD 344.79M by 2032 at 6.98% CAGR
By pmarketresearch, 2026-07-08
Silica Gel Desiccant Market — Strategic Preview for 2026 Decision-Making
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concentrated executive preview of our new Silica Gel Desiccant Market study. This briefing is designed as a high-value “trailer”: it surfaces the critical macro trends, competitive moves, and tactical questions executives must resolve in 2026 — while intentionally withholding proprietary segment-level tables and the detailed breakdowns that power tactical execution. Our objective: equip leadership with the strategic framing needed to prioritize investments, then direct them to the full report for the exact, transaction-grade data.
Silica Gel Desiccant Market
Market trajectory and strategic magnitude
Silica gel desiccants have moved from a niche industrial input into a broadly embedded moisture-control technology across pharmaceuticals, packaging, electronics, and specialty industrial uses. On a macro basis the market has demonstrated steady expansion: the market grew from approximately USD 153.4 Million in 2020 to USD 215.0 Million in the base year 2025, and our modeling projects a continuation of this growth to roughly USD 344.8 Million by 2032. This pathway implies a compound annual growth rate of about 6.98% through the 2026–2032 forecast period — a profile that supports both organic expansion plans and selective strategic M&A.
Silica Gel Desiccant Market
Why this study matters to your 2026 decisions
- Capital allocation: Aligns short-list capex investments to realistic demand scenarios and supplier capacity constraints.
- Procurement strategy: Informs hedge vs. spot decisions for sodium-silicate and other feedstocks after the late-2025 input-price shock.
- Regulatory and go-to-market timing: Clarifies which product formats and material certifications are now table stakes for pharma and nutraceutical customers.
- Commercial prioritization: Helps sales and BD teams choose which product formats, pack-styles, and channels to emphasize over the next 12–36 months.
Report composition — what's in the full study
The report is structured to move from diagnosis to execution. Key deliverables include:
Silica Gel Desiccant Market
- Market sizing and trend matrices (2020–2032) with sensitivity bands that reflect raw-material volatility, regulatory shifts, and format adoption rates.
- Scenario-driven demand models (base, cost-shock, and innovation-acceleration) that quantify volume and revenue outcomes at a product portfolio level.
- Supplier and capacity maps with a proprietary supplier-credit and concentration scorecard — including CR3 and CR5 concentration indicators to highlight systemic supply risk.
- Unit-cost build-ups and pass-through matrices for key feedstocks (notably sodium silicate), enabling near-term pricing playbooks and contractual language for cost escalation.
- Regulatory compliance checklists and packaging certification matrices (FDA/EU compliance, USP <670> applicability, ISO facility considerations) tailored to pharma, food, and nutraceutical applications.
- Commercial playbooks: product positioning, pricing sensitivity analysis, and channel economics for strip desiccants, packets, and engineered-sorbent solutions.
- M&A and JV due-diligence templates, including integration scorecards and an acquisition valuation model calibrated for the industry’s margin structure and concentration dynamics.
Dynamics shaping 2026 choices
- Feedstock cost volatility — operational leverage. Sodium silicate feedstock prices rose sharply in Q4 2025, and manufacturers have been passing through higher production costs. This development alters short-term gross-margin expectations and makes procurement contracting and hedging a first-order priority for 2026.
- Format and packaging innovation. Continuous strip desiccants — now offered with FDA and EU-compliant materials and options aligned to USP <670> — are rapidly moving from novelty to mainstream in high-speed automated packaging lines. Product innovations that incorporate AI-enabled inspection and bio-based, plastic-free packaging are changing both unit economics and sustainability profiles.
- Capacity reconfiguration. Recent capacity projects and plant realignments indicate a decoupling of capacity from historical footprints: incumbents are both expanding high-value fumed-silica capability and consolidating legacy sites to optimize unit costs.
- Consolidation and concentration. The market exhibits high concentration: the top three players account for a dominant share of global supply, and the top five even more so. That concentration magnifies the impact of strategic moves by leading suppliers on pricing, availability, and technological standards.
- Regulatory normalisation in pharma and nutraceuticals. The integration of regulatory-compliant strip desiccants and more stringent supplier qualification across major markets raises the bar on documentation, traceability, and material provenance.
Competitive landscape — key players and strategic postures
The competitive set combines global chemical champions, specialized engineered-sorbent firms, and packaging-focused suppliers. Leading participants and their strategic vectors include:
- Clariant AG (Muttenz, Switzerland): Known for Sorb-It silica gel and continuous strip desiccant strips for automated high-speed packaging. Recent product launches include continuous strip desiccant reels with AI-based quality inspection and sustainability features — a signal of where premium adoption is concentrating.
- W.R. Grace & Co. (Columbia, Maryland): Offers a strong specialty silica and desiccant portfolio oriented to pharmaceutical and industrial moisture-control applications. Its strength lies in technical-grade products and regulatory support for pharma customers.
- Evonik Industries AG (Essen, Germany): A leader in fumed silica technologies (AEROSIL family). Recent capacity additions (early 2026) and selective site consolidations highlight a strategy of product-led differentiation while optimizing capital deployment.
- Multisorb Technologies (Buffalo, New York): Focuses on engineered desiccants for pharmaceutical and food applications; competitive on tailored solutions and regulatory familiarity.
- Fuji Silysia Chemical (Tokyo): Specializes in synthetic silica and is an innovation source for chromatography and catalyst-related silica applications that overlap with high-end desiccant needs.
- Sorbent Systems, Desiccare, AGM Container Controls: These players form the ecosystem of custom-packaging, indicating/non-indicating options, and container-specific desiccant solutions for electronics, military/aerospace, and specialized packaging markets.
Strategic takeaway: leaders are converging on two priorities — product-format innovation (continuous strip, indicating chemistries, bio-based packaging) and a lean-capacity posture that preserves margin while exposing supply to concentrated market risk.
Executive decision frameworks for 2026
- Procurement & supply: Establish layered supplier relationships (core long-term agreements with top-tier producers + nimble spot exposure to regional specialists). Require contractual escalation clauses and transparency on feedstock pass-through.
- Manufacturing & footprint: Re-evaluate existing regional footprints against the forecast growth corridors and the supplier map. Prioritize modular, flexible production that can scale strip-desiccant production quickly.
- Commercial & product: Rebalance portfolios toward high-value formats (regulated strip systems, USP-compliant options) and develop migration paths for existing customers to higher-margin formats with demonstrable automation benefits.
- Innovation & sustainability: Invest in bio-based pack formats and reclaim/reuse narratives where they change buying criteria. Map sustainability claims to verifiable metrics to avoid greenwashing exposure.
- M&A & partnerships: Target tuck-in acquisitions that provide specialized engineered desiccant capabilities, channel reach in pharma/food, or regional manufacturing footprints to mitigate concentration risk.
- Risk & scenario planning: Run stress tests for sustained elevated feedstock costs, a rapid shift to strip adoption, and single-supplier disruptions by top-tier producers.
High-level scenarios to guide near-term action
- Base-case (CAGR ~6.98%): Continued steady adoption; prioritize incremental capacity and targeted product launches timed to customer automation cycles.
- Cost-shock scenario: Persistent elevated sodium-silicate prices — accelerate supplier contracting, evaluate backward integration options, and redesign product packs to reduce material intensity.
- Innovation-acceleration: Rapid switch toward continuous strip and bio-based consumables — expedite certification pathways, invest in automated quality inspection (AI), and secure early-adopter partnerships with packaging OEMs.
What we intentionally withhold here — and why
This preview surfaces the strategic contours and operational imperatives for 2026 but does not publish the report’s granular regional and application-level splits, proprietary supplier-scorecard metrics, or the verbatim financial models that underpin our valuation and M&A templates. Those detailed tables and forecast models are the actionable intellectual property that PW Consulting uses to drive bespoke client outcomes. If your team requires line-by-line segments, price-elasticity matrices, or the supplier-by-capacity dataset, those are available in the full report and through our advisory engagements.
Next steps — how to use this preview
- Download the full Silica Gel Desiccant Market report for the complete dataset, scenario models, and playbooks.
- Request a tailored briefing with PW Consulting to translate findings into a 90–180 day operational plan (procurement, capex, or M&A focus).
- Engage our due-diligence team for transactional support where you’re evaluating suppliers, acquisition targets, or strategic partnerships in 2026.
In an industry where a handful of players and a handful of innovations can reset cost curves and customer standards, the right intelligence — coupled with rapid execution — determines who captures the margin uplift as volumes expand. Our full report provides the exact inputs and executable templates required to move from strategic intent to measurable results. Contact PW Consulting to access the complete study and begin applying the insights to your 2026 decision agenda.
For detailed analysis of this topic, please visit the official page: Silica Gel Desiccant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Hole Saw Market to Grow at 6.98% CAGR Through 2032 — PW Consulting Insight
By pmarketresearch, 2026-07-08
Hole Saw Market 2026: Strategic Imperatives from PW Consulting’s Industry Brief
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise yet rigorous orientation to our Hole Saw Market research — a tactical briefing designed to inform executive decision-making in 2026. This piece demonstrates the analytical depth and the practical, transaction-ready insight you will find in the full report. It deliberately surfaces high‑value signals and strategic implications while withholding granular sub‑segment tables and proprietary splits to guide you to our full deliverable for transaction-level intelligence.
Hole Saw Market
Why this market matters in 2026
The hole saw market has moved from a niche consumable into a strategically relevant industrial category: it sits at the intersection of tool performance, materials innovation, construction cycle dynamics, and utilities/municipal specification requirements. Between 2020 and 2025 the market demonstrated resilience and steady recovery from pandemic-era volatility, evolving from a mid‑single‑hundred million USD industry to a larger, more predictable market base in our 2025 reference year. Our forecast through 2032 anticipates continued expansion, with the market expected to grow at a compound annual growth rate (CAGR) of 6.98%, reaching a mid‑three‑hundred million USD figure by 2026 and projecting to exceed half a billion USD by 2032.
Hole Saw Market
For executives evaluating capital allocation, product portfolio pivots, or M&A choices in 2026, these topline dynamics matter: they signal a market with growth potential sufficient to support new product introductions, premiumization strategies, and consolidation plays — provided those moves are informed by operational and channel realities that we map in the full study.
Hole Saw Market
Macro drivers and strategic context
-
End‑market momentum: Durable construction activity, a steady stream of retrofit and utilities projects, and a growing professional tool market underpin demand for high‑performance hole cutting solutions. The market’s growth profile reflects both volume expansion and mix shifts toward higher‑value geometries and materials.
-
Materials and tool technology: Advances in high‑speed steel (HSS), cobalt‑enhanced HSS grades, carbide teeth and diamond brazing are not incremental; they alter product lifecycle economics, warranty positioning, and service claims. Suppliers that convert material advances into demonstrable operator time savings and lower total cost of ownership will command premium pricing and channel preference.
-
Specification and regulation: Municipal and infrastructure contract language increasingly specifies hole forming methods and standards to avoid damage to mainlines and structurally critical elements. This regulatory backdrop creates a reliable baseline of demand for compliant, precision solutions — a factor that favors established vendors with certified product lines and documented use cases in utility and public works projects.
-
Concentration and competitive dynamics: The landscape is materially concentrated. Top vendors capture a substantial share of market value and distribution reach, creating both barriers for smaller challengers and platform opportunities for strategic acquirers seeking bolt‑on technology or channel access.
What the full report delivers (practical, transaction ready)
Our 2026 Hole Saw Market report is built for action. The deliverable combines robust market sizing and forward forecasts (2026–2032) with operational playbooks that procurement, product, and corporate development teams can apply immediately. Highlights include:
- Demand modeling that isolates macro and micro drivers, with scenario runs for construction cycles, material cost shocks, and rental versus purchase behavior;
- Go‑to‑market blueprints for premium vs. value tiers, channel optimization for pro dealers vs. mass retail, and distributor segmentation to prioritize return on coverage;
- Commercial due diligence templates and acquisition screening criteria keyed to synergies in manufacturing footprint, metallurgy capability, and complementary accessory ecosystems;
- Pricing and warranty frameworks informed by performance benchmarking and cost‑pass through sensitivity to raw material inputs;
- Supply chain heat‑maps and mitigation strategies — from alternate alloy sources to modular manufacturing cells — that preserve gross margin under input volatility;
- Regulatory compliance mapping for public works and utility tenders (ANSI and municipal specifications), enabling bid teams to pre‑certify product acceptance;
- KPIs and early‑warning indicators for volume shifts, channel inventory buildups, and competitive product launches;
- Practical product development pipelines with time‑to‑market estimates, prototyping cost ranges and recommended pilot programs for cordless‑optimized and impact‑capable hole saws.
Competitive landscape: what leading players are doing
The competitive set includes multiple legacy tool manufacturers and specialty brands that have each carved defensible positions through product systems, warranties, and channel relationships. Key strategic postures we analyzed:
-
LENOX (U.S.): System‑centric play — integrates blade design with arbors and accessories. Their speed‑and‑durability messaging targets contractors looking to reduce downtime and tooling breakage. Strategic implication: system bundling increases lifetime value and creates cross‑sell opportunities.
-
Greenlee (U.S.): Niche focus on professional electricians and industrial hole‑making accessories. Their strength lies in deep channel trust among trade professionals and specification visibility in industrial procurement. Strategic implication: maintain tight channel relationships and leverage specialty distribution as a defensive moat.
-
Milwaukee Tool (U.S.): Performance and cordless optimization — warranties and speed claims play well in the pro power‑tool ecosystem. Their brand and innovation cadence make them a natural disruptor in premium segments. Strategic implication: incumbents should consider performance guarantees and OEM tool integrations to remain competitive.
-
RIDGID, IRWIN and Starrett (U.S.): Broad industrial portfolios and strong trade recognition. These firms compete on heritage, reliability and availability across trades channels. Strategic implication: incremental innovation and aftermarket services can sustain pricing power.
-
Morse Cutting Tools and Diablo Tools: Focused innovation — quick‑change impact compatibility and carbide/rough‑in solutions for demanding substrates. Strategic implication: targeted product differentiation focused on specific contractor pain points opens premium segments.
Recent industry moves — trade‑show showcases, large‑range stockings by major distributors, tutorials and product launches — underscore an active commercialization environment. These developments accelerate adoption curves for newly optimized geometries and drive faster OEM endorsement cycles.
Strategic implications for 2026 decisions
For boards and business unit leaders planning 2026 allocations, the hole saw market presents several discrete opportunities and risks. Key recommendations we draw from our analysis:
-
Prioritize product architectures that deliver measurable operator productivity gains. Investments that demonstrably shorten cycle time or reduce blade replacement frequency translate into premium pricing and wider specification acceptance.
-
Rethink sales coverage with a two‑track channel approach: a premium, specification‑led route for utility and industrial projects; and a high‑service, availability‑led route for construction and rental customers. Channel economics in this market reward differentiated stocking strategies.
-
Build raw‑material hedging and second‑source arrangements for HSS and carbide inputs. Small shifts in input cost can compress margins quickly; a resilient sourcing plan is table stakes for margin preservation.
-
Use M&A selectively to acquire complementary metallurgy capabilities, rapid prototyping, or distributor footprints. Given the market’s concentration, bolt‑on transactions can yield meaningful market access acceleration without the integration challenges of large horizontal deals.
-
Leverage regulatory familiarity as a differentiation axis. Companies that document compliance for utility and public works projects reduce sales friction and become first‑choice suppliers for specification‑driven contracts.
-
Operationalize a product lifecycle and warranty playbook that aligns with digital traceability (batch‑level performance data) to reduce claims and improve product improvement cycles.
Risk factors and scenario planning
Key downside scenarios we model in the full report include: a sharp slowdown in industrial retrofit cycles, a raw‑material shock that tightens margins without pass‑through ability, and an aggressive price war initiated by a mass‑retailer private label. Each scenario is accompanied by mitigations: re‑prioritizing SKUs, temporary premium feature offers, and rapid price‑value communications to channel partners.
How to use this briefing
Consider this briefing the strategic overlay: it identifies where to focus 2026 decision energy (product performance, channel segmentation, supply resilience, and targeted M&A). The PW Consulting full report provides the granular build‑up — the segment‑by‑segment demand tables, regional and application splits, price points, and the tactical M&A shortlist that power deal execution and commercial planning.
Next steps
-
For corporate development: request the acquisition screening annex that maps strategic fit against operational synergies and valuation sensitives.
-
For product and operations leadership: review the prototype cost and manufacturing cell scenarios to quantify time‑to‑market for cordless‑optimized and impact‑capable products.
-
For sales and channel teams: engage with our distributor segmentation dashboards and the pricing elasticity experiments to optimize SKU localization and margin capture.
PW Consulting’s Hole Saw Market study combines market mechanics, competitive intelligence and execution playbooks tailored for 2026 decision timelines. To access the full dataset, proprietary segmentation, and the complete set of tactical templates that enable execution, please consult the source webpage referenced in our release. The granular numbers, scenario matrices and deal checklists you need to move from strategy to execution are contained there.
PW Consulting — actionable insight, designed for execution.
For detailed analysis of this topic, please visit the official page: Hole Saw Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Disposable Tableware Market Poised for 4.02% CAGR Through 2032
By pmarketresearch, 2026-07-08
Disposable Tableware Market — 2026 Strategic Brief: Navigating the Transition from Compliance to Competitive Advantage
PW Consulting presents an executive-introductory perspective on our full Disposable Tableware Market study (base year 2025, forecast 2026–2032). This brief explains why the study matters for board-level and commercial decisions in 2026, how the market’s structural dynamics will shape value creation, and what practical moves manufacturers, brand owners, distributors, and private equity investors should prioritize. We demonstrate analytical depth and decision-useful insight while intentionally withholding the granular splits and proprietary model outputs that are available in the full report.
Disposable Tableware Market
Market at a glance: baseline and trajectory
The disposable tableware market has moved from recovery to measured expansion. On a global basis, the market reached USD 168.0 Million (revenue unit: Million USD) in our 2025 base year after an accelerated rebound from the 2020 trough. Looking forward, our forecast embeds a 4.02% compound annual growth rate (CAGR) for 2026–2032, with the market approaching roughly USD 221 Million by 2032 under the central scenario. These headline numbers mask important transitions — in materials, policy-driven demand shocks, and channel shifts — that will determine who captures the next wave of margin expansion.
Disposable Tableware Market
Why this research matters for 2026 decision-making
- Regulatory-driven demand shifts are now strategic : Recent policy decisions (for example, state and national bans and prohibitions that came into force during 2024–2025) have materially reallocated demand away from certain legacy materials toward molded-fiber, paper-based and recyclable/compostable alternatives. Companies that treat regulation as a recurring operational risk rather than a one-off compliance cost will unlock first-mover advantages.
- Sustainability credentials are table stakes — but with commercialization nuance : Innovations and approvals that expand allowable recycled content change both raw-material economics and go-to-market claims. The acceptance of high Post-Consumer Recycled (PCR) content for food-contact items creates a pathway to lower-cost circular feedstocks — but it requires validated supply chains and regulatory documentation to convert procurement contracts.
- Fragmentation creates roll-up and margin-improvement opportunities : Market concentration metrics indicate a fragmented competitive field (CR3 ≈ 22%; CR5 ≈ 28.5%), leaving room for scale-driven cost reduction, brand consolidation in key channels, and targeted M&A to secure fiber and compostable capacity.
- Commercial models must be retooled : Pricing strategies, channel incentives, and contract terms that worked in a legacy EPS/plastic environment will underperform in a multi-material market where cost drivers, shelf-life claims, and end-of-life handling differ materially.
Regulatory and innovation dynamics changing the playing field
- Policy interventions that took effect in 2024–2025 have redirected procurement and product roadmaps. Notably, statewide EPS restrictions and single-use plastics prohibitions have accelerated adoption of alternatives and prompted foodservice buyers to change supplier qualification criteria.
- Material innovation continues at pace — from novel paper plate inventions to scalable molded-fiber processes — creating opportunities to substitute higher-emission plastics without eroding consumer utility.
- Regulatory acceptance pathways for recycled content and compostable claims are enabling circular-leaning product strategies, but they require proactive engagement with regulators and certified supply chains to translate into commercial wins.
What the full report delivers — practical, transaction-ready intelligence
We structured the full study around use-cases for decision-makers who must translate insight into action in 2026. Key deliverables include:
Disposable Tableware Market
- Comprehensive market sizing and five-plus scenario forecasts (base year 2025; forecast 2026–2032), with sensitivity to raw-material price swings, regulatory adoption timing, and alternative development curves.
- Segmentation by material, application, and detailed regional breakdowns — including proprietary demand models and addressable-market maps for prioritized country clusters (note: granular splits are available only in the full report).
- Supply-chain and cost-to-serve analytics: raw-material sourcing footprints, converter capacity maps, capex timelines for molded-fiber vs. thermoforming, and margin waterfall models for alternate product constructs.
- Competitive benchmarking and strategic profiles covering major participants and challenger specialists, with M&A scorecards, partner-fit matrices, and integration risk assessments.
- Go-to-market playbooks tailored to manufacturers, brand owners and distributors: channel segmentation, tender templates, price-indexing strategies, and pilot deployment checklists for new-material introductions.
- Regulatory and sustainability action matrix: roadmaps for compliance, certification pathways, labeling strategies, and stakeholder engagement plans (regulators, waste managers, large foodservice buyers).
- Interactive financial model (licenseable) that allows executives to test acquisition scenarios, capex spends, and price shocks against revenue and EBITDA outcomes through 2032.
Competitive landscape: who to watch, and why
The market displays a mix of global converters, brand-house incumbents, and mission-led challengers. Each archetype brings different threats and partnership opportunities for incumbents and new entrants:
- Pactiv Evergreen Inc. — A large-scale converter with integrated paper and plastic offerings for both foodservice and consumer channels. Their breadth makes them a critical counterparty for national retailers and large foodservice distributors; they also have the operational scale to internalize feedstock transitions.
- Huhtamaki Oyj — Known for branded paper and molded-fiber products (including institutional-grade lines), this incumbent has deep R&D in molded fiber and strong go-to-market relationships with foodservice operators seeking branded reliability.
- Dart Container Corporation — A traditional foam and plastic player that is actively shifting portfolio exposure toward compostable lines. Their transition pathway is instructive for other plastic-heavy specialists attempting to reposition without margin erosion.
- Genpak LLC — A high-volume supplier to foodservice operators with capabilities in expanded polystyrene and paper-based formats; their playbook captures the trade-offs between low-cost formats and migration risk under tightening regulations.
- Reynolds Consumer Products Inc. — As a consumer-products house, Reynolds leverages marketing and retail shelf presence to influence household adoption patterns and private-label contracts.
- Novolex, Berry Global — Large-scale manufacturers with diversified portfolios across molded fiber and plastic; their investments in capacity and recycling partnerships are indicators of where scale economics will accrue.
- Green Paper Products, Eco-Products, World Centric — Niche, sustainability‑first specialists driving adoption in institutional and premium channels; their certification expertise and circular supply relationships are often acquisition targets for larger converters seeking credibility.
- Sabert Corporation — Focused on commercial and institutional foodservice, Sabert blends plastic and paper solutions and is an important strategic supplier for high-turnover foodservice concepts.
Taken together, the field shows room for consolidation and for differentiated specialist positions (e.g., cost leader in recycled fiber; premium sustainable brand; integrated circular player). The relatively low CR3/CR5 metrics point to an environment where intelligent aggregation or targeted capability acquisition can produce outsized returns.
Priority actions for executives in 2026
- Regulatory triage (0–3 months) : Run a compliance-impact and procurement requalification audit to identify at-risk SKUs and prioritized customers. Map current contracts to near-term policy deadlines and issue supplier continuity plans.
- Product and supplier pivot (3–9 months) : Execute SKU rationalization and run rapid pilots of molded-fiber and PCR-enabled SKUs with top buyers; negotiate supply agreements that include transitional pricing and shared risk clauses.
- Supply-chain de-risking (6–18 months) : Secure dual-sourced feedstocks, invest in backward integration for critical inputs where unit economics justify, and form strategic alliances with certified composting and sorting partners to protect claims.
- M&A and capacity strategy (12–36 months) : Screen for bolt-on targets that provide immediate access to fiber-processing, compostable-forming, or certification credibility. Prioritize targets that improve gross margin through vertical synergies rather than only market share.
- Commercial rewiring : Reprice contracts to reflect lifecycle costs and end-of-life handling, and segment customers by readiness to pay for certified sustainability vs. price sensitivity.
Methodology & assurance
The study uses a blended methodology: historical reconstruction (2020–2025) built from primary interviews and shipment data, and forward forecasts (2026–2032) combining bottom-up build-ups by product and channel with macro overlays for regulatory adoption and raw-material price paths. Scenario workstreams model accelerated substitution, moderate transition, and delayed adoption outcomes; all scenarios are accessible via the interactive model licensed with the report. Data quality is reinforced by supplier triangulation, buyer panel validation and a legal/regulatory review of jurisdiction-level policies through mid‑2026.
Next steps — where to get the full intelligence
This brief is designed to establish strategic context and immediate action priorities. The full PW Consulting Disposable Tableware Market report contains the granular regional, material and application splits, the interactive financial model, detailed company profiles and our proprietary M&A scorecards that are intentionally excluded here. For access to the complete dataset, licensing options, or a tailored workshop to apply the model to your portfolio, please contact our research team via the PW Consulting portal.
PW Consulting — We help clients convert regulatory disruption and material transition into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Disposable Tableware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: AES Resin Market to Reach USD 185M in 2025, Forecasting 6% CAGR to 2032
By pmarketresearch, 2026-07-08
AES Resin Market — Strategic Preview for 2026 Decision‑Makers
As companies plan capital allocations, product launches, and supply‑chain adjustments for 2026, PW Consulting’s AES Resin Market study offers a strategic compass grounded in empirical trend analysis and executable scenarios. This preview outlines the macro trajectory, competitive dynamics, and the operational playbooks that matter most for executives contemplating investments, partnerships, or portfolio reshaping in the coming 12–36 months. In keeping with our “trailer” approach, we demonstrate the analytical depth that underpins the full study while deliberately withholding granular segment tables and regional shares to preserve the incentive to consult the complete report.
AES Resin Market
Market trajectory at a glance
Between 2020 and 2025 the AES resin market showed steady expansion, reflecting recovering industrial activity and structural demand from mobility, electronics and durable consumer segments. Our dataset, anchored to a 2025 base year, indicates that the market expanded materially over the historical window and enters the forecast horizon with strong momentum. From 2026 through 2032, the market is projected to grow at a compound annual growth rate (CAGR) of approximately 6.0% under our baseline scenario, driven by continued adoption of engineered styrenic blends, premiumization toward weather‑resistant and high‑impact formulations, and selective end‑market recovery patterns.
AES Resin Market
Key implications of this trajectory for 2026 planning:
AES Resin Market
- Volume and premium product demand will both expand — creating simultaneous opportunities for market share gains and margin recovery if firms capture product mix shifts effectively.
- Capital timing matters: incremental capacity or retrofit investments made in 2026 will reach full economic effect as the market migrates toward the upper bound of our forecast window, emphasizing the need for multi‑year P&L modeling.
- Pricing strategy must be informed by near‑term feedstock volatility while keeping an eye on the structural trend that supports higher average selling prices for differentiated grades.
Why this study matters for 2026 corporate strategy
Our research is purposely designed for decision points executives face in 2026: whether to commit to greenfield/expansion projects, pursue bolt‑on M&A, diversify supplier footprints, or reallocate R&D spending toward specialty grades. The report synthesizes quantitative forecasts with qualitative market intelligence so leaders can convert top‑line growth into durable competitive advantage.
- Investment prioritization — Clear guardrails on timing, scale and expected payback for capacity moves under multiple demand scenarios.
- Commercial optimization — Playbooks on product segmentation, channel pricing and specification strategies to extract premium from weather‑resistant and impact‑modified grades.
- Risk management — Actionable mitigation for feedstock and logistics shocks, including contract structures and inventory levers that preserve margins.
What’s inside the full PW Consulting AES Resin Market study (select highlights)
The full study is an operational toolkit for 2026 decisions. Highlights include:
- Rigorous historical baseline (2020–2025) and scenario‑based demand forecasts for 2026–2032 with sensitivity to macroeconomic and raw‑material shocks.
- An integrated cost‑to‑serve and margin model that maps feedstock dynamics to plant‑level profitability under alternate pricing regimes.
- Company scorecards and strategic options analysis for incumbent producers and potential new entrants, including prioritized near‑term actions.
- Go‑to‑market playbooks tailored to major end markets (automotive systems, consumer durables, electronics, and construction) that combine specification roadmaps with channel and OEM engagement frameworks.
- Due‑diligence checklists and M&A valuation sensitivities for buyers targeting scale, technology or geographic complementarities.
- Supplier and logistics risk matrix, with practical contracting templates and inventory policy recommendations for volatile feedstocks.
We intentionally withhold granular regional shares and fine‑grained application splits in this preview to preserve the commercial value of the full dataset and the demand model that supports it.
Raw‑material dynamics and margin pressure — what to watch in 2026
Input costs are the single largest margin lever in the AES value chain. Recent price movements have introduced fresh asymmetry into cost and supply assumptions that will shape strategic choices in 2026:
- Acrylonitrile volatility: Analysts’ tracking shows acrylonitrile prices rose modestly across many regions in Q1 2026 (roughly mid‑single digits), but with sharp regional spikes — notably a documented surge in the U.S. in late March 2026 where spot prices increased dramatically. These events underscore how quickly upstream inventory tightness and feedstock availability can compress gross margins. (Source: Analysts Insights, Q1 2026)
- Regional price baselines differ: Earlier indicators from 2025 show material regional price spreads (e.g., India levels recorded in late‑2025), which create arbitrage and sourcing opportunities for firms with flexible procurement arrangements. (Source: Analysts Insights, Q3 2025)
- Companion elastomer feedstocks: EPDM rubber — a key contributor for impact‑modified grades — displayed easing in Northeast Asia and deeper declines in South America through mid‑2026, changing relative economics for high‑impact formulations and opening short‑term margin relief for certain producers. (Source: Analysts Insights, May 2026)
Strategic takeaways:
- Adopt layered procurement: combine shorter‑term indexed purchases with limited-duration fixed contracts to balance cost savings and risk.
- Prioritize feedstock integration where feasible: firms with upstream access or strategic partnerships gain defensive advantage during tight cycles.
- Operational flexibility: investments in formulation agility reduce exposure to single‑feedstock swings and enable premium capture through rapid product substitution.
Competitive landscape — players to watch and their strategic postures
The AES resin market demonstrates moderate concentration. Top producers capture a majority share of market supply, creating an environment where scale, specialty portfolios, and customer intimacy determine outcomes. In particular, the top three companies account for a meaningful share of capacity, and the top five expand that footprint further — a structure that favors focused, well‑capitalized incumbents while leaving room for targeted challengers.
Selected company perspectives (strategic themes, not exhaustive profiles):
- Established specialty producers emphasize formulation breadth and weather resistance. Their strategic playbooks prioritize high‑value product variants for outdoor, automotive exterior, and construction segments, plus collaborative development with OEMs to lock in specifications.
- Large integrated petrochemical players leverage scale and cost integration to defend general‑purpose volumes while selectively upgrading portfolios toward high‑margin, high‑performance grades.
- Midsized players and regional champions compete through agility — rapid custom formulation, local technical support, and optimized supply arrangements for regional processors.
- New entrants must evaluate route‑to‑market tradeoffs: carve out differentiated niches (e.g., ultra‑weatherable grades or bio‑content blends) or pursue geographic expansion via tolling and JV agreements to avoid heavy upfront capital exposure.
Our full report includes company scorecards for leading names in the landscape, assessing technology positioning, capacity footprints, R&D pipelines, and commercial momentum. Executive teams will find comparative matrices that translate qualitative strengths into quantifiable strategic options.
Actionable strategic pathways for 2026
We recommend decision frameworks aligned to four archetypal objectives. Each pathway includes short‑cycle (0–12 months) and medium‑term (12–36 months) actions:
- Protect margins in a volatile feedstock environment
- Short: renegotiate contracts to include indexation clauses, secure shadow inventories, and pursue tactical hedges for acrylonitrile exposure.
- Medium: evaluate partial vertical integration or long‑term offtake collaborations with feedstock suppliers.
- Capture premium growth from differentiated products
- Short: fast‑track application trials with key OEMs and set up price‑differentiated SKU ladders keyed to performance tiers.
- Medium: invest in R&D for weather‑resistant and impact‑modification technologies and protect IP to sustain pricing power.
- Scale sensibly through partnerships and bolt‑ons
- Short: prioritize M&A targets that add formulation capabilities or regional distribution strength rather than undifferentiated capacity.
- Medium: deploy capacity expansions in stepwise phases tied to binding offtake agreements to de‑risk utilization schedules.
- Strengthen commercial and supply resilience
- Short: implement dynamic customer segmentation and contractual flexibility (volume bands, minimum commitments) to preserve revenue while controlling working capital.
- Medium: diversify logistics routes and develop alternative sourcing nodes to mitigate single‑point failures.
Conclusion — how to use this preview
This preview demonstrates the strategic contours of the AES resin market as firms plan for 2026. The full PW Consulting study delivers the quantitative engine — demand matrices, scenario models, company scorecards and executable playbooks — that translate these contours into boardroom‑ready decisions. If your leadership team is evaluating capacity allocation, M&A targets, sourcing strategies, or product roadmaps for 2026, the complete report provides the dataset and tools to move from strategic intent to tactical execution.
Contact PW Consulting to obtain the full AES Resin Market study and the underlying models that can be integrated into your 2026 planning cycle. Our team stands ready to run custom scenario analyses and apply the market insights to your specific risk profile and strategic ambitions.
For detailed analysis of this topic, please visit the official page: AES Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HNBR Market to Reach USD 883 Million by 2032 at 7.45% CAGR
By pmarketresearch, 2026-07-08
HNBR Market 2026: Strategic Imperatives for Decision‑Makers — A PW Consulting Preview
Hydrogenated Nitrile Butadiene Rubber (HNBR) sits at a strategic intersection of performance elastomers: it is an enabler for higher‑temperature sealing, improved oil resistance, and extended service life across automotive, oil & gas, and industrial applications. Our latest PW Consulting market study — based on a 2025 base year and extending through 2032 — finds the global HNBR market positioned for steady expansion. The market, measured at approximately USD 535 million in 2025, is projected to approach roughly USD 883 million by 2032, equivalent to a compound annual growth rate (CAGR) of approximately 7.45% over the forecast horizon. For executives planning capital allocation, supply strategies, or product road maps in 2026, the findings point to a narrow set of high‑leverage strategic choices that will determine competitive outcomes.
Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Why this study matters for 2026 decisions
-
Timing of capacity investments. The market growth profile and recent capacity moves among leading producers create both opportunity and risk: being early to secure feedstock or offtake arrangements materially improves margin capture, while late entrants risk oversupply in selected corridors.
Hydrogenated Nitrile Butadiene Rubber (HNBR) Market -
Feedstock exposure. HNBR economics are tightly coupled to butadiene and hydrogenation costs. Volatility in spot butadiene pricing and regional feedstock spreads creates pronounced margin sensitivity — a core operational risk that should be centrally modelled in 2026 CapEx and sourcing decisions.
Hydrogenated Nitrile Butadiene Rubber (HNBR) Market -
Regulatory substitution pathways. Regulatory actions targeting PFAS and related chemistries are changing customer specifications for sealing and barrier materials. HNBR is being explicitly positioned as a non‑fluorinated alternative in select sealing duties, which opens new commercial windows but also brings validation and specification timelines that require upstream technical engagement.
-
Consolidation and scale dynamics. The market structure is moderately concentrated — the largest players control a clear majority of global supply — which amplifies the impact of any single large capital project or supply interruption.
What the PW Consulting report delivers (practical scope)
Our research is designed for strategy, procurement, and R&D leaders who need immediately actionable intelligence rather than an academic catalogue. Deliverables included in the full report are:
-
Bottom‑up demand forecasts by end market and polymer type, with scenario outputs for conservative, base, and upside demand trajectories across 2026–2032.
-
Supply‑side landscape and plant economics: unit cost curves, utilization scenarios, and feedstock sensitivity tables that translate spot butadiene and hydrogen price moves into margin impact on a per‑ton basis.
-
Risk and opportunity heat maps covering geopolitics, feedstock shocks, regulatory timelines (including PFAS influence), and competitive capacity additions — each with quantified probability bands and impact scoring.
-
Commercial playbooks: go‑to‑market options for specialty grades, value capture strategies through technical support and testing programs for OEM qualification, and pricing playbooks tied to inventory and hedging positions.
-
M&A and partnership screening: prioritized target archetypes and an acquisition valuation framework tailored for specialty elastomers, with sensitivity to integration costs and channel synergies.
-
Implementation templates: supplier scorecards, term‑sheet exemplars for long‑term feedstock contracts, and a staged investment timetable for new polymer lines or catalyst upgrades.
Market dynamics that should influence 2026 strategy
-
Feedstock volatility and regional spreads. During 2025–2026 the industry experienced pronounced regional differentials in butadiene pricing, with wide gaps between major trading hubs. These spreads materially change the attractiveness of local vs. import supply and should guide decisions on where to site incremental capacity or how to structure cross‑border sourcing agreements.
-
Price cycles and inventory effects. The HNBR market has recently seen sharp price movements driven by demand surges and inventory adjustments; short‑term spikes can create both margin windfalls and demand destruction if OEM pass‑through is constrained. Tactical inventory management and dynamic pricing tools will be essential for firms looking to stabilize returns.
-
Geopolitical risk to feedstock supply. Instability in key feedstock producing regions has periodically increased naphtha and LPG costs, feeding through into NBR and HNBR production expenses. Scenario planning that includes extended feedstock disruption is a prudent 2026 planning assumption.
-
Regulatory displacement opportunities. Recent filings and regulatory moves have explicitly referenced HNBR as a non‑fluorinated substitute for several sealing duties. This creates a multi‑year OEM qualification runway; companies that invest in targeted application validation now are likely to be in a preferred position as procurement teams seek PFAS‑free alternatives.
Competitive landscape — how industry players are positioning
The global competitive set includes multinational specialty chemical companies, regional integrated producers, and agile compounders and distributors. At a high level:
-
Global leaders are leveraging scale, a broad product portfolio, and global channel presence to lock in long‑term OEM relationships. Their strategic moves include capacity expansions in selective geographies and investment in lower‑emission processes that reduce both carbon footprint and local operating risk.
-
Specialty players focus on high‑value grades — extreme temperature, aerospace, and high‑durability sealing applications — where technical partnerships and certification pathways command premium pricing.
-
Regional producers, particularly in Asia, compete on cost and fast time‑to‑market for standard grades; many are pursuing incremental capacity to capture export opportunities as global demand grows.
-
Compounders and distributors provide downstream customization and local service, essential for customers who require rapid prototyping, tool changeover, or small‑batch production; they are often acquisition targets for larger players seeking channel control.
Recent corporate moves underscore these dynamics: several incumbents have confirmed capacity expansions and product introductions targeted at both OEM and industrial segments, while price adjustments and product launches among regional players have increased competitive intensity. The market displays moderate concentration — the top three players account for the majority of supply — which means that a few strategic moves can change the landscape quickly.
Actionable recommendations for 2026
-
Run a feedstock‑sensitivity stress test for any capital project. Model scenarios that include significant regional price differentials and a prolonged supply shock; use these outputs to set break‑even utilization and offtake thresholds.
-
Lock in technical partnerships with OEMs early. If your product roadmap targets regulatory‑driven substitution, start qualification programs now — the approval and validation cycles for sealing applications are multi‑year and resource intensive.
-
Pursue hybrid sourcing. Combine long‑term feedstock contracts with short‑term market exposure to protect margins while retaining upside, and consider regional inventory hubs to arbitrage price spreads.
-
Consider targeted M&A or JV for market entry. For companies looking to accelerate access to HNBR capabilities or to capture downstream margins, acquiring a regional compounder or forming a JV with a technical supplier can shorten time‑to‑market.
-
Invest in low‑emission processing and catalyst technology. Regulatory and customer pressure on sustainability profiles makes emissions‑efficient processes a differentiator; early adoption also mitigates operational risk as emissions standards tighten.
What we intentionally withhold in this preview — and why you should download the full report
In keeping with our “trailer” approach, this article highlights strategic insights and high‑level market metrics to support 2026 decision making. However, detailed segmentation tables, region‑ and application‑level share data, granular price and tariff decks, supplier scorecards, and the complete list of scenario outputs are excluded here to preserve the proprietary analytic layer of the study. These are the assets that enable precise commercial modelling and competitive benchmarking and are available in the full PW Consulting HNBR market report.
Final synthesis — the executive takeaway
HNBR is transitioning from a specialized, niche polymer into a strategically important performance elastomer for a broader set of sealing and resistance applications. The market’s mid‑single‑digit to high‑single‑digit CAGR and the ongoing repositioning of global capacity create a window of strategic opportunity in 2026: companies that move decisively — by securing feedstock, accelerating OEM qualification, and aligning capacity with validated demand — will capture disproportionate value. Conversely, organizations that delay investment or under‑model feedstock volatility face margin compression and competitive displacement.
PW Consulting’s full HNBR report provides the operative analytics and implementation tools executives need to convert this market trajectory into measurable commercial advantage. For access to the complete data sets, detailed segmentation, supplier scorecards, and tailored scenario models, consult the full report on our site or contact your PW Consulting advisor.
For detailed analysis of this topic, please visit the official page: Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Road Bikes Market to Reach USD 5.49 Billion by 2032 at 4.85% CAGR — PW Consulting
By pmarketresearch, 2026-07-08
Road Bikes Market 2026: Strategic Preview for Executive Decision‑Makers
As PW Consulting’s senior strategy team, we prepared this market preview to orient executive decisions in 2026. The global road bikes market is returning to a steady, structurally supported growth path: a market that expanded from roughly USD 3.1 billion in 2020 to about USD 3.85 billion in 2025 and is projected to continue rising into the next decade, reaching roughly USD 5.5 billion by 2032 under a mid‑range scenario. Our forecast framework expects a compound annual growth rate of approximately 4.85% through the 2026–2032 period. These headline numbers anchor the tactical and strategic guidance below — but the value for executives is less in the topline and more in the scenarios, risk ladders, and levers that convert that growth into profitable market share.
Road Bikes Market
Why this research matters for 2026 decisions
- Risk‑informed capital allocation: quantify how regulatory actions and raw‑material volatility change the returns on new product investments, plant expansions, and inventory commitments.
- Portfolio prioritization: identify where to concentrate R&D and channel investments between performance, endurance, and volume segments so 2026 product cycles align with demand momentum.
- Supply‑chain resilience: model procurement strategies (hedging, near‑sourcing, supplier consolidation) that protect margins against material price shocks and tariff exposures.
- M&A and partnerships: highlight acquisition targets and co‑development partners whose capabilities accelerate time‑to‑market on high‑value innovations without absorbing fixed cost risk.
- Pricing and channel optimization: translate the macro trend into price elasticity maps and dealer vs direct‑to‑consumer (D2C) scenarios that preserve ASPs while expanding reach.
What the full report delivers (practical, operational content)
- Validated market sizing and forward curves (2020–2032) with transparent assumptions and sensitivity bounds that management teams can plug into their financial models.
- Scenario playbooks that quantify the P&L and balance‑sheet impact of four plausible 2026 shocks — tariff imposition, a sustained raw material price surge, an acceleration in e‑bike substitution, and tightening UCI equipment rules.
- Supply‑chain stress tests: supplier concentration heatmaps, critical‑path lead‑time simulations, and recommended mitigation steps (dual sourcing, pre‑purchases, and regional buffering).
- Competitive diagnostic for the top global brands with capability maps, relative cost positions, and go‑to‑market strengths and weaknesses tailored to premium, mid, and entry tiers.
- Product roadmaps and R&D priorities tied to measured performance returns (e.g., system vs frame gains), regulatory compliance checklists, and testing protocols for 2026 rule changes.
- Commercial playbooks: channel split optimization, promotional cadence recommendations, and customer retention strategies for urban commuters, recreational riders, and competitive racers.
- M&A & partnership scoring model: a repeatable framework to rank targets by strategic fit, integration complexity, and near‑term cash conversion potential.
Macro dynamics shaping 2026 strategy
The industry is navigating a convergence of regulatory, cost, and product‑design forces that materially affect 2026 decisions:
Road Bikes Market
- Trade and tariff risk: stakeholders should plan for policy volatility. In late 2025 the US Department of Commerce opened comments on proposals that would dramatically raise tariffs tied to metal content. Even without a definitive outcome, the mere prospect compresses margins for manufacturers with exposed metal‑intensive supply chains and raises the value of local assembly or non‑metal innovation strategies.
- Regulatory design rules: UCI’s 2026 fork internal width limits require rapid design adaptations for race‑oriented platforms. This has cascading implications for wheel‑tire systems, integration strategies, and sponsor value propositions for pro team partnerships.
- Input cost pressure: steel, aluminum, and carbon fiber experienced multi‑year price escalations through 2025. Companies that rely on single‑source, high‑volume buys or that operate on thin margin models are particularly vulnerable.
- Channel and product blurring: discussions around e‑motor regulation and the misclassification risks of high‑powered e‑motorcycles could reshape how distributors, insurers, and regulators treat powered two‑wheelers, indirectly influencing dealer footprint economics and consumer purchasing behavior.
Competitive landscape — position, momentum, and tactical levers
Concentration in the road bikes market is meaningful but not prohibitive: the top three vendors control a large minority of global revenue, and the top five approach a clear majority, creating both competitive pressure and opportunity for informed challengers. Competitors fall into three strategic archetypes: technology leaders, system integrators with scale, and niche specialists. Understanding where a company sits on that map determines which levers will most improve relative performance.
Road Bikes Market
- Specialized (Morgan Hill, CA) — Technology and brand cachet in both aluminum and carbon. Their broad portfolio from entry to pro race gives them channel reach; maintain advantage through incremental material and cockpit integration innovations.
- Trek (Waterloo, WI) — Strength in aerodynamic and endurance platforms. Trek’s investment strategy should prioritize system‑level aero gains and service bundles to protect premium pricing.
- Cannondale (Bethel, CT) — Known for ride feel and aluminum performance models. Opportunities exist in modular upgrades and premiumizing aluminium lines without eroding core value propositions.
- Giant (Taichung, Taiwan) — Scale and recent product updates (notably an 18‑watt efficiency gain on the Propel through cockpit, wheel, and tire refinements) make Giant a bellwether for system engineering returns versus marginal cost.
- Cervélo, Pinarello, Factor, BMC, Canyon, Scott, Bianchi — These brands represent a mix of aero specialists, direct‑to‑consumer disruptors, and heritage craft makers. Tactical differentiation ranges from carbon material science to distribution models and racing partnerships.
Recent developments underscore strategic vectors for 2026: Giant’s March 2026 Propel update demonstrates the commercial value of system optimization; Canyon’s D2C refreshes tighten price/performance competition; Bianchi’s supply deal with a WorldTour team reinforces the marketing and R&D payoff from pro association; and smaller innovators (e.g., OPEN) indicate fertile ground in gravel and adjacent segments.
Strategic playbook for management teams in 2026
- Move from commodity sourcing to supplier partnership models: secure fixed‑volume options for carbon and critical metal inputs, and pursue joint development agreements to share R&D costs for new layup and integration concepts.
- Invest in system engineering over isolated component gains: measured system‑level watt reductions (cockpit, wheels, tires) can deliver outsized competitive advantages at lower certification and tooling cost than full new‑frame programs.
- Hedge regulatory exposure with product tiering: maintain race‑compliant platforms for pro channels while offering adaptable endurance and urban models that reduce dependence on contested tariff lines or specific material mixes.
- Pursue selective vertical integration and near‑shoring where economics justify — particularly assembly and final finishing — to mitigate tariff risk and improve lead‑time responsiveness to product launches.
- Accelerate margin capture via service and software: performance analytics, personalized fit services, and subscription wheels/maintenance can reduce cyclicality and improve customer lifetime value.
- Use targeted sponsorship and pro team alignment to validate new designs and accelerate market acceptance, but price those investments by measured return metrics tied to sales lift, not solely to brand prestige.
- Calibrate M&A to acquire capability not just volume: look for composite‑layup expertise, proprietary cockpit/wheel systems, or D2C logistics assets that shorten time‑to‑scale for high‑margin offerings.
How PW Consulting’s Road Bikes Market report accelerates action
This study is designed as an executable toolkit for 2026. Beyond the headline forecast and market map, the full report contains executable decision support: configurable financial models, supplier risk matrices, a prioritized R&D investment matrix, and an M&A scorecard populated with targets and valuation ranges. We intentionally keep detailed region‑ and application‑level splits behind the report paywall in order to preserve the actionable competitive granularity clients rely on for bidding, sourcing, and investment decisions.
For leadership teams, the most immediate takeaway is that steady topline growth masks a materially different competitive and regulatory terrain in 2026 than in 2020–2021. Companies that rewire procurement, sharpen system engineering, and align commercial models to service and software will capture disproportionate value as the market evolves. PW Consulting’s full report provides the granular segment tables, supplier lists, and company‑level diagnostics necessary to convert this strategic preview into an operational transformation plan.
Reach out to PW Consulting to obtain the full Road Bikes Market report and the accompanying decision‑support workbook to map the implications to your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Road Bikes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Iodine Market to Reach USD 2,355.6M by 2032 at 4.26% CAGR
By pmarketresearch, 2026-07-08
Iodine Market 2026: Strategic Imperatives for Decision‑Makers
As PW Consulting’s lead industry analyst, I present a focused strategic brief introducing our full Iodine Market study. This piece outlines why 2026 is a critical inflection year for participants across the value chain — producers, chemical processors, pharmaceutical manufacturers, investors and policy teams — and how the report equips you to make higher‑confidence decisions. We demonstrate the macro trajectory of the market and sketch the high‑impact levers that will determine winners, while deliberately preserving proprietary segment-level detail to encourage direct review of the full study.
Iodine Market
Why 2026 Matters: Timing, Risk and Opportunity
The iodine market has shown steady expansion through the first half of the decade, moving from a post‑2020 recovery into a structurally growing market. Our base year is 2025, when the global market reached USD 1.75 billion. Looking forward across our 2026–2032 forecast window, the market compounds at an annual growth rate of approximately 4.26%. By the end of our forecast horizon, the market is set to exceed USD 2.3 billion, reflecting both stable underlying demand and pockets of accelerated uptake driven by healthcare, industrial chemistry and recycling innovations.
Iodine Market
2026 is a hinge year because several disruptive vectors converge: regulatory shifts in medical manufacturing, nascent vertical integration attempts to secure contrast media supply chains, and selective capacity expansions from legacy producers. These forces will determine short‑term pricing dynamics and medium‑term structural positions. Companies that prepare now — modeling scenarios and stress‑testing supply paths — will convert uncertainty into advantage.
Iodine Market
What Strategic Leaders Need to Know
- Supply concentration and market power: The market exhibits meaningful concentration at the top. While there remains room for mid‑tier entrants, incumbents with integrated feedstock control and downstream capabilities maintain a privileged margin profile.
- Feedstock diversity matters: Producers sourcing iodine from caliche, brine, seaweeds and recycling show divergent cost curves and resilience to localized disruptions. The economics of each source type, and how they map to end‑use quality requirements, are central to sourcing strategy.
- Healthcare demand is the growth engine: Use cases tied to diagnostic imaging and pharmaceutical intermediates continue to underpin robust demand and higher purity thresholds, increasing the value of regulatory‑compliant, traceable supply chains.
- Regulatory and supply‑chain fragility: High‑impact regulatory interactions — including FDA scrutiny related to drug shortages and submission pathways for contrast media — can rapidly reallocate value along the chain. Firms must embed regulatory scenario analysis into commercial forecasting.
How the Market Is Evolving: Macro Signals
Across 2020–2025 the market expanded from a post‑pandemic base to a stronger, more diversified demand profile. The compound annual growth observed in our baseline validates continued investment interest, but beneath this headline growth lie asymmetries: pockets of rapid demand for premium, pharmaceutical‑grade iodine; cyclical industrial demand; and a growing strategic premium on supply reliability.
Capacity expansion announcements from established miners and processors have created a near‑term window of increased supply, while simultaneous moves by specialty chemical firms and emerging vertically integrated players indicate shifting capture of downstream margins. The net effect is a market that remains attractive, but one where first‑mover advantages accrue to those who align capacity, quality control and regulatory readiness.
Competitive Landscape: Players to Watch
Our analysis profiles global producers and specialty suppliers, emphasizing their strategic positioning rather than transactional figures. Key archetypes include:
- Large, upstream integrated miners with caliche and brine operations that supply both industrial and pharmaceutical channels. These players compete on feedstock scale, cost optimization, and certifications that signal environmental and energy management maturity.
- Regionally focused brine and oilfield‑linked producers that leverage localized extraction and specialized processing technologies to deliver high‑purity crystalline iodine for medical and research customers.
- Specialty chemical and materials firms that convert raw iodine into pharmaceutical intermediates, high‑purity compounds and polarizing film inputs — units where quality control and customer qualification are barriers to entry.
- Emerging vertically integrated entrants pursuing mine‑to‑product strategies aimed at decoupling critical medical supply chains from geopolitical and trade headwinds.
Representative firms covered in the full study include leading South American miners, Japanese and UK technology‑focused operators, and North American specialty processors. For each, our profiles synthesize production model, downstream exposure, recent capacity changes, and strategic intent — enabling readers to map competitor moves into realistic scenarios for pricing, availability and partnering opportunities.
Recent Developments and Their Strategic Implications
- Capacity expansions by major producers: Announced increases at established mining operations and brine processors suggest a deliberate effort to shore up supply to growing pharmaceutical and industrial channels. This expands optionality for buyers but can pressure near‑term pricing if demand does not absorb new volumes quickly.
- Specialty producer scaling: Technology‑driven producers have announced capacity uplifts to capture rising industrial and specialty chemical demand. Their moves signal that quality and process control remain critical value differentiators.
- Vertical integration in medical supply: New entrants pursuing mine‑to‑bottle strategies for contrast media are advancing regulatory and feasibility workstreams. These initiatives could reframe procurement strategies for hospitals and imaging suppliers by offering alternative qualified sources.
- Regulatory cadence: FDA interactions — including pathway submissions for contrast products and attention to drug shortage risks — will influence timelines for commercial supply diversification. Companies must synchronize regulatory milestones with commercial rollouts.
- Standards and certifications: Adoption of management system standards (energy, environmental, quality) by key producers improves their cost predictability and social license, which can be material for long‑term contracts with multinational buyers.
Report Deliverables: What You’ll Get from the Full Study
Our Iodine Market study is designed as a pragmatic decision tool for 2026 planning cycles. It includes:
- Top‑down market sizing and demand forecasts for 2026–2032, with scenario branches for healthcare expansion and industrial cyclicality.
- Supply‑side modelling that integrates feedstock economics, announced capacity changes, and substitutability dynamics.
- Regulatory risk matrices and a timeline of expected agency actions that could affect market access for new contrast media and pharmaceutical intermediates.
- Supplier heatmaps and procurement playbooks that guide sourcing strategy — from spot purchases to multi‑year offtake agreements and co‑investment structures.
- Investment and M&A screening templates: criteria, valuation multiples and integration risk flags tailored to producers, specialty converters and downstream manufacturers.
- Actionable recommendations and a 100‑day sprint plan for market entrants or incumbent responses.
Importantly, the full report contains detailed regional and application segmentation, company‑level share estimates, and price and volume intelligence that executives rely upon for contract negotiations and capital planning. This granular intelligence is intentionally reserved for the full report to ensure our clients retain exclusive strategic advantage.
Strategic Playbook for 2026
Based on our analysis, management teams should prioritize three coordinated initiatives in 2026:
- Secure quality‑compliant supply chains: For any business exposed to diagnostic imaging or pharmaceutical intermediates, dual‑sourcing and qualification of alternative suppliers are non‑optional. Build supplier scorecards that weight regulatory track record and certification parity with price.
- Assess vertical moves selectively: Vertical integration can mitigate supply shocks but requires deep regulatory and production capability. Pursue partnerships or minority investments before full upstream build‑outs, unless your firm already has extraction expertise.
- Embed regulatory scenario planning: Simulate FDA submission outcomes, potential trade policy shifts, and drug shortage escalations into financial forecasts. This will enable adaptive commercial tactics — from inventory buffers to price escalation clauses — that protect margins under stress.
How to Use This Intelligence in Board and Investment Decisions
Our market-level numbers and concentration metrics provide an evidence base for board debates about capex, M&A, and contract strategy. Use the study to:
- Formulate realistic up‑ and down‑side business cases for greenfield extraction or processing projects.
- Prioritize acquisition targets that close strategic gaps in feedstock diversity or downstream capabilities.
- Design procurement terms that recognize the asymmetric value of certified, traceable pharmaceutical‑grade supply.
Closing: Why the Report Is Timely
The 2026 planning horizon is no longer about incremental optimization; it is about structural positioning. With measured CAGR growth and ongoing concentration at the top of the market, the supply‑demand equation will reward actors who combine supply security, regulatory competency, and operational excellence. Our full Iodine Market study translates macro momentum into executable strategies — but we keep the most sensitive segment and company‑level data behind the detailed report to preserve actionable advantage for subscribers.
To access the comprehensive regional and application breakdowns, supplier scorecards, and downloadable modeling tools referenced here, please visit the PW Consulting report page for the full Iodine Market study.
For detailed analysis of this topic, please visit the official page: Iodine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com