

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Disposable Tableware Market Poised for 4.02% CAGR Through 2032

Disposable Tableware Market — 2026 Strategic Brief: Navigating the Transition from Compliance to Competitive Advantage
PW Consulting presents an executive-introductory perspective on our full Disposable Tableware Market study (base year 2025, forecast 2026–2032). This brief explains why the study matters for board-level and commercial decisions in 2026, how the market’s structural dynamics will shape value creation, and what practical moves manufacturers, brand owners, distributors, and private equity investors should prioritize. We demonstrate analytical depth and decision-useful insight while intentionally withholding the granular splits and proprietary model outputs that are available in the full report.
Disposable Tableware Market
Market at a glance: baseline and trajectory
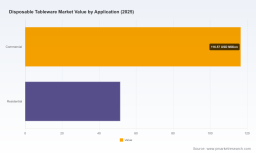
The disposable tableware market has moved from recovery to measured expansion. On a global basis, the market reached USD 168.0 Million (revenue unit: Million USD) in our 2025 base year after an accelerated rebound from the 2020 trough. Looking forward, our forecast embeds a 4.02% compound annual growth rate (CAGR) for 2026–2032, with the market approaching roughly USD 221 Million by 2032 under the central scenario. These headline numbers mask important transitions — in materials, policy-driven demand shocks, and channel shifts — that will determine who captures the next wave of margin expansion.
Disposable Tableware Market
Why this research matters for 2026 decision-making
- Regulatory-driven demand shifts are now strategic : Recent policy decisions (for example, state and national bans and prohibitions that came into force during 2024–2025) have materially reallocated demand away from certain legacy materials toward molded-fiber, paper-based and recyclable/compostable alternatives. Companies that treat regulation as a recurring operational risk rather than a one-off compliance cost will unlock first-mover advantages.
- Sustainability credentials are table stakes — but with commercialization nuance : Innovations and approvals that expand allowable recycled content change both raw-material economics and go-to-market claims. The acceptance of high Post-Consumer Recycled (PCR) content for food-contact items creates a pathway to lower-cost circular feedstocks — but it requires validated supply chains and regulatory documentation to convert procurement contracts.
- Fragmentation creates roll-up and margin-improvement opportunities : Market concentration metrics indicate a fragmented competitive field (CR3 ≈ 22%; CR5 ≈ 28.5%), leaving room for scale-driven cost reduction, brand consolidation in key channels, and targeted M&A to secure fiber and compostable capacity.
- Commercial models must be retooled : Pricing strategies, channel incentives, and contract terms that worked in a legacy EPS/plastic environment will underperform in a multi-material market where cost drivers, shelf-life claims, and end-of-life handling differ materially.
Regulatory and innovation dynamics changing the playing field
- Policy interventions that took effect in 2024–2025 have redirected procurement and product roadmaps. Notably, statewide EPS restrictions and single-use plastics prohibitions have accelerated adoption of alternatives and prompted foodservice buyers to change supplier qualification criteria.
- Material innovation continues at pace — from novel paper plate inventions to scalable molded-fiber processes — creating opportunities to substitute higher-emission plastics without eroding consumer utility.
- Regulatory acceptance pathways for recycled content and compostable claims are enabling circular-leaning product strategies, but they require proactive engagement with regulators and certified supply chains to translate into commercial wins.
What the full report delivers — practical, transaction-ready intelligence
We structured the full study around use-cases for decision-makers who must translate insight into action in 2026. Key deliverables include:
Disposable Tableware Market
- Comprehensive market sizing and five-plus scenario forecasts (base year 2025; forecast 2026–2032), with sensitivity to raw-material price swings, regulatory adoption timing, and alternative development curves.
- Segmentation by material, application, and detailed regional breakdowns — including proprietary demand models and addressable-market maps for prioritized country clusters (note: granular splits are available only in the full report).
- Supply-chain and cost-to-serve analytics: raw-material sourcing footprints, converter capacity maps, capex timelines for molded-fiber vs. thermoforming, and margin waterfall models for alternate product constructs.
- Competitive benchmarking and strategic profiles covering major participants and challenger specialists, with M&A scorecards, partner-fit matrices, and integration risk assessments.
- Go-to-market playbooks tailored to manufacturers, brand owners and distributors: channel segmentation, tender templates, price-indexing strategies, and pilot deployment checklists for new-material introductions.
- Regulatory and sustainability action matrix: roadmaps for compliance, certification pathways, labeling strategies, and stakeholder engagement plans (regulators, waste managers, large foodservice buyers).
- Interactive financial model (licenseable) that allows executives to test acquisition scenarios, capex spends, and price shocks against revenue and EBITDA outcomes through 2032.
Competitive landscape: who to watch, and why
The market displays a mix of global converters, brand-house incumbents, and mission-led challengers. Each archetype brings different threats and partnership opportunities for incumbents and new entrants:
- Pactiv Evergreen Inc. — A large-scale converter with integrated paper and plastic offerings for both foodservice and consumer channels. Their breadth makes them a critical counterparty for national retailers and large foodservice distributors; they also have the operational scale to internalize feedstock transitions.
- Huhtamaki Oyj — Known for branded paper and molded-fiber products (including institutional-grade lines), this incumbent has deep R&D in molded fiber and strong go-to-market relationships with foodservice operators seeking branded reliability.
- Dart Container Corporation — A traditional foam and plastic player that is actively shifting portfolio exposure toward compostable lines. Their transition pathway is instructive for other plastic-heavy specialists attempting to reposition without margin erosion.
- Genpak LLC — A high-volume supplier to foodservice operators with capabilities in expanded polystyrene and paper-based formats; their playbook captures the trade-offs between low-cost formats and migration risk under tightening regulations.
- Reynolds Consumer Products Inc. — As a consumer-products house, Reynolds leverages marketing and retail shelf presence to influence household adoption patterns and private-label contracts.
- Novolex, Berry Global — Large-scale manufacturers with diversified portfolios across molded fiber and plastic; their investments in capacity and recycling partnerships are indicators of where scale economics will accrue.
- Green Paper Products, Eco-Products, World Centric — Niche, sustainability‑first specialists driving adoption in institutional and premium channels; their certification expertise and circular supply relationships are often acquisition targets for larger converters seeking credibility.
- Sabert Corporation — Focused on commercial and institutional foodservice, Sabert blends plastic and paper solutions and is an important strategic supplier for high-turnover foodservice concepts.
Taken together, the field shows room for consolidation and for differentiated specialist positions (e.g., cost leader in recycled fiber; premium sustainable brand; integrated circular player). The relatively low CR3/CR5 metrics point to an environment where intelligent aggregation or targeted capability acquisition can produce outsized returns.
Priority actions for executives in 2026
- Regulatory triage (0–3 months) : Run a compliance-impact and procurement requalification audit to identify at-risk SKUs and prioritized customers. Map current contracts to near-term policy deadlines and issue supplier continuity plans.
- Product and supplier pivot (3–9 months) : Execute SKU rationalization and run rapid pilots of molded-fiber and PCR-enabled SKUs with top buyers; negotiate supply agreements that include transitional pricing and shared risk clauses.
- Supply-chain de-risking (6–18 months) : Secure dual-sourced feedstocks, invest in backward integration for critical inputs where unit economics justify, and form strategic alliances with certified composting and sorting partners to protect claims.
- M&A and capacity strategy (12–36 months) : Screen for bolt-on targets that provide immediate access to fiber-processing, compostable-forming, or certification credibility. Prioritize targets that improve gross margin through vertical synergies rather than only market share.
- Commercial rewiring : Reprice contracts to reflect lifecycle costs and end-of-life handling, and segment customers by readiness to pay for certified sustainability vs. price sensitivity.
Methodology & assurance
The study uses a blended methodology: historical reconstruction (2020–2025) built from primary interviews and shipment data, and forward forecasts (2026–2032) combining bottom-up build-ups by product and channel with macro overlays for regulatory adoption and raw-material price paths. Scenario workstreams model accelerated substitution, moderate transition, and delayed adoption outcomes; all scenarios are accessible via the interactive model licensed with the report. Data quality is reinforced by supplier triangulation, buyer panel validation and a legal/regulatory review of jurisdiction-level policies through mid‑2026.
Next steps — where to get the full intelligence
This brief is designed to establish strategic context and immediate action priorities. The full PW Consulting Disposable Tableware Market report contains the granular regional, material and application splits, the interactive financial model, detailed company profiles and our proprietary M&A scorecards that are intentionally excluded here. For access to the complete dataset, licensing options, or a tailored workshop to apply the model to your portfolio, please contact our research team via the PW Consulting portal.
PW Consulting — We help clients convert regulatory disruption and material transition into durable competitive advantage.
For detailed analysis of this topic, please visit the official page: Disposable Tableware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com