

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Aspheric Lens Market to Hit USD 16,593M by 2032 at 8.4% CAGR - PW Consulting

Aspheric Lens Market 2026: Strategic Preview for Executive Decision-Making
Aspheric optics are at the center of a convergence between precision manufacturing, photonics-driven applications and high-volume consumer demands. This market preview, prepared by PW Consulting, synthesizes macro trends and practical levers that corporate leaders must know as they set strategy in 2026. Our full market study (base year 2025) combines quantitative forecasts, supply‑chain stress tests, and actionable playbooks for commercialization, but this introduction emphasizes the strategic implications while omitting the granular segmentation tables reserved for the full report.
Aspheric Lens Market
Why this study matters for 2026 decisions
-
Accelerating scale and structural growth: The global aspheric lens market expanded materially in the early 2020s and reached USD 9,487 Million in 2025. Under our central forecast, the market is expected to grow to approximately USD 16,593 Million by 2032, reflecting a compound annual growth rate (CAGR) of 8.4% across the 2026–2032 forecast horizon. That trajectory creates a multi-year window for revenue capture—but also intensifies competition for high‑precision capacity and qualified supply.
Aspheric Lens Market -
Decision timeframe alignment: For executives planning 12–36 month product roadmaps or 3–5 year capital investments, the interplay between near-term supply constraints and medium-term demand expansion is the critical planning parameter. Our research translates market-level growth into investment thresholds, break-even horizons, and capacity utilization scenarios tailored to different manufacturing approaches (glass molding, polymer injection, diamond turning, CNC grinding).
Aspheric Lens Market -
Risk-adjusted opportunity mapping: Growth alone is not a sufficient signal. We examine where premium value accrues (performance, manufacturability, integration) and where commoditization pressures compress margins. The result is a set of prioritized strategic moves—supply diversification, automation-led cost reduction, M&A targets, or vertical integration—calibrated to company-size and capability profiles.
What the full report delivers (practical content highlights)
-
Decision-ready market model: A living demand-supply model (interactive workbook) that converts the reported market growth into demand volumes by manufacturing method and product-performance tier. The model includes sensitivity levers (pricing, yield, lead time, labor cost) so executives can simulate scenarios quickly.
-
Manufacturing playbook: Comparative cost and throughput benchmarks for diamond turning, precision glass molding, and polymer injection; capex and OPEX schedules; recommended floor plans for mixed‑mode production; and a roadmap for automation investments that materially improve yield and reduce skilled labor dependency.
-
Procurement and supplier strategy: A supplier scoring matrix and audit checklist, tailored contract templates, and a phased supplier-onboarding timeline for rapid qualification under ISO 10110 documentation requirements.
-
Go-to-market and product roadmap guidance: Segment-specific release strategies, platformization templates to reduce SKU proliferation, and commercialization checklists for integrating aspheric optics into systems (camera modules, LiDAR, medical imaging).
-
Competitive and M&A playbook: Profiles for leading players, capability overlap maps, and valuation heuristics for tuck-in acquisitions targeting niche capabilities (ultra-precision metrology, hybrid aspherics, polymer molding). This includes scenario planning for both defensive and offensive M&A.
-
Risk register and mitigation matrices: Practical mitigations for raw-material bottlenecks, carbon-border regulatory exposure (e.g., CBAM implications), and talent scarcity in precision optics manufacturing.
Market structure and concentration — what executives must internalize
The market is neither fully consolidated nor atomized. The top three players account for a significant portion of industry revenue (CR3 ~47.1%), and the top five capture roughly 63.8%. That concentration creates clear implications: scale confers bargaining power with component suppliers and customers, but differentiated technical capabilities still allow focused specialists to command premium margins. For mid-sized incumbents and new entrants, the strategic question is whether to pursue specialization (high-value niche optical solutions) or invest to scale through automation and strategic partnerships.
Competitive landscape: capability map and strategic levers
-
Global optics leaders (e.g., multinational camera and precision optics firms) bring deep integration across lens design, coatings, and system-level optics. Their competitive advantage lies in R&D scale, IP portfolios, and customer lock-in in camera and semiconductor optics supply chains.
-
Mid-tier and specialized vendors (manufacturers of molded glass, diamond‑turned parts, and hybrid aspherics) differentiate on manufacturing innovation, lead-time, and customization. They are frequently preferred suppliers for medical imaging, LiDAR, and defense applications where performance-to-cost trade-offs are highly specific.
-
Electro-optics distribution and systems integrators add value through systems-level service (optical assembly, metrology, and testing), accelerating time‑to‑market for OEMs that lack in‑house optics expertise.
Representative strategic implications for each cluster:
-
Tier-1 multinational optics firms: prioritize system lock-in, expand into sensor/algorithms integration, and protect margin through IP and coatings specialization.
-
Mid-tier specialists: focus on manufacturing process IP (e.g., ultra-precision CNC, diamond turning) and pursue selective partnerships with OEMs in automotive and medical segments.
-
New entrants and scale-ups: consider asset-light service models (co-design + outsourced manufacturing) while building metrology and QA capabilities as a barrier to entry.
Operational dynamics and industry “noise” that influence timing
-
Production cost / labor: Complex grinding and polishing techniques continue to drive up per-unit labor cost and constrain throughput. Automation and in‑process metrology are not optional if organizations are targeting sustainable margins at scale.
-
Raw-material supply: The limited availability of certain high-grade optical glasses and specialty polymers remains a key gating factor. Executives should model procurement lead times and secure material options via long-term contracts or local sourcing where feasible.
-
Regulation and standards: ISO 10110 remains the lingua franca for documenting aspheric lens specifications; compliance reduces rework risk and accelerates qualification cycles for system integrators and OEMs.
-
Geopolitical and carbon regulation: Emerging trade and carbon-adjustment policies (for example, regional carbon border mechanisms) may inflate costs for certain imported inputs and require scenario stress‑testing in supply chain models.
Recent signal events and their implications
-
Technical publications and knowledge sharing: A January 2026 application note from a specialized optics firm emphasized polymer injection molding and integrated supply-chain approaches to reduce lead times—underscoring that process engineering advances are shifting where value is captured in the value chain.
-
Industry convenings and metrology focus: Events focused on manufacturing and metrology indicate industry attention on tolerancing, measurement repeatability and yield improvements. Leaders who invest early in metrology and closed‑loop manufacturing will shorten qualification cycles and secure premium customers.
Where to compete — strategic options for 2026
-
Operational excellence: Invest in automation and in‑line metrology to convert labor- and tolerance-driven disadvantages into predictable, scalable manufacturing. This path suits players targeting higher volume, lower variety segments.
-
Specialization and performance premium: Concentrate on hybrid aspherics, ultra-precision optics for LiDAR and medical imaging, and deepen certification capabilities for regulated markets. This route preserves margin in an otherwise competitive growth environment.
-
Partnership and platform strategies: Build modular optical sub-systems and co-development partnerships with sensor and semiconductor players to lock-in customers and expose new cross-selling channels.
-
Vertical integration: For firms exposed to material or process risk, integrating upstream (glass suppliers, coating houses) or downstream (assembly and testing) can stabilize margins but requires careful ROI discipline.
Immediate actions for executives (first 12 months)
-
Run a 90‑day supply‑chain stress test: model lead‑times for critical glass types and polymer resins under three disruption scenarios, and identify two alternative qualified suppliers for each critical input.
-
Prioritize metrology investments: pilot in‑line interferometry and automated surface inspection on one production line to benchmark yield improvements and cycle time reductions.
-
Customer portfolio review: segment customers by margin-to-effort and develop targeted commercialization playbooks for the two highest-margin segments where aspherics are mission‑critical.
-
Capability gap audit: map internal competencies vs. target profiles (precision molding, diamond turning, coating, assembly) and define a 12–24 month capability investment plan tied to explicit revenue triggers.
What we withhold here — and why you should access the full report
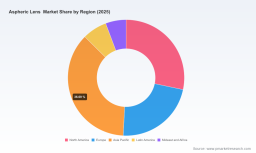
This preview intentionally omits the detailed regional and application-level splits, granular pricing curves, and the full company-by-company revenue benchmarking that underpin our recommendations. Those segmented datasets and interactive models are core deliverables in the full Aspheric Lens Market report and are necessary to translate the strategic options above into executable business plans and financial models. If you are planning capital allocation, M&A screening, or a product commercialization timeline in 2026, the actionable datasets in the complete study are indispensable.
Closing: the strategic imperative
The aspheric lens market offers sustained growth driven by higher‑value imaging systems, automotive sensing, and medical instrumentation. But growth will favor organizations that move beyond product-centered competition to control critical manufacturing capabilities, secure supply for high‑grade materials, and embed rigorous metrology and standards into their workflows. Our full report provides the detailed, transaction‑ready intelligence—forecasts, supplier matrices, and investment cases—required to translate this market expansion into defensible, profitable scale.
For access to the full dataset, segmentation tables, company valuations and decision-ready models, consult the PW Consulting Aspheric Lens Market report and its interactive appendices.
For detailed analysis of this topic, please visit the official page: Aspheric Lens Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com