

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Iodine Market to Reach USD 2,355.6M by 2032 at 4.26% CAGR

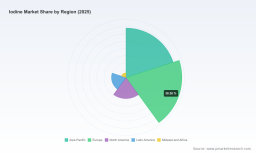
Iodine Market 2026: Strategic Imperatives for Decision‑Makers
As PW Consulting’s lead industry analyst, I present a focused strategic brief introducing our full Iodine Market study. This piece outlines why 2026 is a critical inflection year for participants across the value chain — producers, chemical processors, pharmaceutical manufacturers, investors and policy teams — and how the report equips you to make higher‑confidence decisions. We demonstrate the macro trajectory of the market and sketch the high‑impact levers that will determine winners, while deliberately preserving proprietary segment-level detail to encourage direct review of the full study.
Iodine Market
Why 2026 Matters: Timing, Risk and Opportunity
The iodine market has shown steady expansion through the first half of the decade, moving from a post‑2020 recovery into a structurally growing market. Our base year is 2025, when the global market reached USD 1.75 billion. Looking forward across our 2026–2032 forecast window, the market compounds at an annual growth rate of approximately 4.26%. By the end of our forecast horizon, the market is set to exceed USD 2.3 billion, reflecting both stable underlying demand and pockets of accelerated uptake driven by healthcare, industrial chemistry and recycling innovations.
Iodine Market
2026 is a hinge year because several disruptive vectors converge: regulatory shifts in medical manufacturing, nascent vertical integration attempts to secure contrast media supply chains, and selective capacity expansions from legacy producers. These forces will determine short‑term pricing dynamics and medium‑term structural positions. Companies that prepare now — modeling scenarios and stress‑testing supply paths — will convert uncertainty into advantage.
Iodine Market
What Strategic Leaders Need to Know
- Supply concentration and market power: The market exhibits meaningful concentration at the top. While there remains room for mid‑tier entrants, incumbents with integrated feedstock control and downstream capabilities maintain a privileged margin profile.
- Feedstock diversity matters: Producers sourcing iodine from caliche, brine, seaweeds and recycling show divergent cost curves and resilience to localized disruptions. The economics of each source type, and how they map to end‑use quality requirements, are central to sourcing strategy.
- Healthcare demand is the growth engine: Use cases tied to diagnostic imaging and pharmaceutical intermediates continue to underpin robust demand and higher purity thresholds, increasing the value of regulatory‑compliant, traceable supply chains.
- Regulatory and supply‑chain fragility: High‑impact regulatory interactions — including FDA scrutiny related to drug shortages and submission pathways for contrast media — can rapidly reallocate value along the chain. Firms must embed regulatory scenario analysis into commercial forecasting.
How the Market Is Evolving: Macro Signals
Across 2020–2025 the market expanded from a post‑pandemic base to a stronger, more diversified demand profile. The compound annual growth observed in our baseline validates continued investment interest, but beneath this headline growth lie asymmetries: pockets of rapid demand for premium, pharmaceutical‑grade iodine; cyclical industrial demand; and a growing strategic premium on supply reliability.
Capacity expansion announcements from established miners and processors have created a near‑term window of increased supply, while simultaneous moves by specialty chemical firms and emerging vertically integrated players indicate shifting capture of downstream margins. The net effect is a market that remains attractive, but one where first‑mover advantages accrue to those who align capacity, quality control and regulatory readiness.
Competitive Landscape: Players to Watch
Our analysis profiles global producers and specialty suppliers, emphasizing their strategic positioning rather than transactional figures. Key archetypes include:
- Large, upstream integrated miners with caliche and brine operations that supply both industrial and pharmaceutical channels. These players compete on feedstock scale, cost optimization, and certifications that signal environmental and energy management maturity.
- Regionally focused brine and oilfield‑linked producers that leverage localized extraction and specialized processing technologies to deliver high‑purity crystalline iodine for medical and research customers.
- Specialty chemical and materials firms that convert raw iodine into pharmaceutical intermediates, high‑purity compounds and polarizing film inputs — units where quality control and customer qualification are barriers to entry.
- Emerging vertically integrated entrants pursuing mine‑to‑product strategies aimed at decoupling critical medical supply chains from geopolitical and trade headwinds.
Representative firms covered in the full study include leading South American miners, Japanese and UK technology‑focused operators, and North American specialty processors. For each, our profiles synthesize production model, downstream exposure, recent capacity changes, and strategic intent — enabling readers to map competitor moves into realistic scenarios for pricing, availability and partnering opportunities.
Recent Developments and Their Strategic Implications
- Capacity expansions by major producers: Announced increases at established mining operations and brine processors suggest a deliberate effort to shore up supply to growing pharmaceutical and industrial channels. This expands optionality for buyers but can pressure near‑term pricing if demand does not absorb new volumes quickly.
- Specialty producer scaling: Technology‑driven producers have announced capacity uplifts to capture rising industrial and specialty chemical demand. Their moves signal that quality and process control remain critical value differentiators.
- Vertical integration in medical supply: New entrants pursuing mine‑to‑bottle strategies for contrast media are advancing regulatory and feasibility workstreams. These initiatives could reframe procurement strategies for hospitals and imaging suppliers by offering alternative qualified sources.
- Regulatory cadence: FDA interactions — including pathway submissions for contrast products and attention to drug shortage risks — will influence timelines for commercial supply diversification. Companies must synchronize regulatory milestones with commercial rollouts.
- Standards and certifications: Adoption of management system standards (energy, environmental, quality) by key producers improves their cost predictability and social license, which can be material for long‑term contracts with multinational buyers.
Report Deliverables: What You’ll Get from the Full Study
Our Iodine Market study is designed as a pragmatic decision tool for 2026 planning cycles. It includes:
- Top‑down market sizing and demand forecasts for 2026–2032, with scenario branches for healthcare expansion and industrial cyclicality.
- Supply‑side modelling that integrates feedstock economics, announced capacity changes, and substitutability dynamics.
- Regulatory risk matrices and a timeline of expected agency actions that could affect market access for new contrast media and pharmaceutical intermediates.
- Supplier heatmaps and procurement playbooks that guide sourcing strategy — from spot purchases to multi‑year offtake agreements and co‑investment structures.
- Investment and M&A screening templates: criteria, valuation multiples and integration risk flags tailored to producers, specialty converters and downstream manufacturers.
- Actionable recommendations and a 100‑day sprint plan for market entrants or incumbent responses.
Importantly, the full report contains detailed regional and application segmentation, company‑level share estimates, and price and volume intelligence that executives rely upon for contract negotiations and capital planning. This granular intelligence is intentionally reserved for the full report to ensure our clients retain exclusive strategic advantage.
Strategic Playbook for 2026
Based on our analysis, management teams should prioritize three coordinated initiatives in 2026:
- Secure quality‑compliant supply chains: For any business exposed to diagnostic imaging or pharmaceutical intermediates, dual‑sourcing and qualification of alternative suppliers are non‑optional. Build supplier scorecards that weight regulatory track record and certification parity with price.
- Assess vertical moves selectively: Vertical integration can mitigate supply shocks but requires deep regulatory and production capability. Pursue partnerships or minority investments before full upstream build‑outs, unless your firm already has extraction expertise.
- Embed regulatory scenario planning: Simulate FDA submission outcomes, potential trade policy shifts, and drug shortage escalations into financial forecasts. This will enable adaptive commercial tactics — from inventory buffers to price escalation clauses — that protect margins under stress.
How to Use This Intelligence in Board and Investment Decisions
Our market-level numbers and concentration metrics provide an evidence base for board debates about capex, M&A, and contract strategy. Use the study to:
- Formulate realistic up‑ and down‑side business cases for greenfield extraction or processing projects.
- Prioritize acquisition targets that close strategic gaps in feedstock diversity or downstream capabilities.
- Design procurement terms that recognize the asymmetric value of certified, traceable pharmaceutical‑grade supply.
Closing: Why the Report Is Timely
The 2026 planning horizon is no longer about incremental optimization; it is about structural positioning. With measured CAGR growth and ongoing concentration at the top of the market, the supply‑demand equation will reward actors who combine supply security, regulatory competency, and operational excellence. Our full Iodine Market study translates macro momentum into executable strategies — but we keep the most sensitive segment and company‑level data behind the detailed report to preserve actionable advantage for subscribers.
To access the comprehensive regional and application breakdowns, supplier scorecards, and downloadable modeling tools referenced here, please visit the PW Consulting report page for the full Iodine Market study.
For detailed analysis of this topic, please visit the official page: Iodine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com