

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Shock Absorber Market Set for 5% CAGR Through 2032

Shock Absorber Market: Strategic Outlook for 2026 Decision-Making
Executive summary
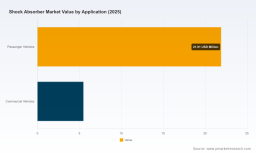
As PW Consulting’s lead industry analyst, I present a concise strategic preface to our comprehensive Shock Absorber Market study (base year 2025). The market has expanded steadily over the past half-decade, increasing from USD 21.47 Million in 2020 to USD 27.4 Million in 2025. Our forecast period (2026–2032) anticipates continued expansion at a compound annual growth rate (CAGR) of 5.0%, reaching roughly USD 38.55 Million by 2032 (all figures in USD Million). For 2026 corporate planning cycles, the implications are clear: steady topline growth accompanies selective disruption driven by electrification, adaptive systems, raw-material volatility, and tightening safety and emissions regulation.
Shock Absorber Market
Why this report matters for 2026 strategic planning
-
Timing: The 2026 planning horizon aligns with several regulatory and OEM product cycles that will determine supplier qualification and platform selection for the next generation of vehicles. Delays or misreads here can lock suppliers out of multi-year programs.
Shock Absorber Market -
Predictability vs. disruption: A predictable macro trajectory (5.0% CAGR) masks asymmetric risk. Material cost shocks, software-driven damping systems, and OEM-level system integration create windows for both margin compression and premiumization.
Shock Absorber Market -
Resource allocation: With a measured market growth rate, firms must choose between volume-led scale plays, targeted premiumization (adaptive/EV-specific dampers), or aftermarket expansion. Each choice demands different capex, R&D, and M&A profiles.
-
Competitive positioning: The market exhibits moderate consolidation—our concentration metrics indicate a fragmented landscape with the top three players accounting for approximately a quarter of value and the top five approximately one-third—creating opportunities for mid-tier players to pursue consolidation or niche specialization.
Key dynamics shaping supplier economics in 2026
-
Regulatory acceleration: Safety and emissions rules—both regionally specific and globally aligned—are increasingly influencing damper design. Regulatory moves such as new NHTSA guidelines and strengthened EPA GHG standards through model year 2026 create indirect support for advanced damping solutions that improve vehicle efficiency and active safety integration.
-
Technology shift: Adoption of adaptive, electronically controlled dampers (including AI-enabled tuning for EV platforms) is progressing from flagship models into high-volume segments. Suppliers who can deliver verified systems engineering and production-ready electronics/software stacks will secure higher margins.
-
Input-cost volatility: Steel and hydraulic fluid price inflation, exacerbated by sustained supply disruptions linked to geopolitical events, remain a near-term margin headwind. Cost pass-through mechanisms, hedging strategies, and material substitution will be key levers.
-
Trade and tariff dynamics: Preferential trade agreements and supply-chain realignments are enabling cross-border OEM-supplier collaboration; firms with flexible manufacturing footprints stand to benefit from reduced friction in trans-regional platform sourcing.
Strategic implications by corporate function
-
R&D and product roadmap: Prioritize modular platforms that support both passive and active damping architectures. Invest in validated control software and sensor integration to reduce system-level qualification timelines with OEMs.
-
Supply chain & procurement: Establish strategic hedges for key commodities and qualify alternate suppliers for hydraulic fluids and critical steel grades. Shorten lead-times for high-cost components via nearshoring where economically sensible.
-
Commercial & OEM engagement: Align product demonstrations around system-level benefits—fuel economy gains, NVH improvements, and safety compliance—rather than component specifications alone. Early engagement in OEM calibration cycles yields outsized program share.
-
M&A and corporate development: Given moderate market concentration, acquisitive growth can be achieved through targeted buys—capability gaps (electronics, software, EV-adapted dampers) offer the highest strategic uplift per dollar.
-
Aftermarket strategy: With passenger vehicle parc aging in several markets, differentiated aftermarket propositions (smart retrofits, digitally enhanced warranty & diagnostics) offer recurring revenue streams that cushion OEM cycle exposure.
What PW Consulting’s report delivers (practical content highlights)
-
Actionable demand model: A calibrated topline model from 2020–2032 (base year 2025) that allows scenario testing against commodity shocks, EV adoption curves, and regulatory trajectories.
-
Decision-ready playbooks: Function-specific recommendations for procurement, R&D prioritization, go-to-market tactics, and M&A screening filters tuned for 2026 execution.
-
Risk heatmaps: Short- and medium-term risk matrices covering input-price volatility, regulatory timing, and program de-risking steps for supplier qualification.
-
Commercial modeling templates: Margin and pricing impact simulators that show the sensitivity of profit pools to different product-mix and pass-through strategies.
-
Benchmarking and KPIs: Operational benchmarks for cycle-time to qualification, warranty rates, and manufacturing productivity that inform near-term operational improvements.
-
Executive-ready briefings: Summarized scenarios that map each strategic choice to likely market outcomes through 2032.
Competitive landscape—who matters and why
The competitive field contains global OEM suppliers and regional specialists. Leading names maintain broad OEM relationships and are accelerating capabilities in adaptive and EV-specific systems. Below is a high-level strategic read on the core players covered in the report:
-
KYB Corporation (Tokyo, Japan) — Global OEM scale in hydraulic shock absorbers and increasing investment in electronic suspension subsystems. Strength: deep OEM engineering relationships and global manufacturing footprint.
-
ZF Friedrichshafen AG (Friedrichshafen, Germany) — Focused on high-performance and adaptive dampers; positions itself as a systems integrator for OEM platforms, particularly where mechatronics and software play a role.
-
Tenneco / Monroe (Northville, Michigan, USA) — Strong aftermarket and light-vehicle OEM presence; recent product initiatives underscore a push to reclaim performance and comfort leadership.
-
thyssenkrupp Bilstein (Ennepetal, Germany) — Known for premium performance products with pronounced OEM and replacement market credibility; leverages technology cachet to sustain margin premium.
-
KONI B.V. (Oud-Beijerland, Netherlands) — Niche premium and motorsport-derived technology translated into road-car performance applications; a go-to for performance-calibrated dampers.
-
Showa Corporation & Hitachi Astemo (Japan) — Both investing in eco- and software-forward developments; Showa’s recent eco-hydraulic fluid announcement signals a sustainability push among component suppliers.
-
Mando Corporation (South Korea) — Emphasizing AI-enabled and EV-targeted adaptive systems; strong ties to domestic OEM programs provide a launchpad for global expansion.
-
Other relevant players — A mix of legacy brands and regional manufacturers continue to serve aftermarket and regional OEMs; their scale and proximity to localized supply chains make them meaningful in procurement and competitive scenarios.
Recent developments & near-term triggers
-
Product innovation: In March 2026, Monroe Ride Solutions announced advancements in passive damper valve technology that claim both improved ride comfort and handling—illustrative of the incremental innovation that will shape mainstream product cycles.
-
Sustainability push: Showa’s 2025 announcement of an eco-friendly hydraulic fluid highlights the dual pressures of regulatory compliance and customer demand for decarbonization across supply chains.
-
Regulatory and trade catalysts: New guidelines from NHTSA and tightened EPA GHG standards, coupled with trade agreements that reduce cross-border frictions, create both compliance obligations and new commercial pathways for suppliers able to scale regionally.
Risk profile and contingency considerations
-
Commodity shocks can rapidly compress margins in a market with moderate growth; proactive hedging and material-efficiency engineering are essential.
-
Software and electronic integration failure modes introduce program risk; suppliers must invest in systems engineering and supplier-of-record practices early in OEM timelines.
-
Geopolitical supply disruptions and sudden tariff shifts can upend sourcing strategies; flexible manufacturing footprint and alternative-sourcing plans are recommended.
Conclusion — how to act in 2026
For executive teams building 2026 plans, the choice is not between growth or protection—both are required. The market’s steady 5.0% CAGR through 2032 offers a predictable foundation, but the growth pathway will be uneven across technologies, channels, and geographies. Firms that combine disciplined supply-chain risk management, targeted investments in adaptive/EV-capable damping technologies, and commercially minded OEM engagement will convert a modest market expansion into outsized strategic returns.
PW Consulting’s full Shock Absorber Market report provides the detailed segment-level data, vendor benchmarking, and executable playbooks needed to convert these strategic imperatives into 2026 actions. For access to the complete segmentation, granular forecasts, and proprietary decision tools, please visit our report page or contact our strategy team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Shock Absorber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com