

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: EV Battery Market 2026–2032 — 3.82% CAGR Fuels Electric Mobility

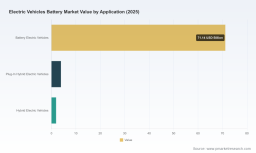
Electric Vehicles Battery Market: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As the automotive industry accelerates its transition to electrified mobility, the electric vehicle (EV) battery market is entering a phase defined by incremental growth, concentrated supply power, and disruptive technology inflection points. Our base-year analysis (2025) places the global EV battery market at approximately USD 77.0 billion, following a steady climb from the early 2020s. Under our central forecast, the market expands at a compound annual growth rate (CAGR) of roughly 3.8% through the 2026–2032 horizon, crossing the USD 100 billion threshold before the end of the forecast window. These headline figures mask meaningful differentiation beneath the surface — shifts in chemistry, manufacturing location strategy, feedstock volatility, and regulatory constraints that will determine winners and losers in 2026 and beyond.
Electric Vehicles Battery Market
Why 2026 is a pivotal year
-
Transition from volume-led to value-led competition: With headline market growth moderating versus the high-double-digit expansion of earlier years, 2026 will separate companies that compete on cost and scale from those capturing value through differentiated chemistries, fast-charge capability, safety, and integrated systems approaches.
Electric Vehicles Battery Market -
Regulatory and trade regimes are reshaping supply chains: Recent policy moves have created new sourcing and localization imperatives. Procurement teams and investors must evaluate compliance, tariff exposure, and the operational cost of localization when sizing facilities and negotiating offtake agreements.
Electric Vehicles Battery Market -
Material and technology inflection points converge: Surges in key commodity prices alongside rapid commercial rollouts of alternative chemistries force OEMs and suppliers to reassess technology roadmaps and risk exposures in 2026.
Market trajectory and what the headline numbers mean
Viewed as a whole, the EV battery market is continuing to expand but at a pace that rewards operational excellence, strategic positioning, and portfolio flexibility. The market’s progression from the low-60s billion USD level in the early 2020s to roughly USD 77 billion in 2025 — and onward toward a seven-figure growth milestone by the early 2030s — reflects a maturing industry where unit cost reductions, technology substitution, and aftermarket business models matter as much as unit volume.
For corporate strategists this implies three immediate tactical considerations: 1) prioritize investments that improve cost-per-kilowatt-hour on commercially relevant chemistries; 2) model scenarios where commodity spikes and export controls compress margins; and 3) set clear criteria for factory location and partnership choices that internalize regulatory and tariff risk.
Competitive landscape — concentrated and contested
The EV battery landscape in 2026 remains relatively concentrated among a handful of large, vertically integrated suppliers, with the top three players commanding a substantial share of market supply and the top five commanding a clear majority. This structure produces tight negotiation dynamics with OEMs, privileged access to large-scale capacity, and the ability for front-runners to subsidize R&D at scale.
Leading suppliers demonstrate complementary strategic approaches that define current best practices and emergent threats:
-
CATL (Ningde, China): Global market leadership driven by breadth of chemistry offerings — including LFP, NCM, and advanced formulations — coupled with rapid commercialization of sodium-ion and condensed cell formats targeted at range and fast-charge performance. CATL’s move into sodium-ion mass production and its latest Qilin and fast-charge products underscore a playbook that mixes scale, product differentiation, and aggressive commercialization timelines.
-
BYD (Shenzhen, China): Integrates proprietary cell and pack technologies with captive vehicle demand. Its Blade Battery narrative emphasizes safety and charging characteristics and provides a vertically coordinated advantage for both captive fleet deployment and third-party supply opportunities.
-
LG Energy Solution (Seoul, South Korea): Leverages large-scale cylindrical and pouch production with geographic diversification, notably expanded manufacturing in North America. LGES balances long-term OEM contracts with strategic capacity retooling to reflect shifting chemistry demand.
-
Panasonic Energy (Osaka, Japan): Continues to anchor cylindrical-cell leadership with multi-format programs for North American and global OEMs. Panasonic’s deep OEM partnerships and cell-format expertise make it a critical supplier in product architectures optimized around cylindrical formats.
-
SK On and Samsung SDI (Seoul, South Korea): Both firms combine chemistry R&D with regional expansion. Recent multi-year supply agreements from Samsung SDI highlight continued demand for high-performance cells for premium OEM programs.
-
EVE Energy and Northvolt: Represent targeted regional plays — one anchored in domestic prismatic technologies and the other emphasizing clean-energy production and European supply sovereignty — both attractive to OEMs pursuing differentiated sustainability and localization narratives.
Dynamics shaping 2026 decision-making
-
Regulatory tailwinds and headwinds: Policy changes in 2025–2026 have materially affected procurement strategies. For example, trade measures and sourcing conditions in major markets have altered the economics of imported cells and encouraged a reassessment of onshore capacity. Companies must model not just tariff rates but also the administrative and compliance costs associated with evolving incentive programs.
-
Material price volatility: The industry experienced marked swings in critical feedstocks. Cobalt supply constraints and policy actions in key producer nations led to sharp price movements, while lithium markets rebounded significantly in early 2026 compared to 2025 levels. These dynamics increase the value of supply agreements, downstream integration options, and alternative chemistry adoption.
-
Chemistry substitution and manufacturing reallocation: Large-scale retooling toward different chemistries — including reallocations toward LFP in 2025 — demonstrates that manufacturing footprints are now more plastic. Sodium-ion moving into mass production further expands the technology toolkit available to OEMs and fleets seeking cost-performance trade-offs.
-
Technology performance vectors: Range per charge, charge speed, safety characteristics, lifecycle degradation, and total cost of ownership remain the dominant decision criteria for OEMs and fleet operators. Recent product launches underscore a premium on fast-charge and condensed energy-density solutions.
Practical content included in our full report
The comprehensive PW Consulting market study is designed for executives who need to translate macro trends into executable 2026 plans. Key deliverables include:
-
Robust market sizing and scenario forecasts, with transparent methodology and sensitivity testing to alternative demand, commodity, and policy assumptions.
-
Supply-chain heatmaps and bottleneck risk scoring that identify critical nodes and contingency options.
-
Technology roadmaps and deployment timelines for incumbent and emergent chemistries, including commercialization timelines and cost curves.
-
Competitive intelligence dossiers for tier-1 suppliers — coverage includes commercial strategies, capacity expansion roadmaps, partnership matrices, and likely responses to OEM sourcing shifts.
-
Commercial playbooks for OEMs and investors: negotiation checklists, contract structures, offtake calibration tools, and go-to-market templates for captive vs. third-party supply strategies.
-
M&A and JV decision frameworks that prioritize value creation levers under different regulatory and commodity scenarios.
Recommended strategic actions for 2026
-
Lock flexible capacity and secure feedstock optionality: Structure offtake and supply agreements to preserve flexibility across chemistry formats and geographic sources; where possible, negotiate clauses that hedge against extreme commodity swings.
-
Prioritize modular investment in manufacturing: Favor modular, reconfigurable lines that enable chemistry switches without multi-year production gaps.
-
Build regulatory playbooks: Invest in capabilities to rapidly assess incentive eligibility, tariff exposure, and localization requirements; prioritize markets where policy alignment yields outsized total-cost advantages.
-
Differentiate through system-level integration: Suppliers and some OEMs will capture premium value by integrating thermal management, cell-to-pack designs, and differentiated warranties rather than competing solely on cell cost.
-
Stress-test partnerships and M&A with scenario-driven valuation: Use scenario P&L stress tests that incorporate raw material shocks and regulatory permutations — transact where synergies are resilient across these regimes.
Implications for corporate planners and investors
2026 will not be a year for passive portfolio allocations. The combination of moderate headline growth, concentrated supplier power, and disruptive material and chemistry shifts elevates the returns to active strategic management. Boards should expect procurement teams to present multi-scenario sourcing plans, CFOs to demand commodity-hedging strategies, and business development teams to prioritize partnerships that reduce execution risk.
For investors, the concentration metrics in the sector point to asymmetric opportunity: a small number of integrated suppliers will likely preserve margin and market access, while nimble challengers can win share regionally by aligning with local OEMs and sustainability narratives. The winners will be those who couple capital discipline with a clear play for pricing power, differentiation, or structural cost advantage.
Next steps — where to find the full intelligence
This article is a strategic preview intended to communicate the practical value of full, proprietary analysis contained in our Electric Vehicles Battery Market report. The complete study includes granular sensitivity models, a downloadable dataset, and a full competitive matrix that expands on the supplier dossiers summarized here. For procurement leaders, R&D heads, and C-suite decision-makers planning 2026 capital and commercial moves, the full report provides the actionable depth necessary to convert uncertainty into advantage.
Contact PW Consulting or visit our report page to access the full dataset and scenario-builders, and to schedule a bespoke briefing tailored to your portfolio and operational footprint.
For detailed analysis of this topic, please visit the official page: Electric Vehicles Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com