

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
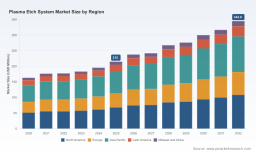
PW Consulting: Plasma Etch Market to Reach USD 344.8M by 2032 at 13.5% CAGR

Plasma Etch System Market — Strategic Intelligence Brief for 2026 Decision-Makers
As companies finalize capital plans, supplier strategies, and regulatory compliance roadmaps for 2026, the Plasma Etch System market is entering a phase where technology choice, supply‑chain resilience, and regulatory readiness will determine winners and losers. PW Consulting’s new market study — built on a 2020–2025 historical base and a 2026–2032 forecast horizon — provides the analytical scaffolding executives need to move from hypothesis to high‑confidence action.
Plasma Etch System Market
Why this research matters for 2026
-
Accelerating market growth with practical implications. The Plasma Etch System market has expanded steadily through 2020–2025 and, per our forecast framework, is set to accelerate during 2026–2032 at a compound annual growth rate of 13.5%. Translating that growth into procurement and R&D budgets requires granular scenario planning: buy vs. lease decisions on fab equipment, retrofit vs. greenfield capacity, and timing of technology upgrades for advanced nodes and heterogeneous integration.
Plasma Etch System Market -
Timing is strategic. With 2025 as the base year, the 2026 planning window is crucial for locking in pricing, lead times, and strategic partnerships. Short‑lead supplier engagements initiated in 2026 will influence production capacity and cost structures through the late 2020s.
Plasma Etch System Market -
Regulatory and input‑cost shocks require rapid adaptation. Volatility in critical specialty gases and tightening HFC/PFC regulations are already reshaping capital allocation and retrofit priorities. This report ties macro forecasts to actionable levers — what to accelerate, what to hedge, and what to defer.
Snapshot of market trajectory (select macro datapoints)
-
Historical growth: Our model captures the market evolution from 2020 through 2025, illustrating the recovery and structural expansion that preceded the 2026 decision window.
-
Near‑term sizing: Using 2025 as the base year, the market entry point for 2026 planning is explicitly modeled and validated against industry KPIs we track across equipment deployments, wafer starts, and CAPEX announcements.
-
Seven‑year outlook: Under the core scenario, the market expands at a 13.5% CAGR over 2026–2032, producing material addressable growth — a trajectory that justifies targeted investments in automation, emissions control retrofits, and specialty gas procurement strategies.
What’s inside PW Consulting’s operationally focused study
-
Market sizing and structured forecast (2020–2032) with scenario variants to stress‑test demand under different node‑transition and packaging adoption paths.
-
Technology landscape and roadmap: in‑depth treatment of ICP, RIE, DRIE and hybrid platforms with emphasis on manufacturability, throughput tradeoffs, and retrofit pathways for emissions reduction.
-
Supply‑chain vulnerability assessment: concentration and single‑source risks across high‑purity gases, chamber components, and custom RF subsystems, plus mitigation playbooks for procurement and contract design.
-
Regulatory impact modules: compliance cost modeling for AIM Act, EU F‑gas requirements and U.S. EPA emission factors, and practical retrofit sequencing to reduce emissions while maintaining uptime.
-
Commercial playbooks: vendor selection matrix, TCO templates, lease vs. buy calculators, and negotiation checklists tailored to OEMs, IDMs, and captive fabs.
-
M&A and partnership screen: candidate archetypes, valuation multipliers for software and service attachments, and integration risk matrices for roll‑up strategies.
-
Vendor profiles and benchmarking: comparative analysis of engineering capabilities, regional service footprints, and financial strength for the key equipment providers (feature summaries provided below).
-
Appendix: data sources, methodology, and a reproducible sensitivity model that allows client teams to substitute their own assumptions and produce bespoke forecasts.
Competitive landscape — what the analysis reveals
The supply base for plasma etch systems is globally distributed across specialist manufacturers and large semiconductor equipment groups. Market concentration metrics indicate a fragmented landscape (CR3 ~24.6%, CR5 ~26.2%), which has two strategic implications: procurement choice is broad, but scale matters for global service, spare parts, and rapid tool qualification.
-
Plasma Etch Inc. (Carson City, NV) — A niche supplier focused on surface‑preparation and RIE systems, including custom and refurbished models. Their flexibility and lower lead times make them a logical candidate for pilot‑line engagements and quick R&D iterations.
-
Plasma‑Therm LLC (Hauppauge, NY) — Known for premium wafer‑based etch and deposition equipment, with recent initiatives emphasizing scalable manufacturing for new application areas (notably quantum and advanced packaging). Their partnerships and content investments make them attractive for long‑term, co‑development relationships.
-
SPTS Technologies (KLA, Newport, UK) — A supplier of advanced platforms for silicon, dielectrics and compound semiconductor etch. SPTS is positioned for customers transitioning to heterogeneous substrates and who require tight process control at advanced nodes.
-
SAMCO Inc. (Kyoto, Japan) — Broad technology portfolio including high‑temperature PECVD and single‑wafer plasma systems. SAMCO’s recent product launches and trade show activity signal a push into higher‑temperature and specialty‑process segments, relevant for certain MEMS and compound‑semiconductor applications.
-
Trion Technology Inc. (Clearwater, FL) — Focused on etch, strip, and deposition solutions with particular strength in cost‑effective platforms for established logic and memory fabs.
-
Corial SA (Evry, France) — A European player emphasizing pilot‑line to production transfers. Their profile suits customers looking to localize production and de‑risk cross‑border supply chains.
-
GigaLane (Seoul, South Korea) — Regional supplier with growing capabilities for mainstream semiconductor fabs and expanding export footprints.
-
Tokyo Electron Limited; Applied Materials Inc.; Lam Research Corporation — Large OEMs that provide integrated fab solutions and have the service scale, financing options, and roadmap visibility required for advanced node and high‑volume memory customers. Their offerings are the default choice for major logic and memory IDMs, especially where system integration and long‑term support are non‑negotiable.
Recent industry developments that reshape 2026 strategy
-
SAMCO’s product moves (single‑wafer Aqua Plasma and 700°C high‑temperature PECVD) and their CS MANTECH presence underscore a pivot to high‑temperature and specialty processes. Firms planning pilot lines for MEMS, high‑power devices, or compound semiconductors should assess early access programs with SAMCO to compress time‑to‑qualification.
-
Plasma‑Therm’s 2025 review and partnership with quantum manufacturing players indicate that the market is beginning to monetize etch expertise beyond mainstream logic and memory — opening avenues for co‑investment in process development for emerging device classes.
-
Across the industry, tool suppliers are emphasizing service and retrofit packages (e.g., remote plasma chamber cleans) that materially reduce certain GHG emission factors and compliance costs. Procurement teams should treat these as differentiators, not optional add‑ons.
Regulatory and input‑cost dynamics every 2026 plan must address
-
Stringent HFC/PFC targets (e.g., AIM Act ambitions and EU F‑gas mandates) are forcing a shift toward lower‑GWP chemistries, emissions capture, and remote plasma clean strategies. These regulations will affect both equipment specifications and operating expenditures over the next decade.
-
U.S. EPA advancements — including demonstrated reductions in CF4 emission factors via remote cleans — create a clear retrofit pathway that can be modeled against non‑compliance penalties and carbon‑pricing scenarios.
-
Specialty gas supply volatility is a near‑term operational risk. For example, helium pricing has risen sharply in recent years, and limited domestic production of high‑purity gases in certain regions increases supplier risk. Companies must blend contractual hedging, dual‑sourcing, and local inventory strategies into their procurement plans.
Practical recommendations for 2026 planning
-
Embed emissions‑reduction upgrades into tool refresh cycles. Prioritize retrofits that reduce regulated emissions and secure compliance economics in CAPEX proposals.
-
Structure supplier engagements around service levels and spare‑parts SLA, not just purchase price. Given the fragmented CR metrics, the total cost of ownership and service coverage will differentiate suppliers.
-
Establish gas‑security protocols: evaluate dual‑sourcing, on‑site recovery, and contractual indexation to manage specialty‑gas exposure.
-
Create a two‑track R&D partnership approach: fast pilots with flexible, nimble suppliers for short‑cycle innovation; strategic co‑development with large OEMs for high‑volume, long‑lifecycle nodes.
-
Use scenario modeling to stress test capacity decisions against at least three demand paths (baseline, accelerated packaging adoption, and slower node transition) — the report’s reproducible models are designed for exactly this purpose.
How PW Consulting’s study supports executive decisions
Our report is explicitly structured to convert market intelligence into executable plans. It combines rigorous market-sizing (2020–2025 history; 2026–2032 forecast), vendor benchmarking, technical deep dives, regulatory cost modeling, and procurement playbooks. That combination enables cross‑functional teams — strategy, operations, procurement, and R&D — to align around a single, data‑driven plan for 2026 and beyond.
For senior teams ready to move from strategic intent to tactical execution, the complete study contains the detailed regional, type, and application splits, line‑item TCO models, vendor scorecards, and the scenario files referenced above. These granular datasets are intentionally gated to preserve the analytical integrity of the market model and to ensure clients receive a reproducible, auditable basis for board‑level decisions.
Next steps
-
Request the executive package to receive the reproducible forecasting workbook and vendor scorecards for internal stress‑testing.
-
Schedule a strategy workshop with PW Consulting to map the 2026 CAPEX cycle to emissions‑reduction investments and supplier contracts.
-
Engage on a short due‑diligence sprint if contemplating supplier consolidation or an M&A target in the plasma equipment space — our rapid diligence playbook compresses the timeline to decision.
PW Consulting’s Plasma Etch System Market study equips 2026 decision‑makers with the market context, risk‑adjusted scenarios, and commercial playbooks necessary to capture the next phase of growth while managing compliance and input‑cost shocks. For access to the complete dataset, vendor matrices, and reproducible models, contact our research team to obtain the full report and client briefing.
For detailed analysis of this topic, please visit the official page: Plasma Etch System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com