

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Dashcam Market to Reach USD 344.8M by 2032 at 8.5% CAGR

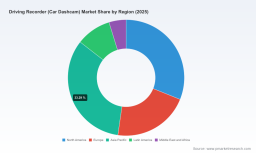
Driving Recorder (Car Dashcam) Market 2026 Outlook: Strategic Implications for Decision Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a forward-looking primer to our comprehensive Driving Recorder (Car Dashcam) Market study. This preview distills the macroeconomic trajectory, competitive dynamics, supply-chain stress points, and actionable options that matter for corporate decision-making in 2026 — while preserving the granular segment intelligence available only in the full report.
Driving Recorder (Car Dashcam) Market
Why this market matters in 2026
The driving recorder market has moved from a niche safety accessory to a strategic node linking vehicle security, telematics, ADAS integration, and fleet risk management. After a period of post‑pandemic recovery and product refresh cycles (2020–2025), the market expanded from the low hundreds of millions to an estimated USD 215.0 Million in our 2025 base year, and is forecast to grow at a robust compound annual growth rate (CAGR) of 8.5% through our 2026–2032 forecast window. By the end of the forecast period, the addressable market reaches roughly USD 345 Million — not an enormous absolute scale, but one with outsized strategic leverage for players who can convert hardware into data- and service-driven revenue streams.
Driving Recorder (Car Dashcam) Market
Key takeaways for 2026 corporate strategy
- Monetize beyond the device: Value is shifting from standalone hardware to recurring services — cloud storage, AI analytics, and fleet telematics. Companies that package subscriptions and analytics with hardware see higher lifetime revenue per unit.
- Platform partnerships trump point products: OEMs and fleet operators are increasingly demanding integrated camera + ADAS + telematics stacks. Strategic alliances or OEM supply agreements will accelerate adoption more than traditional retail channels.
- Supply-chain resilience is now a competitive moat: Memory and semiconductor availability are constraining output and driving cost volatility. Firms that secure long‑term allocations or vertically integrate critical sourcing will protect margins and delivery timelines.
- Regulation and national security considerations are shaping go-to-market routes: Export-control discussions and national security bills are increasing scrutiny on camera and chipset sourcing — a factor that impacts global distribution strategies and supplier selection.
Market dynamics: drivers, headwinds, and inflection points
Technology convergence is the primary growth driver. We see three parallel trends: image-sensor and computational upgrades enabling 4K/2K recording and low-light performance; embedded AI that powers driver coaching, object recognition, and event triage; and cloud connectivity that turns episodic recordings into longitudinal datasets for insurance, compliance, and predictive safety. These capabilities are being incorporated into both aftermarket products and OEM systems, creating cross‑pressure across channels.
Driving Recorder (Car Dashcam) Market
On the supply side, several material constraints and policy shifts are increasingly relevant for 2026 planning. Memory chip pricing surged dramatically since late 2025 due to AI data‑storage demand and allocation priorities among suppliers, while semiconductor lead times have spiked — with top-component lead times reaching levels unheard of in stable markets. Such constraints are not transient; they demand procurement redesigns, strategic buffer inventories, and sourcing diversification.
Policy and national-security trends add a layer of complexity. Legislative activity in multiple jurisdictions impacting export controls and critical-technology transfer increases transaction friction for vendors that rely on cross-border supply chains or cloud services hosted in geopolitically sensitive regions.
Competitive landscape — who matters and why
The market remains moderately fragmented: the top three incumbents capture roughly a third of market revenue, and the top five approach half. That concentration profile signals both opportunity and competition: there is room for regional specialists, differentiators built on AI and cloud services, and converged OEM solutions.
- Viofo (Shenzhen): Known for professional-grade imaging using advanced Sony sensors and multi-channel recording — strong in performance-conscious aftermarket segments.
- BlackVue / Pittasoft (Seongnam-si): Positioned at the premium end with cloud-enabled systems and parking-mode security — attractive for fleet and high-end consumer buyers seeking integrated cloud features.
- 70mai (Shanghai): Leverages AI and smart‑car integration to capture connected-device buyers and value-conscious consumers who prioritize intelligent features.
- Garmin (Olathe): Brings broad automotive electronics expertise, GPS integration and strong brand recognition — useful in channels where voice and navigation integration matter.
- Thinkware (Coquitlam): Competes in premium segments with ADAS integration, radar-assisted parking surveillance, and mobile connectivity — increasingly relevant as ADAS and dashcam functions converge.
- Vantrue, Nextbase: High-resolution recording and fleet-oriented product lines keep these vendors relevant across consumer and B2B fleets.
Recent product launches are accelerating capability expectations. Notable launches include Geotab’s AI-focused fleet camera and Thinkware’s flagship U3000 with integrated RADAR sensing and STARVIS 2 sensors — both underline the market shift toward sensor fusion, AI analytics, and fleet-grade reliability. BlackVue’s triple‑camera, cloud-compatible DR770X Box likewise strengthens parking-surveillance propositions for fleets.
Where the strategic battlegrounds will be in 2026
- Fleet telematics and safety services: Rapid risk reduction pilots and voice/alert systems are proving commercial value; fleet operators prioritize solutions that measurably lower insurance and accident costs. Expect procurement cycles focused on demonstrations of ROI, not just feature lists.
- OEM integration: Automakers are evaluating next‑gen front-camera modules that combine ADAS and recording functions. Suppliers with modular, certifiable camera+compute modules can win OEM slots and higher ASPs.
- Consumer ecosystem play: Subscription bundles that include cloud storage, theft protection, and behavioral coaching can transform unit economics for hardware-first vendors.
- Service differentiation via AI: Sophisticated analytics that triage events, reduce false positives, and enable automated claims handling will create stickiness and pricing power.
Practical implications — decisions to prioritize in 2026
- Procurement & sourcing: Reassess contracts for memory and SoC suppliers; secure allocation agreements, consider second-source qualification, and model buffer inventories into working capital forecasts.
- Product roadmap: Invest selectively in sensor fusion and onboard AI capabilities. Prioritize architectures that allow OTA upgrades and edge-cloud partitioning to enable future services.
- Commercial model: Build subscription pilots with insurers and large fleets to prove ARR pathways; use pilot results to shift channel incentives and reseller economics.
- M&A & partnerships: Target small AI analytics firms, telematics platforms, or regional distribution partners to accelerate service capabilities and market access.
- Regulatory & compliance: Establish a compliance function to track export controls and national-security legislation that could affect sourcing or cloud-hosting choices.
What PW Consulting’s full report delivers
This preview is deliberately selective. The full Driving Recorder (Car Dashcam) Market report provides the operative, transaction‑ready intelligence executives and investment teams need to act in 2026, including:
- Proprietary market-sizing with historical (2020–2025) validation and scenario forecasts (2026–2032) under multiple macroeconomic assumptions;
- GTM and pricing playbooks tailored for aftermarket, OEM, and fleet channels;
- Granular segmentation matrices across form-factor, functionality, and application — and an interactive sensitivity model for stress‑testing pricing and supply shocks;
- Detailed supplier maps and component-level cost curves to support sourcing negotiations and make-or-buy decisions;
- Commercial due-diligence templates, M&A target shortlists, and market-entry checklists;
- Risk heatmaps covering supply-chain, regulatory, and technological threats with mitigation roadmaps.
To preserve the research utility of the report, this preview omits the full segmentation tables and the detailed regional/application breakdowns that underpin our revenue forecasts. If your strategic questions require segment-level revenue, channel share, unit pricing, or a vendor-by-vendor supplier-capability comparison, the source report contains those datasets and the model files we use for scenario analysis.
Recommended next steps for executives
- Commission a short (4–6 week) commercial pilot with clearly defined KPIs (incident reduction, claims processing time, subscription uptake) if you are a fleet operator or insurer.
- For suppliers: embed component allocation clauses and negotiate lead-time protections with key vendors now; parallelize second-source qualification programs.
- For investors: request the full PW Consulting data room to evaluate M&A targets against our valuation sensitivity model — the market’s moderate concentration and rising services mix create attractive bolt-on opportunities.
- For OEMs and Tier‑1 suppliers: prioritize modular camera+compute architectures that support certification, OTA updates, and tiered service offers.
Concluding perspective
The driving recorder market in 2026 is small enough that nimbleness matters, and large enough that scale and platform plays pay. Hardware remains the entry ticket, but software, cloud services, and procurement sophistication determine margin capture. With a projected mid-single-digit to high-single-digit CAGR and concentrated but contestable leadership, companies that secure supply, build service economics, and form strategic partnerships will convert a modest market into a differentiated competitive advantage.
Access the full PW Consulting Driving Recorder (Car Dashcam) Market report for the segmentation detail, raw datasets, vendor scorecards, and execution playbooks that will make your 2026 decisions both defensible and actionable.
For detailed analysis of this topic, please visit the official page: Driving Recorder (Car Dashcam) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com