

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Surround-View Market to Reach USD 344.8 Million by 2032 (14.51% CAGR)
By pmarketresearch, 2026-07-09
Automotive Surround-View Systems Market: Strategic Imperatives for 2026 Decision‑Makers
As vehicle architectures accelerate toward higher levels of driver assistance and electrified platforms, surround‑view systems have transitioned from niche convenience features to foundational perception layers for parking, low‑speed autonomy and urban maneuvering. PW Consulting’s latest market study—anchored on a 2025 base year and a 2026–2032 forecast window—captures this transition with a data‑driven narrative: the global market surpassed USD 215 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 14.51% through the forecast period, reaching an estimated USD 345 Million by 2032. For executives setting 2026 priorities, this trajectory demands a recalibration of product, supply chain and partnership strategies to capture value in a maturing yet fast‑growing segment.
Automotive Surround-View Systems Market
Why this study matters for 2026 strategic decisions
- Timing of investment matters: With the market growing at a double‑digit pace, investments initiated in 2026 will determine whether companies secure design wins that compound over the next seven years. The study identifies which technology bets are likely to be de‑risked by 2028 and which will remain optional equipment well into the next decade.
- Architecture choices are value multipliers: OEMs and Tier‑1s that adopt modular, software‑defined surround‑view architectures—capable of integrating AI preprocessing and scalable ECU horsepower—can capture a higher value share than those retaining monolithic, hardware‑centric approaches.
- Regulatory alignment is non‑negotiable: Compliance expectations (UNECE R79, FMVSS 111, IATF 16949 and relevant imaging hardware standards such as ISO 11201) are tightening validation timelines. The report maps these regulatory inflection points to program milestones so engineering, quality and procurement teams can avoid late‑stage design rework.
What the report delivers: actionable intelligence, not academic theory
PW Consulting’s report is designed for commercial and product leaders who must translate macro growth into executable plans. Rather than presenting broad strokes, the study provides:
Automotive Surround-View Systems Market
- Scenario‑based demand forecasts that link penetration curves to vehicle production ramps, option take‑rates and aftermarket/retrofit channels—enabling revenue‑backed business cases for 2026 capital allocations.
- Technology roadmaps that compare imaging sensors, lens families, fusion strategies and AI‑assisted perception stacks—highlighting migration paths from 2D stitched views to 3D/semantic surround perception.
- Supplier and OEM playbooks: procurement scorecards, qualification checklists and commercial negotiation levers tailored for both Tier‑1 supply agreements and strategic minority investments.
- Integration blueprints—hardware, middleware and over‑the‑air software update considerations—to shorten time‑to‑market for new variants and to control total cost of ownership across vehicle fleets.
- A focused risk register covering technical, regulatory, supply and competitive risks with mitigation guidance calibrated to common program timelines (concept, validation, ramp, sustainment).
The report purposefully refrains from publishing sensitive segmentation tables within the executive summary: detailed regional, application and component splits are available in the full study, where readers can interact with scenario toggles and download granular matrices for their internal planning tools.
Automotive Surround-View Systems Market
Competitive landscape: who leads, why it matters
The surround‑view market demonstrates moderate concentration: the top three global suppliers account for roughly 62% of market value, while the top five hold about 65%. This concentration reflects a winner‑takes‑most dynamic on large OEM programs, but it also hides a layer of niche innovation and fast‑moving start‑ups that can influence feature roadmaps. Our competitive analysis focuses on strategic positioning rather than raw share numbers, profiling the capabilities that matter for 2026 program decisions.
- Continental AG (Hanover, Germany) — Known for its ProViu 360 platform, Continental combines 3D imaging with AI‑enhanced object detection targeted at parking assistance and close‑range safety. Their strength lies in system integration and broad OEM relationships that ease program adoption for safety‑critical applications.
- Valeo SA (Paris, France) — Valeo’s surround‑view portfolio emphasizes 360° visibility and human‑machine interface convenience. They compete on packaged solutions that reduce OEM integration effort and are often positioned as upgrade paths for mid‑segment vehicle lines.
- Magna International Inc. (Aurora, Canada) — Magna focuses on 3D surround systems paired with electronic control units (ECUs), offering end‑to‑end subsystems that can be configured for blind‑spot monitoring and parking automation. Their strength is in manufacturing scale and flexible vehicle integration capabilities.
- Aptiv PLC (Schaffhausen, Switzerland) — Aptiv’s strategy centers on ADAS‑integrated platforms and multi‑camera arrays designed to feed perception stacks for higher‑level driver assistance. Their offerings appeal to OEMs aiming to harmonize surround view with broader sensing strategies.
- Robert Bosch GmbH (Gerlingen, Germany) — Bosch markets second‑generation 360° camera systems focused on robust video‑based object detection and reliability in diverse environmental conditions. Their engineering advantage is long experience in automotive safety systems and rigorous validation processes.
- Denso Corporation (Kariya, Japan) — Denso delivers camera modules integrated into platform architectures, aiming for efficiency in production and predictable performance across vehicle variants. They are a preferred partner where tight supplier vehicle integration is a priority.
Each of these players pursues a distinct mix of vertical integration, modularity and software capabilities. The full report contains a supplier matrix that cross‑references these strategic dimensions against OEM program needs and validates potential partner fit for 2026 procurement cycles.
Technology and validation dynamics shaping procurement
- AI and edge analytics: Recent vendor integrations—such as Renesas’s addition of AI‑supported imaging analytics into surround monitoring platforms—have demonstrated measurable safety improvements (reported collision prevention gains on the order of a third in certain implementations). These capabilities shift system value from raw sensor count to perception quality and compute efficiency.
- Hardware‑software co‑design: Commodity camera sensors are increasingly commoditized; differentiation comes from firmware, calibration tools and perception middleware. Suppliers who provide validated OTA update paths and continuous learning pipelines will command premium positions.
- Standards and test regimes: Compliance with UNECE and FMVSS requirements, IATF quality regimes and electromagnetic/noise standards (e.g., ISO 11201 for imaging hardware noise emission) translates into discrete program tasks: documented validation plans, calibration traceability and production quality gates. Our report maps these obligations to development milestones to avoid costly late changes.
Strategic playbook for 2026
Based on the market trajectory and competitive dynamics, PW Consulting recommends a focused set of actions for 2026 decision‑makers:
- Decide architecture by Q2 2026: Commit to either a modular, software‑centric platform or a vertically integrated ECU‑centric approach. Late reversals are expensive; our breakeven analyses show when one choice dominates depending on anticipated option take‑rates and software monetization plans.
- Prioritize perception quality over camera count: Early investments in AI preprocessing and sensor fusion can reduce total system cost while improving detected object fidelity—critical for urban environments and fleet use cases.
- Lock in supply‑chain flex: Negotiate multi‑source options for critical camera modules and secure long‑lead sensors to mitigate node‑level shortages. Use supplier scorecards and KPIs from our study to structure earn‑outs and quality incentives.
- Embed regulatory signoffs in program gates: For OEMs targeting global launches, validate against UNECE, FMVSS and IATF checkpoints within design‑freeze windows to prevent costly requalification.
- Plan software monetization and lifecycle economics: Build OTA delivery and feature‑tiering into the first production release to enable post‑launch revenue streams and iterative safety improvements.
How to use this report in boardroom decisions
Boards and executive teams should treat the surround‑view market as a strategic enabler of broader ADAS and autonomy roadmaps rather than a discrete feature line item. The study provides the financial templates, supplier comparison tools and regulatory mapping required to translate product roadmaps into capital allocation decisions, M&A screening criteria and partnership frameworks. For CFOs, the report includes sensitivity matrices that quantify how option take‑rates and component cost declines impact program IRR across the 2026–2032 window; for CTOs, there are fast‑track integration checklists and validation sequences aligned to industry standards.
Next steps: where to find the granular intelligence
This introduction outlines the high‑level strategic implications and competitive dynamics crucial to 2026 decision cycles. PW Consulting’s full Automotive Surround‑View Systems Market report contains the granular matrices, interactive scenario models and supplier scorecards required to operationalize these insights—including regional penetration forecasts, component-level cost curves, and OEM program matchup tables. Accessing the complete study will equip your team with the actionable artifacts to win design‑ins, structure supplier contracts and optimize your product roadmap in a market growing at ~14.5% annually.
For teams preparing 2026 budgets and product roadmaps, the timing to act is now: the market’s growth profile rewards early clarity on architecture, supplier partners and regulatory sequencing. PW Consulting’s full report delivers the precise, operational intelligence you need to convert that clarity into competitive advantage.
For detailed analysis of this topic, please visit the official page: Automotive Surround-View Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Insight: Dry Film Market to Reach USD 1,744.04M by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-09
Dry Film Market: Strategic Intelligence for 2026 Decisions
As PW Consulting’s Lead Industry Analyst, I present a concise, decision-focused brief that frames the strategic value of our forthcoming Dry Film Market study for executives planning 2026 horizons. The dry film sector—spanning photoresists, solder masks, and solid-film lubricants—has returned to sustained growth after pandemic-era adjustments and is poised to meaningfully re-shape supplier strategies, capital allocation, and product roadmaps into the early 2030s. Our analysis synthesizes historical performance (2020–2025), forward-looking scenarios (2026–2032), and actionable intelligence to help leaders convert market movement into competitive advantage.
Dry Film Market
Why this study matters for 2026
-
Macro clarity in an uncertain cycle: The overall dry film market has expanded from a mid-single-hundred million baseline in 2020 to an estimated USD 1.115 billion in our 2025 base year. Under a 6.5% CAGR projection, the market trajectory through 2032 reveals material upside for firms that time investments and partnerships effectively.
Dry Film Market -
Concentration shapes strategy: With industry concentration materially favoring a small set of established suppliers, competitive moves by top vendors (product launches, capacity additions, formulation upgrades) can rapidly alter access to advanced materials and premium margins. Our report quantifies concentration metrics and models their implications on supplier bargaining power.
Dry Film Market -
Regulatory and material inflection points: New PFAS-free formulations, stricter aerospace/military specs, and volatile feedstock costs are raising the operational bar—forcing C-suite tradeoffs between short-term margin protection and longer-term compliance-driven differentiation.
What you’ll gain from the full study (high-level)
-
Actionable market-sizing and trend scaffolding: We provide a transparent top-down market model anchored to 2025 as the base year, with scenario runs that capture demand elasticity, price pass-through, and technology substitution through 2032.
-
Scenario-driven capacity planning: Practical tools to evaluate when to expand, delay, or outsource production—incorporating lead times for specialty coating lines, formulation qualification, and customer requalification cycles common in PCB and aerospace programs.
-
Supply-chain stress-testing: A modular heat-map that links raw-material volatility—polymers, photoinitiators, specialty additives—to margin compression under different procurement strategies and hedge positions.
-
Regulatory readiness playbook: Stepwise requirements for PFAS alternatives, MIL-spec approvals, and IPC standard compliance—plus a timeline matrix showing typical qualification durations across defense and commercial OEMs.
-
Commercial playbooks: Go-to-market approaches tailored to high-density IC packaging, rigid-flex PCB customers, and aerospace prime contractors—covering value-based pricing, co-development structures, and distributor partnerships.
-
M&A and partnership diagnostics: A checklist and valuation overlays that highlight when bolt-on acquisitions or manufacturing alliances produce the highest risk-adjusted returns.
Competitive landscape—who moves markets
The sector is anchored by several companies whose recent moves and product portfolios materially influence supplier selection, technical availability, and pricing dynamics. Below I summarize the strategic posture of ten key players we scrutinize in depth in the full report. These company sketches are paired with implications—not raw financials or segment-level shares—to help executives prioritize engagement.
-
Taiyo America (San Diego) : Focused on high-resolution solder mask solutions for flexible and ultra-fine-line PCBs. Their FLEXFINER launch (Aug 2025) signals an offensive into tight-registration flexible substrate niches—areas where design-to-manufacturing alignment yields premium pricing and long qualification cycles. Strategic implication: suppliers of advanced flex substrates and contract manufacturers must evaluate Taiyo’s offering for potential co-development or lock-in risk.
-
DuPont de Nemours, Inc. (Wilmington) : Offers a broad Riston portfolio addressing advanced PCB and semiconductor patterning requirements. As a legacy materials player, DuPont’s strength is integrated chemistry plus global qualification reach—making them a default partner for OEMs migrating to higher-density patterning. Strategic implication: incumbents and challengers should model DuPont’s pricing and channel influence when planning market entry.
-
Eternal Materials (Taichung) : Recently approved capacity expansion (Jan 2025) for photoresists, solder masks and polyimide lines. Their investment reflects anticipated demand from regional EMS and semiconductor packaging customers. Strategic implication: regional supply resilience and lead-time containment will increasingly be a competitive lever in APAC-heavy supply chains.
-
Showa Denko Materials (Tokyo) : Emphasizes photoimageable solder masks and photoresist formulations suited to precision boards. Their product depth supports customers requiring tight process windows and repeatable yields. Strategic implication: OEMs with high-fidelity manufacturing requirements should prioritize multi-source strategies to mitigate single-supplier disruptions.
-
Kolon Industries (Seoul) : Markets Trumask photoresist and solder mask lines with an eye on integration with substrate makers. Strategic implication: substrate-material integration can shorten qualification timelines for new board designs but raises switching costs—an important factor for contract electronics manufacturers.
-
Curtiss-Wright Corporation (Charlotte) : Supplies solid-film lubricants (Everlube, Ecoalube) targeted at aerospace/high-temperature industrial use. Product updates (Jan 2024) show continued demand for high-performance, high-temperature lubricants. Strategic implication: prime contractors and Tier-1 suppliers must balance longer relubrication intervals promised by these materials against higher unit costs and qualification effort.
-
Tiodize (Huntsville) and Sandstrom Products (Port Byron) : Both provide military-grade solid film lubricants—emphasizing precision aerospace application and military-spec compliance. Strategic implication: defense supply chains remain a core, high-margin vertical that rewards deep process knowledge and compliance infrastructure.
-
MacDermid Alpha Electronics Solutions (Waterbury) : Offers adhesion promoters and integration services—an important bridge product that reduces defect rates for advanced solder masks and photoresists. Strategic implication: value-added services and formulation integration are potent differentiation routes for mid-sized suppliers.
-
Agfa-Gevaert Group (Mortsel) : Known for precision dry film photoresists and solder masks for both PCB and semiconductor markets. Strategic implication: European customers seeking geographically diversified supply options consider players like Agfa to manage regional regulatory and logistics risks.
Key market dynamics shaping 2026 choices
-
Raw material volatility: Polymer and specialty chemical price swings are a recurring margin risk. We model multiple procurement responses—multi-sourcing, strategic stockpiles, tolling partnerships—and quantify break-even points for each.
-
Regulatory pivot to PFAS-free and ceramic-based chemistries: New PFAS-free formulations and ceramic-based lubricants are being introduced, and while they often carry a price premium, they reduce regulatory and reputational risk. Our assessment maps which customer segments will pay premiums and the expected payback timelines.
-
Standards and qualification timelines: Military and aerospace standards plus IPC updates are extending qualification lead times for novel formulations. We estimate typical requalification windows and the operational impacts on inventory and production scheduling.
-
Concentration and bargaining dynamics: The market’s top-tier suppliers control a meaningful share of advanced formulations. That concentration creates both barrier effects for challengers and opportunity windows for niche players serving specialized applications.
Practical takeaways and recommended 2026 actions
-
Run an immediate supplier resilience stress-test: Map single points of failure in feedstock and specialty chemical supply chains and stress-test procurement strategies against 6–12 month price shock scenarios.
-
Prioritize PFAS-free roadmap and defense-spec compliance: If you serve aerospace, defense, or regulated industrial clients, accelerate qualification programs today—delays add materially to TTM and can cede share to qualified incumbents.
-
Evaluate selective capacity vs. partnership: For firms considering expansion, use scenario models (available in our report) to compare greenfield, tolling, or JV options under low, base, and high demand cases.
-
Consider M&A and tech licensing as fast-follow moves: Given concentration, acquiring niche formulation expertise or licensing specialized chemistries can shorten time-to-market with lower capital outlay than building internal R&D/production capabilities.
-
Adopt a differentiated commercial playbook: For customers in HDI, rigid-flex, or semiconductor packaging, pair materials with process support and qualification services to command premium margins and lock-in higher lifetime value.
What we intentionally withhold here—and why
In line with our “trailer” principle, this brief highlights the frameworks, competitive context, and tactical implications you need to decide whether to act in 2026. Detailed segmentation tables, granular regional/application revenue splits, full company revenue share models, and downloadable valuation spreadsheets are reserved for the full PW Consulting Dry Film Market report. Those proprietary deliverables contain the calibrated assumptions, excel models, and supplier scorecards executives need for board-level approval of capital and procurement plans.
Next steps
If your 2026 planning requires prioritized supplier lists, go/no-go qualification timelines, or a custom scenario run on capacity or pricing, contact PW Consulting to license the full report or commission a tailored engagement. The macro picture is clear: the dry film market is growing, concentrated, and subject to regulatory and raw-material inflection points that make timely, informed action both high-value and urgent.
For detailed analysis of this topic, please visit the official page: Dry Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Chromatography Syringes Market to Reach USD 82.2M in 2025
By pmarketresearch, 2026-07-09
Chromatography Syringes Market: Strategic Imperatives for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present an executive preview of our newest Chromatography Syringes Market study — a practical, decision-focused briefing designed to shape boardroom choices in 2026. The market has expanded steadily over the 2020–2025 historical window and is projected to continue growing through our forecast period (2026–2032) at a compound annual growth rate of 5.6%. Measured in USD Million, the industry’s total market sizing and trajectory are core inputs to every strategic recommendation in this dossier. This preview demonstrates the analytical depth of the full study while deliberately withholding granular segment and regional splits to guide you to the complete report for transaction-grade detail.
Chromatography Syringes Market
Market trajectory: what the numbers mean for strategy
-
Momentum and scale: The market’s recovery and steady rise from the historical base demonstrates resilient demand across laboratory, pharmaceutical, and environmental testing end‑markets. Forecast growth to 2032 reflects not only baseline replacement demand but also structural shifts — automation, single‑use adoption, and traceability requirements — that increase average selling prices and per‑lab consumption.
Chromatography Syringes Market -
Fragmentation with pockets of influence: Market concentration metrics indicate a mid-level consolidation posture — leaders hold meaningful influence but buyers still see multiple credible suppliers. This creates both defensive pressures for incumbents and attack surfaces for challengers pursuing niche specialization or integrated systems plays.
Chromatography Syringes Market -
Unit economics and value capture: As labs push for higher throughput, the willingness to pay for precision, reduced carryover, and smart traceability features rises. Strategic moves that capture service and consumables revenue streams — not just one‑time hardware sales — will disproportionately lift margins in a market growing at a steady mid-single-digit CAGR.
Key demand and technology drivers
-
Automation and autosampler proliferation: Adoption of autosampler-compatible syringes is a primary structural driver. Automated platforms increase per‑instrument consumption of precision syringes and raise the bar on tolerance, durability, and compatibility.
-
Single-use preference and sterilization economics: High-throughput environments are favoring single‑use designs to eliminate cleaning cycles and cross‑contamination risk. This shifts procurement from capital expenditure (reusable syringes plus cleaning) to ongoing consumable spend.
-
Regulatory and materials pressures: Global regulations (including REACH, RoHS) and stringent laboratory certification requirements (FDA expectations, ISO 11040 series) are raising the technical bar for materials selection, testing protocols, and traceability. Non-compliance risks are now commercial risks.
-
Sustainability trade-offs: Buyers face a trade-off between single‑use convenience and material sustainability. Companies that reconcile eco‑design with single‑use economics — for example through bio‑based polymers, take‑back programs, or lifecycle carbon accounting — will win preferential access to certain buyers and tenders.
What the full PW Consulting report delivers (practical content for 2026 planning)
-
Validated market sizing and forecast models (2020–2032) with scenario variants to stress‑test your 2026 plans.
-
Demand-driver mapping and use‑case prioritization to align R&D and sales targets with highest-value applications.
-
Competitive benchmarking: capability matrices, technology roadmaps, product portfolios, and go‑to‑market positioning for the leading suppliers and credible challengers.
-
Supply‑chain and procurement playbooks, including dual‑sourcing templates, lead‑time sensitivity models, and cost to serve analyses.
-
Regulatory compliance matrix that translates REACH, RoHS, FDA guidance, and ISO 11040 requirements into actionable product design and validation checkpoints.
-
M&A and partnership heatmaps: likelihood-of-success scoring for bolt‑on acquisitions and co‑development alliances, complete with valuation sensitives and integration risk flags.
-
Commercial execution toolkit: pricing levers, contract templates, service bundling strategies, and commercial KPIs calibrated to the market’s growth trajectory.
-
Interactive Excel models and slide decks that executives can use in 2026 budget rounds, investor presentations, and due‑diligence processes.
Competitive landscape — who matters and why
The competitive set includes global instrument and consumable specialists, each offering differentiated strengths that matter for strategic decision-making:
-
Hamilton Company (Reno, NV): Known for precision HPLC and GC syringes — both autosampler and manual — with advanced plunger technologies to minimize carryover and maximize chemical resistance.
-
Agilent Technologies (Santa Clara, CA): Supplier of autosampler syringes and needles optimized for high‑throughput automated platforms; recent strategic moves emphasize integrated systems development.
-
Thermo Fisher Scientific (Waltham, MA): Offers gas‑tight and fixed‑needle options with digital traceability features for reproducible injections in regulated labs.
-
Shimadzu Corporation (Kyoto, Japan): Supplies both manual and autosampler syringes with a focus on durability and optical clarity for chromatography workflows.
-
Restek / SGE Analytical Science (Bellefonte, PA & Ringwood, Australia): Specialist precision syringes and cross‑brand compatibility for diverse instrument ecosystems.
-
VICI AG International (Schenkon, Switzerland): Focused on integrated syringe systems and components that enable automation OEMs and integrators.
-
Gilson, PerkinElmer and other analytical vendors: Provide complementary product lines and distribution reach important for route‑to‑market strategies.
Recent industry moves underscore strategic direction: a major acquisition expanded one OEM’s consumables portfolio in 2024, while a strategic partnership between a leading instrument vendor and syringe systems specialist signals acceleration toward integrated automation solutions. These events illustrate two viable competitive playbooks — horizontal consolidation to own consumables, and vertical integration through systems partnerships.
Practical strategic implications for 2026 decision-makers
-
Prioritize autosampler and automation-compatible SKUs in product roadmaps. The combination of higher throughput and willingness to pay for reliability means faster revenue uplift and stickier procurement relationships.
-
Invest in traceability and digital features. Smart identification and reproducibility capabilities reduce customer risk and justify premium pricing, particularly for regulated pharmaceutical and clinical lab customers.
-
Build a compliance-first product design process. Translate REACH / RoHS and ISO 11040 test requirements into documented design gates to speed customer qualification and reduce costly rework during audits.
-
Scale single‑use manufacturing capacity while designing sustainability offsets. Single‑use will dominate many high‑throughput workflows, but buyers increasingly select suppliers who can present credible lifecycle and recycling strategies.
-
Pursue selective M&A and partnerships. Given market concentration metrics, bolt‑on acquisitions that add automation compatibility, materials expertise, or service capabilities are likely to deliver the best ROI vs. broad horizontal consolidation.
-
Secure supply chains proactively. Dual‑sourcing of critical materials and nearshoring where feasible will be decisive in avoiding disruptions that ripple into customer relationships.
-
Monetize services. Field calibration, validation support, and consumable subscription bundles increase lifetime value and smooth revenue seasonality.
How to use this preview in your 2026 planning cycle
-
Board and executive teams: use our scenario models to stress‑test capital allocation between manufacturing scale‑up, R&D for smart syringes, and M&A options.
-
Product and R&D leaders: adopt the regulatory matrix and materials checklist as immediate inputs into 2026 design sprints and product validation timelines.
-
Commercial and procurement teams: apply our pricing levers and customer segmentation playbooks to 2026 tender and contract negotiations.
-
Corporate development: leverage the M&A heatmap and integration playbooks to prioritize targets and to build rapid diligence pipelines.
Note: this preview intentionally omits granular region and application split figures to preserve the strategic lead contained in our full dataset. The complete PW Consulting report unlocks transaction‑grade detail — including regional demand curves, application-level consumption, SKU-level pricing benchmarks, supplier share matrices, and downloadable financial models — to directly support M&A, procurement, and product roadmap decisions in 2026.
Next steps
For teams preparing budgets, vendor negotiations, or M&A pipelines in 2026, the full report provides the actionable datasets and templates required to convert insight into execution. Access the complete dossier to obtain the granular splits, interactive models, and supplier scorecards that will materially de‑risk and accelerate your 2026 plans.
For detailed analysis of this topic, please visit the official page: Chromatography Syringes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Enclosed Belt Conveyor Market to Hit USD 344.8M by 2032 at 7.1% CAGR
By pmarketresearch, 2026-07-09
Enclosed Belt Conveyor Market — Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s senior industry analyst, I present a focused, decision‑centric preview of our Enclosed Belt Conveyor Market study (base year 2025, historical 2020–2025, forecast 2026–2032). This briefing synthesizes the macro trajectory, competitive posture, and the operational dynamics that will matter to procurement, engineering leadership, OEM strategy teams, and investors planning actions in 2026. It intentionally demonstrates analytical rigor while withholding detailed segment-level allocations — a tactical “trailer” to motivate full report access for execution‑level intelligence.
Enclosed Belt Conveyor Market
Market snapshot: Where the market stands and where it is headed
Between 2020 and 2025 the global enclosed belt conveyor market recorded steady expansion, reflecting resilient demand from bulk handling sectors. The market grew from an aggregate that we track in 2020 to a larger consolidated size by 2025 (base year). Under our central projection, the market is expected to expand at a compound annual growth rate (CAGR) of 7.1% over the 2026–2032 forecast horizon, moving from the 2026 opening point through to a materially larger market by 2032. This pace reflects both recovery tailwinds in industrial CAPEX and structural tailwinds driven by automation, stricter dust‑containment regulation, and product innovation.
Enclosed Belt Conveyor Market
Why this matters for 2026 decision cycles
- Procurement and capex timing: A predictable mid‑single‑digit CAGR allows buyers to stage replacement and retrofit programs around multi‑year maintenance budgets rather than rush into spot procurements.
- Supplier selection and risk: The market remains relatively fragmented compared with heavy industrial equipment categories. Buyers that rely on a narrow supplier set will face availability and lead‑time risk if they don't diversify across vendors with different design philosophies (e.g., molded belts vs. steel enclosures).
- Product development prioritisation: R&D and product roadmaps should prioritize belting materials, dust‑containment seals, and low‑maintenance idler systems — features that buyers will pay a premium for as regulatory and operational pressures mount.
- Investment thesis clarity: Investors evaluating OEMs should weigh the stable CAGR against commodity exposure (raw steel, polymers) and the extent to which firms demonstrate differentiated IP or channel reach into high‑growth verticals.
Market dynamics driving growth and risk
- Regulatory acceleration: Recent industry standards and government mandates increasingly require near‑complete dust containment (approaching 99% in sensitive sectors such as food, cement, and fertilizer). This regulatory tightening converts into a purchasing imperative for enclosed solutions and premium designs that can demonstrably meet compliance tests.
- Raw material cost exposure: Production of enclosed belt conveyors is materially influenced by inputs such as galvanized steel (notably higher grades like G140) and engineering polymers (UHMW). These inputs can constitute a substantial proportion of unit cost, creating margin sensitivity for OEMs that lack hedging or sourcing strategies.
- Labor and automation pressures: Global labor shortages in industrial operations are accelerating adoption of enclosed conveyors which reduce operator requirements through safer, dust‑free continuous handling. Buyers value systems that reduce routine maintenance labor through proven low‑wear components.
- Technology and product innovation: Recent product introductions demonstrate a clear vendor focus on belting technology (high‑durability molded belts), higher capacity drive trains, and modular designs for rapid deployment. These innovations are changing procurement evaluation criteria from purely capital cost to total cost of ownership (TCO) and uptime metrics.
- Commodity cycle and project phasing: The market’s growth profile smooths the impact of cyclical end markets (mining, agriculture, ports), but project‑driven spikes remain a feature. Strategic purchasers should integrate supplier capacity and lead‑time forecasts into multi‑year capital plans.
Segmentation — what we analyse (and why we don’t publish every split here)
The full study contains rigorous segmentation by type, application, and geography across historical and forecast periods. We model demand drivers, replacement cycles, unit pricing dynamics, and supply‑chain cost stacks at the segment level. To preserve the utility of this preview and to comply with our “trailer” approach, we intentionally do not publish segment allocations or regional shares here; those actionable splits are reserved for the full report.
Enclosed Belt Conveyor Market
That said, readers should know we examine:
- Type choices (roller, spool, air‑cushion and hybrids) and their implications for incline capability, maintenance cadence, and TCO.
- End‑use applications (mining, agriculture, construction materials, and others) with differentiated replacement timelines and procurement drivers.
- Geographic demand patterns and project pipelines, contextualized with capex momentum across industrial subsectors.
Competitive landscape — profiles and positioning
The market is served by a mix of specialized OEMs and larger material‑handling firms. The competitive picture is characterized by niche engineering differentiation rather than dominance by a handful of global mega‑players. Key firms exemplify distinct value propositions:
- Ag Growth International (AGI) — Mokena, IL: AGI emphasizes both high‑capacity and dust‑tight designs with product lines tailored for grain handling. Their strength is channel presence in agricultural terminals and a focus on lifecycle performance for grain handlers.
- Cambelt International — Salt Lake City, UT: Cambelt’s proprietary one‑piece molded belting and high‑incline transloaders are positioned for installations where delamination risk and steep conveying profiles are deciding factors. Their IP around belting construction gives them a technical edge in certain bulk handling use cases.
- Bulk Conveyors, Inc. (BCI) — Wichita, KS: BCI competes on low‑maintenance, dust‑tight modules with proven serviceability. Their portfolio is attractive to industrial buyers prioritizing predictable uptime and minimal on‑site intervention.
- Kase Conveyors — Whitney, TX: Kase positions itself on customization — delivering bespoke enclosed conveyor systems for complex industrial layouts, which is valuable for retrofit projects and constrained plant footprints.
- Sweet Manufacturing — Spruce Hill, OH: With an emphasis on galvanized structural designs and robust construction, Sweet targets agricultural and industrial operators seeking long‑life, corrosion‑resistant systems.
- Warrior Mfg. — Hutchinson, MN: Warrior focuses on heavy‑duty idlers and UHMW liners for high throughput applications, appealing to mining and aggregate operations where abrasion resistance is central.
Across vendors, differentiation clusters around belting technology, enclosure metallurgy, idler and liner designs, and aftermarket service networks. Our concentration analysis shows that the top suppliers together do not overwhelmingly dominate the market, leaving room for regional champions and technology specialists to capture niche segments — an important fact for procurement teams seeking alternative sources or partners for co‑development.
Recent industry moves that signal near‑term shifts
- Major suppliers are pushing higher‑capacity and “smarter” conveyors that integrate durability improvements and condition monitoring — examples include product updates and launches across established OEMs in 2025–2026.
- Belting manufacturers have released belting optimized specifically for enclosed systems, reducing wear and improving incline performance — a trend that will reshape retrofit specifications and spare‑parts strategies.
- These product steps, coupled with ongoing regulation, are steadily moving buyer evaluation criteria from upfront price toward demonstrable TCO and regulatory compliance credentials.
What the full PW Consulting report delivers (practical, executable outputs)
- Quantified market sizing and growth scenarios (base year 2025, historical 2020–2025, forecast 2026–2032) with sensitivity testing against commodity and regulatory shocks.
- Segment‑level demand models and unit pricing curves to support capital budgeting and sourcing decisions.
- Supplier scorecards and comparative matrices emphasizing product features, aftermarket footprint, lead times, and financial health.
- Investment and M&A playbooks highlighting target profiles and integration risks for strategic buyers.
- Procurement templates and TCO calculators designed to convert technical spec choices into cash‑flow impacts over typical project horizons.
Strategic implications & recommended 2026 actions
- For OEMs: Prioritise belting R&D, modular enclosure systems, and expanded aftermarket coverage. Hedge raw material exposure through diversified sourcing or pass‑through contracts to protect margins during commodity volatility.
- For asset owners/operators: Reassess replacement vs. retrofit decisions through a TCO lens that incorporates regulatory compliance costs and labor savings. Consider multi‑year supplier partnerships to secure capacity and reduce lead‑time risk.
- For investors: Seek firms with proprietary belting or sealing IP, strong service networks, and demonstrable cost‑control mechanisms for steel/polymer procurement; these attributes materially de‑risk earnings against commodity cycles.
Conclusion — why access the full study
Our market preview contextualizes a growth story driven by regulation, automation, and targeted product innovation. The headline trajectory — a stable CAGR through the forecast horizon — sets the backdrop, but the real strategic value lies in the segment‑level demand drivers, supplier scorecards, and executable procurement and M&A playbooks contained in the full report. For teams preparing budgets, negotiating vendor contracts, or evaluating investments in 2026, those operating‑level insights will be decisive.
PW Consulting’s full Enclosed Belt Conveyor Market study contains the empirical detail and proprietary frameworks you will need to convert the market’s structural trends into boardroom decisions. Contact PW Consulting to unlock the full dataset, models, and supplier matrices required to act with conviction in 2026.
For detailed analysis of this topic, please visit the official page: Enclosed Belt Conveyor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tubular GEL Battery Market to Reach USD 1,200M in 2025, 5.83% CAGR (2026–2032)
By pmarketresearch, 2026-07-09
Tubular GEL Battery Market — Strategic Briefing for 2026 Decision-Makers
As energy architectures diversify and resilience becomes a board-level objective, tubular GEL batteries are re-emerging as a strategic asset class for stationary storage, telecom resilience and renewable energy integration. PW Consulting’s latest Tubular GEL Battery Market research (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes five years of market movement and models seven years of practical scenarios. This briefing highlights the strategic value of that research for executive decision-making in 2026, outlines what the full study delivers, and previews the competitive and regulatory dynamics shaping capital allocation and commercial strategies.
Tubular GEL Battery Market
Why 2026 is an Inflection Point
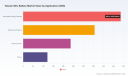
The tubular GEL segment has moved from niche to core in several stationary-storage use cases. Our market model reports the global market size at roughly USD 1.2 billion in 2025 and projects a compound annual growth rate (CAGR) of 5.83% over the 2026–2032 forecast window. By 2032 the market is modeled to approach approximately USD 1.78 billion under our central scenario. Those macro dynamics reflect a combination of steady demand in legacy backup and telecom, accelerated deployment in renewable-linked storage, and selective policy-driven demand that favors longer-life, deep-cycle chemistries.
Tubular GEL Battery Market
For corporate leaders, 2026 is the year to move beyond ad-hoc procurement and to operationalize a multi-year battery strategy that aligns product roadmaps, procurement cycles and manufacturing footprints with predictable market growth and evolving regulation.
Tubular GEL Battery Market
What the Full Report Contains (Practical, Actionable Components)
- Market architecture and sizing: validated time series (2020–2025) and a detailed 2026–2032 forecast with scenario variants (base, upside, downside) and sensitivity to price, raw material shocks and regulatory shifts.
- Go-to-market playbooks: differentiated templates for OEMs, system integrators, EPCs and project developers covering pricing strategies, channel design and lifecycle service models.
- Supplier and technology scorecards: comparative assessments of manufacturing scale, quality maturity, warranty practices and after-sales service readiness.
- Commercial models: TCO and LCOE-style analyses for key use cases (utility-scale hybrid, telecom huts, distributed solar-plus-storage) with inputs you can adapt to your project or portfolio.
- Risk and resilience matrices: regulatory, supply-chain and raw materials risk scenarios with contingency plans and hedging strategies.
- M&A and partnership playbook: valuation frameworks, diligence checklists and integration templates tailored to tubular GEL providers and adjacent battery businesses.
- Field validation: case studies and commissioning reports that illustrate real-world performance and failure modes across climatic and operational settings.
Note: this briefing intentionally omits granular segmentation tables and region/application shares — the full dataset and downloadable models are available through the report portal for subscribers and validated purchasers.
Competitive Landscape — Who Matters and Why
The tubular GEL market demonstrates moderate concentration: our market concentration metrics indicate that the top three suppliers collectively hold roughly a third of market revenue, and the top five capture under half. This structure creates both opportunity and strategic risk — market leadership exists, but regional and technological niches remain contestable.
- Exide Technologies (India) — long-standing industrial supplier with deep distribution networks across industrial and telecom channels; strength lies in scale and localized service capability for large project roll-outs.
- EnerSys (United States) — global footprint with a product portfolio oriented to renewable storage and standby power; differentiates through systems integration and warranty structures that appeal to enterprise and utility customers.
- Hoppecke Batteries (Germany) — European engineering-centric player offering OPzV tubular solutions for deep-cycle and stationary applications; positioned to capitalize on local content requirements driven by European policy.
- FIAMM Energy Technology (Italy) — niche industrial and motive-power supplier with strong OEM relationships in European and Mediterranean markets.
- Several China-headquartered firms (Leoch, Narada, Sacred Sun, Coslight, Ritar, CSBattery, BSB, Wolong, Shoto, Vision Group) — supply scale and cost competitiveness; many are increasingly active in system-level projects and global EPC partnerships.
- Microtex Energy (India) — notable for technology transfer and localized manufacturing using German technology platforms; a strategic partner for regional solar and UPS rollouts.
Recent project activity provides a useful barometer of commercial execution. In early 2026, Ritar International commissioned and connected integrated wind-solar-storage projects in Panama and Shenzhen — tangible confirmation that OPzV/tubular GEL systems are migrating from pilot to grid-connected commercial deployments. Such moves lower execution risk profiles and create referenceable performance data that accelerate procurement decisions.
Regulatory Tailwinds and Policy Noise
Two policy dynamics deserve immediate attention:
- Europe’s December 2025 Battery Booster Strategy has explicit measures that encourage localized manufacturing for tubular gel and other long-life stationary chemistries. For firms active in or entering Europe, the strategy is both an incentive and a competitive hurdle — localization commitments and compliance roadmaps must be integrated into any entry plan.
- India’s 2025 approval of viability gap funding (VGF) for a tranche of BESS capacity — including tubular gel solutions — materially de-risks project economics in domestic renewables integration. That funding reshapes procurement timelines and increases the attractiveness of localized suppliers with project execution capabilities.
Regulatory and market signals are not uniform: EU utility-scale deployments in 2025 were dominated by OPzV-type tubular GEL systems for a majority of new capacity in that region. Such concentration can change rapidly with shifts in ancillary services pricing, inverter strategy and policy design. The report’s policy-impact matrices help quantify these moves and their effect on procurement and manufacturing economics.
Strategic Implications for 2026 Decisions
Executives should move from passive observation to structured options analysis. Below are immediate, actionable implications drawn from our modeling and field validation.
- Procurement and inventory: lock multi-year supply agreements where price exposure is manageable, but include flexibility clauses tied to regulatory milestones and performance KPIs. For large projects, blend regional suppliers to mitigate geopolitical and logistics risk.
- Manufacturing footprint: prioritize modular, near-customer assembly over heavy upfront capital investments. The EU booster policy and India’s VGF make staged localization attractive for players with export ambitions.
- Product & warranty design: extend service portfolios — preventive maintenance, performance guarantees and second-life programs — to capture lifecycle revenue beyond cell sales and support higher total cost of ownership justification.
- M&A and partnerships: identify bolt-on targets that fill gaps in after-sales service, local certification, or EPC capability. The mid-range market concentration suggests accretive consolidation opportunities without immediate monopolistic risk.
- Project-level economics: apply the report’s TCO templates to evaluate hybridization (solar + tubular GEL) and to run sensitivities on cycle life, depth-of-discharge and warranty claims. These inputs materially change IRR and payback timelines.
- Risk management: build supply-chain resilience plans — alternate cathode/lead procurement, freight contingencies, and long-lead spares stocking — to mitigate single-source and logistic disruption exposures.
How to Use the Report in Organizational Decision Rhythms
Three use-cases where the research delivers immediate ROI:
- CapEx committees: use the central and stress-case forecasts to justify or postpone manufacturing investments; embed scenario outputs into investment memos.
- Procurement and Sourcing: deploy supplier scorecards and negotiation playbooks to secure favorable terms while preserving flexibility for regulatory or price shocks.
- Business development: leverage go-to-market templates and the competitive matrix to prioritize geographies and verticals where tubular GEL delivers differentiated value.
Closing—Why PW Consulting’s Study Matters for 2026
In 2026, tubular GEL batteries are neither a fringe option nor a homogenous commodity. They sit at the intersection of legacy reliability requirements and the modern drive for grid-edge decarbonization. Our research, grounded in a verified historical series (2020–2025), a 2025 base year, and a transparent 2026–2032 forecast framework (CAGR 5.83%), provides the practical analytics, benchmarking and playbooks needed to make defensible strategic choices.
The analysis showcased here intentionally signals our depth while reserving detailed segmentation tables, regional and application shares, and granular company financials for the full report. If your 2026 strategy depends on optimizing procurement, sizing manufacturing bets, evaluating M&A or designing warranty-backed service models in tubular GEL batteries, the full PW Consulting study contains the models and market intelligence you will need to execute with confidence.
For detailed analysis of this topic, please visit the official page: Tubular GEL Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Orthopedic Orthotics Market at USD 5,102M in 2025, 5.8% CAGR (2026-32)
By pmarketresearch, 2026-07-09
Orthopedic Orthotics Market 2026: Strategic Primer for Executives
Introduction — Why this study matters as you set 2026 strategy
As PW Consulting’s senior strategic advisor and lead industry analyst, I present a concise, decision-focused introduction to our latest Orthopedic Orthotics Market study. With an industry experiencing steady, technology-led expansion, the choices made in 2026 about product investments, commercial models, and regulatory positioning will disproportionately determine market share and margin performance across the remainder of the decade.
Orthopedic Orthotics Market
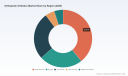
Our analysis covers the historical window of 2020–2025 (base year 2025) and provides a forward-looking forecast through 2032. At the macro level, the market has expanded from under USD 4.0 billion in 2020 to roughly USD 5.1 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of approximately 5.8% over the forecast period. By 2032 the market is expected to be materially larger than in 2025, reflecting both structural demand drivers and ongoing product innovation.
Orthopedic Orthotics Market
What this means for 2026 corporate decision-making
-
Investment cadence: With mid-single-digit CAGR and a multi-year runway, firms should prioritize staged investments that accelerate scalable product platforms (digital scanning, additive manufacturing, sensor integration) rather than one-off product bets.
Orthopedic Orthotics Market -
Commercial focus: The market dynamics reward firms that combine clinical evidence with pragmatic reimbursement strategies. Aligning product claims with coding, documentation, and payer evidence will unlock adoption pathways in both hospital and post-acute settings.
-
M&A and partnerships: Market concentration metrics indicate a space where strategic acquisitions and distribution partnerships can deliver outsized growth. A focused roll-up strategy for regional custom orthotics providers or component suppliers can enhance margins and distribution density.
Data-driven snapshot (high level)
Key reference points from our modeling:
-
Historical scope: 2020–2025 baseline analysis captures product introductions, reimbursement shifts, and supplier consolidation across the period.
-
Forecast horizon: 2026–2032 scenario modeling explicitly quantifies revenue trajectories under multiple adoption curves and reimbursement scenarios, using a 5.8% base-case CAGR.
-
Competitive intensity: Top-tier players account for a meaningful share of the market; our concentration analysis shows a moderately consolidated landscape (CR3 ~55.7%, CR5 ~72.1%). This favors scale players in components, distribution, and clinical services while leaving room for specialist entrants.
Market dynamics and regulatory context
Several practical dynamics shape near-term competitive advantage:
-
Reimbursement complexity: Public payers (notably Medicare Part B in the U.S.) continue to define coverage through specific coding and documentation requirements for off-the-shelf and custom braces. Navigating these rules is table-stakes for commercial success in mature markets.
-
Regulatory pathway: The FDA 510(k) pathway has been the predominant route for new orthopedic orthotic devices, meaning clearance timelines and predicate selection are critical project milestones. Firms should front-load regulatory strategy into product development to avoid last-minute redesigns.
-
Compliance risk: Suppliers of durable medical equipment (DMEPOS) operate under heightened fraud-prevention regimes that require demonstrable treating relationships and robust documentation. Operational hygiene and audit readiness are essential to mitigate payment clawbacks and reputational risk.
Competitive landscape — how leading players are positioned
We assessed incumbents across portfolio breadth, clinical focus, manufacturing footprint, channel strength, and adjacent-service capabilities. Highlights from our competitive mapping include:
-
Ottobock (Duderstadt, Germany) leverages a full orthotics portfolio and domain expertise in neuro-orthotics, offering both advanced mechanical systems and custom solutions for complex neurological and injury cases. Their R&D orientation makes them a benchmark for premium, clinically-focused offerings.
-
Össur (Reykjavik, Iceland) combines bracing and neuro-orthotics capabilities with a strong footprint in custom foot orthotics — emphasizing outcomes for stroke and neurological impairment pathways. Their products trend toward evidence-backed use cases and strong clinician engagement.
-
Bauerfeind (Pirmasens, Germany) emphasizes high-quality, European-made orthoses for joints and feet, with a strong brand association to stability and rehabilitation. Their approach highlights premium positioning and channel control.
-
U.S.-based specialists (examples include Breg, Acor Orthopaedic, Aspen Medical Products, and others) focus on category depth — from knee bracing and AFOs to spinal orthoses — combining product breadth with distribution in acute and post-acute settings. Recent product activity (for example Aspen’s late-2025 launch of a clinically informed maternity back brace) underscores ongoing innovation at the intersection of clinical need and differentiated design.
-
Component and subsystem suppliers (e.g., Basko Healthcare) and vertically-integrated national players (e.g., Allard USA, Trulife, Steeper Group) create a layered supplier ecosystem where partnerships and procurement strategies materially affect time-to-market and margin profiles.
What the report contains — pragmatic deliverables
The full PW Consulting study is organized to support immediate decision-making and includes:
-
Market sizing and forecasting models (2020–2032) with scenario toggles for adoption rates, reimbursement shifts, and pricing evolution.
-
Segmentation analysis by product type, clinical application, and geography, with growth levers and vulnerability heatmaps for each segment.
-
Competitive benchmarking and vendor scorecards covering product portfolios, go-to-market models, R&D pipelines, and manufacturing capabilities.
-
Commercial playbooks — pricing, tendering, payer engagement, and clinical evidence strategies tailored for providers, manufacturers, and distributors.
-
M&A and partnership targets with valuation ranges and integration risk assessments; supplier consolidation scenarios calibrated to market concentration dynamics.
-
Regulatory and reimbursement navigator — practical checklists for 510(k) strategy, coding alignment, and DMEPOS compliance readiness.
-
Operational tools including cost-to-serve models, manufacturing and supply-chain levers, and digital-customization playbooks (scanning, CAD/CAM, additive manufacturing).
Actionable recommendations for 2026 — five strategic moves
-
Prioritize modular platforms: Invest in modular product platforms that allow rapid customization without linear cost increases. This protects margins as demand shifts toward personalized orthoses.
-
Build payer-anchored value cases: Sponsor targeted clinical evidence generation that maps functional outcomes to payer-defined endpoints and coding. Early payer engagement reduces reimbursement uncertainty.
-
Pursue selective M&A: Identify regional orthotics providers and component suppliers that provide distribution density or proprietary components. Use roll-up playbooks to accelerate scale while preserving clinical expertise at the point of care.
-
Operationalize compliance: Standardize documentation workflows and audit trails to satisfy DMEPOS fraud-prevention requirements. This reduces payment disruption risk and supports faster collections.
-
De-risk regulatory pathways: Integrate regulatory strategy into earliest product development stages, selecting 510(k) predicates and evidence packages that minimize uncertainty and preserve label claims aligned with commercial messaging.
Scenario planning and risk considerations
Our stress-tested scenarios model the impact of three macro risks on revenue and margin: a significant reimbursement constriction in a major market, a disruptive lower-cost entrant leveraging additive manufacturing at scale, and accelerated clinical evidence requirements from payers. Each scenario includes recommended tactical responses (pricing flexibility, channel rebalancing, contingency M&A) and threshold triggers for escalation.
Conclusion — the strategic value of the full report
The high-level picture is clear: orthopedic orthotics is a resilient, mid-growth market with attractive pockets for innovation-led expansion, but success in 2026 hinges on integrating clinical evidence, regulatory foresight, and payer-aware commercial execution. PW Consulting’s full study provides the granular segmentation, supplier-level economics, and executable playbooks required to convert market opportunity into sustained competitive advantage.
To preserve actionable differentiation for our subscribers, we have intentionally withheld detailed regional, product-type, and application-level splits from this primer. The comprehensive report contains those segment-level forecasts, market share tables, downloadable financial models, and step-by-step implementation guides that executives and corporate development teams need to act in 2026. Contact PW Consulting to access the full dataset and tailored advisory support.
For detailed analysis of this topic, please visit the official page: Orthopedic Orthotics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cyanuric Acid Market to Reach USD 380 Million in 2025 at 5.5% CAGR
By pmarketresearch, 2026-07-09
Cyanuric Acid Market 2026: Strategic Preview for Corporate Decision-Makers
Executive snapshot
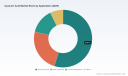
As firms prepare their 2026 strategic plans, cyanuric acid is re-emerging as a high-visibility specialty chemical whose market trajectory combines steady demand growth with episodic supply risk. PW Consulting’s upcoming Cyanuric Acid Market study synthesizes a seven-year forecast (2026–2032) anchored to historical performance (2020–2025, base year 2025) and quantifies a compound annual growth rate (CAGR) of 5.5% for the forecast interval. The broader market, valued at approximately USD 380 Million in 2025, continues on a recovery and expansion path, with modelled topline outcomes reaching the mid-hundreds by the end of the forecast window.
Cyanuric Acid Market
Why this matters for 2026 planning
Procurement, manufacturing, commercial and corporate development leaders must treat cyanuric acid as more than a commodity: it sits at the intersection of consumer-driven swimming pool maintenance, municipal and industrial water treatment, and several niche industrial chemistries. The market’s steady CAGR masks finer-grain volatility driven by supply-chain incidents, regulatory enforcement, and shifts in application demand. For 2026, decisions on capacity investment, contract length for offtake agreements, hedging strategies, and M&A prioritization should be informed by three realities that our study explores in depth:
Cyanuric Acid Market
- Structural growth coupled with episodic shocks: baseline demand grows at a mid-single-digit pace, but short-term dislocations can create outsized pricing and availability effects.
- Consolidation pressure: market concentration metrics indicate a modestly concentrated supplier base, which influences negotiation dynamics and strategic options for buyers and potential entrants.
- Regulatory and supply-side complexity: legacy incidents and regulatory actions continue to create tail risks that merit operational contingencies.
Market trajectory: headline figures and what they imply
PW Consulting’s topline model records the market at roughly USD 380 Million in the 2025 base year and applies a 5.5% CAGR across 2026–2032 to map out plausible upper- and lower-bound scenarios. That trajectory signifies durable end-market demand for the chemical, while also providing a quantitative foundation for stress-testing capex and commercial scenarios. In absolute terms, our forecast horizon projects steady expansion with intermittent dips and rebounds aligned to supply events and investment cycles—patterns that are commonplace in specialty chemical segments.
Cyanuric Acid Market
Dynamics and risk drivers
Our Dynamics section dissects the twin drivers of cyanuric acid markets: demand-side evolution (end-use preferences, seasonal consumption patterns, and water-treatment standards) and supply-side constraints (feedstock availability, plant uptime, and concentration of production). Notable inputs include documented supply disruptions: for example, historical force majeure declarations tied to production facilities have repeatedly shown how localized damage can ripple through global availability and commercial terms. Regulatory and trade developments, including post-incident enforcement and trade remediation, are integrated into the scenario suite to quantify contagion effects on price and availability.
Segmentation architecture (high-level)
The market naturally breaks down across product forms, applications and geographies. Our study models demand across granular, powdered and liquid product forms; across primary application clusters such as swimming pools and industrial/water-treatment uses; and across global regional demand centers. As a strategic preview, we deliberately showcase the segmentation framework and its strategic implications, while preserving the report’s proprietary granularity—core split figures and specific regional/application breakdowns are reserved for the full report to support client-level decisioning.
Competitive landscape — what you need to know
The supply side is characterized by a concentrated leading cohort and several mid-tier producers. Market concentration metrics in our analysis indicate that the top three producers account for a substantial portion of total market volume, and the top five capture a material majority—conditions that shape bargaining power, price pass-through and consolidation potential.
- Shandong Wolan Biology Co., Ltd. (Juancheng County, Shandong Province, China) — A producer with direct, commercially-oriented offerings in the cyanuric acid space. Their product portfolio, along with distribution networks, positions them as a decisive regional supplier for Asia-focused buyers and as a competitor for exports into other geographies.
- Hebei Jiheng Chemical Co., Ltd. (Wuyi County, Hengshui City, Hebei Province, China) — Maintains a strong domestic foothold with capabilities tailored to cyanuric acid production. The company is relevant for buyers assessing midstream partnerships or seeking reliable contract manufacturing capacity.
- Shandong Xingda Chemical Co., Ltd. (Yucheng, Dezhou, Shandong Province, China) — A vertically integrated manufacturer with a portfolio that includes cyanuric acid offerings; their integration profile matters for buyers evaluating supply security and cost structure.
- Shandong Mingda Chemical Technology Co., Ltd. (Chiping County, Liaocheng City, Shandong Province, China) — Competes on product availability and cost competitiveness, with a footprint that emphasizes regional logistics and production scale.
Each of these firms is profiled in the full report with operational footprints, go-to-market strategies, capacity posture, and directional intelligence on commercial terms. For buyers and investors, the combination of concentration metrics and supplier profiles creates definable strategic options: secure flexible long-term contracts with incumbent majors, vertically integrate through tolling or JV structures, or target bolt-on acquisitions among well-positioned mid-tier manufacturers.
Practical, actionable content in the PW Consulting report
The full Cyanuric Acid Market study goes beyond market sizing and competitor lists to deliver operationally relevant outputs designed for 2026 decision cycles:
- Dynamic scenario models that let you toggle supply-shock severity, demand elasticity, and price pass-through to quantify NPV and margin outcomes under alternate assumptions.
- Vendor due-diligence templates for procurement teams to standardize RFPs, SLAs and risk clauses specific to cyanuric acid supply.
- An M&A playbook identifying target archetypes, valuation heuristics and integration risks unique to specialty chemical acquisitions in this space.
- Regulatory monitoring maps that translate historical incidents and enforcement actions into forward-looking compliance checklists.
- Commercial intelligence dashboards summarizing price trends, volatility indices and inventory-to-sales staging calibrated for procurement and treasurer use.
Strategic implications and recommended actions for 2026
PW Consulting’s recommendations are targeted at three audiences—producers, buyers (including pool-chemical distributors and municipal/industrial procurement), and private-equity investors—and reflect a balance between growth capture and risk mitigation:
- For producers: Prioritize flexible capacity and dual-sourcing pathways. Consider staged debottlenecking investments and strategic tolling agreements to capture upside without overcommitting capital under near-term uncertainty.
- For buyers: Move from spot-heavy to hybrid contracting (mix of indexed short-term purchases and longer-term capacity bookings). Build inventory buffers sized to modeled disruption scenarios and use our vendor due-diligence templates to harden supply agreements.
- For investors: Target assets with clear feedstock differentiation, proximity to key demand centers, or acquisition targets that can be integrated to create scale in a moderately concentrated market—prioritizing operational resilience over aggressive geographic arbitrage.
Risk management checklist for 2026 execution
Every strategy should be accompanied by a practical risk checklist. Key items we recommend embedding into 2026 plans include:
- Supply contingency playbooks that specify alternate feedstocks, tolling partners and logistics routes.
- Regulatory surveillance routines to detect changes in water-treatment regulation and trade policy that can affect imports/exports.
- Working-capital scenarios that align payment terms with volatility regimes and contractual protections against force majeure events.
- Product-mix optimization to shift flows between product forms (granular, powdered, liquid) according to seasonality and margin dynamics.
What we intentionally withhold — and why
Consistent with PW Consulting’s “trailer” approach, this preview demonstrates our methodological depth and delivers the strategic implications decision-makers need to evaluate. To preserve the commercial integrity of the analysis and to provide maximum value to subscribers, specific sub-segment figures, detailed regional/application splits, and client-ready proprietary tables are exclusive to the full report and its accompanying data workbook. Those assets enable precise negotiations, transaction modeling and operational changes—making them essential for teams executing in 2026.
Next steps
For leaders preparing budgets, negotiating supplier terms, evaluating acquisitions, or stress-testing operations for 2026, our Cyanuric Acid Market study provides the quantitative backbone and the practical tooling required for confident action. Access to the full dataset, supplier profiles with validated URLs, scenario models and execution templates is available through PW Consulting’s report portal. Engage with our team to commission customized variants of the model scoped to your supply chain, geographies, or transaction thesis.
PW Consulting is ready to support decision-makers in turning market insight into executable advantage for 2026 and beyond. Visit the report page to review sample outputs and to arrange a tailored briefing.
For detailed analysis of this topic, please visit the official page: Cyanuric Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Auto Power Window Motors to hit USD 344.8M by 2032 (5.07% CAGR)
By pmarketresearch, 2026-07-09
Automotive Power Window Motor Market — Strategic Intelligence for 2026 Decision-Makers
Executive preview
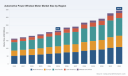
As automotive OEMs and tier suppliers map product roadmaps and procurement strategies for 2026, the Automotive Power Window Motor market presents a clear, measurable growth story — but one that conceals important tactical inflection points beneath an otherwise steady headline. PW Consulting’s market model shows a market that grew from roughly USD 163 million in 2020 to about USD 215 million in 2025, and is forecast to continue expanding at a compound annual growth rate of c.5.07% into the 2026–2032 horizon, reaching roughly USD 345 million by 2032. For executives evaluating manufacturing investments, supplier partnerships, or M&A opportunities in 2026, the opportunity is sizable — and the competitive and regulatory terrain requires deliberate, early action.
Automotive Power Window Motor Market
Why this study matters for 2026 planning
- It translates macro momentum (vehicle content growth, safety regulation, and incremental feature adoption) into discrete opportunities for product, procurement, and R&D roadmaps.
- It combines a forward-looking quantitative model with pragmatic playbooks for supplier evaluation, cost sensitivity testing, and compliance readiness — the tactical inputs that accelerate boardroom decisions into executable programs.
- It surfaces mid-cycle risks — from material cost volatility to regulation-driven requalification — that can shift 2026 budgets and supplier strategies if not anticipated.
Market trajectory and practical inflection points
The market’s historical arc (USD ~163M in 2020 to USD ~215M in 2025) reflects steady demand for powered convenience and safety functions in passenger vehicles. The near-term step to approximately USD 234M in 2026 embedded in our base-case model is driven primarily by continued refresh cycles in light vehicle platforms, incremental electronic content per vehicle (anti-pinch sensors, integrated control electronics), and rising adoption of brushless motor architectures in mid- and premium segments.
Automotive Power Window Motor Market
From a strategic planning perspective, the c.5.07% CAGR projected across 2026–2032 is meaningful: it signals an expanding addressable market large enough to justify targeted capacity additions, but not so concentrated that scale alone delivers guaranteed margin. Decision-makers must therefore balance investments in differentiated technology (electronics, sensors, lightweighting) with disciplined cost management and a focused go-to-market strategy.
Automotive Power Window Motor Market
Structural dynamics: fragmentation, profit pools and product migration
The market’s competitive structure is not a classic winner-takes-most oligopoly. Measured concentration metrics show that the top three and top five suppliers capture modest shares of the total market, which implies a fragmented vendor landscape and multiple viable partners for OEMs and tier-one customers. For investors and corporate development teams, that fragmentation creates two parallel strategies: (1) consolidation and capability roll-ups to capture supplier economics, or (2) targeted partnerships to access specific technology modules (e.g., encoderless anti-pinch, ultra-lightweight motors).
Product migration remains a central theme. Brushless motor architectures, integrated electronics, and embedded obstruction-detection algorithms are progressively displacing legacy brushed units in new platforms — creating differentiated value propositions on reliability, NVH, and energy efficiency. Niche architectures (such as stepper-based solutions) retain relevance in specific applications where positional control matters, but the headline trend is toward fewer, higher-value modules per door system combined with smarter software-driven diagnostics.
Technology, regulations and supply-side shocks — what 2026 leaders must prioritize
- Regulatory compliance is non-negotiable. Recent technical bulletins and regulatory mandates from major jurisdictions emphasize anti-pinch and intelligent obstruction detection. These requirements influence design validation cycles, supplier qualification timelines, and warranty exposure. Expect certification and functional safety audits (ISO 26262, FMVSS/region-specific equivalents) to form a gating item for OEM approval lists.
- Electronics-enabled architectures are accelerating. Silicon and MCU suppliers are releasing application-focused motor-driver evaluation platforms that shorten development cycles for encoderless anti-pinch implementations. These enablers materially reduce integration time — but they also raise the bar for software verification and cybersecurity considerations.
- Raw material volatility is an ongoing constraint. The price of rare-earth elements used in high-efficiency motors has experienced significant upward pressure in recent periods; procurement teams must plan for input-cost sensitivity and validate alternative magnet and motor designs where feasible.
Competitive landscape — capability mapping and strategic implications
The market is populated by established global component specialists and regional champions. Each competitor brings a different mix of scale, product depth, and OEM relationships. High-level capability positions — synthesized from supplier profiles, product announcements, and recent field bulletins — shape actionable choices for 2026:
- Robert Bosch GmbH (Gerlingen, Germany): Deep systems integration capability with proven DC and brushless motor platforms and robust anti-pinch implementations — a preferred partner for OEMs seeking end-to-end regulator assemblies and global support.
- DENSO Corporation (Kariya, Japan): Focus on compact, efficiency-optimized motors with integrated electronics; strong for platforms prioritizing packaging and thermal management.
- Valeo SA (Paris, France): Early mover on brushless, modular regulator designs and anti-trap detection; well positioned for platform modularization strategies.
- Brose Fahrzeugteile SE & Co. KG (Coburg, Germany): Strength in weight-optimized drives and door-architecture integration — attractive for OEMs seeking light-weighting without sacrificing functionality.
- Mitsuba Corporation (Tokyo, Japan) & Mabuchi Motor (Matsudo, Japan): Specialists in ultra-light and high-torque motor chemistries respectively — compelling options for cost- and weight-sensitive platforms.
- Johnson Electric (Hong Kong) & Continental AG (Hannover, Germany): Offerings range from compact gearmotors to full lift lines; useful where compatibility with broader vehicle electrical architectures matters.
- Aisin Seiki (Nagoya), Lucas TVS (Chennai) and Hi-Lex (Osaka): Regional strengths, proven volume manufacturing and price-competitive assemblies — important in regionally differentiated sourcing strategies.
Recent field activity — including regulator replacement bulletins from safety agencies — underscores the commercial impact of reliability and serviceability. For 2026 sourcing strategies, suppliers with fast aftermarket response capability and clear traceability will be advantaged.
Five strategic imperatives for 2026
- Embed functional-safety and anti-pinch compliance into the earliest design gates. Treat regulation-driven features as drivers of product architecture, not add-ons.
- Prioritize brushless motor and integrated-electronics roadmaps where lifecycle cost and NVH improvements materially affect competitive win rates.
- De-risk rare-earth exposure through dual-sourcing, alternative materials R&D, and long-term purchase agreements tied to indexed pricing clauses.
- Evaluate bolt-on consolidation opportunities selectively — target suppliers that close capability gaps (electronics, software, aftermarket logistics) rather than generic scale acquisitions.
- Shorten supplier qualification cycles by leveraging vendor evaluation platforms and pre-certified subsystems; incorporate supplier performance KPIs linked to failure-mode incidence and field-service metrics.
What the full PW Consulting study delivers (practical, executable assets)
We designed the full report to be a working toolkit for 2026: not just insight, but materials you can operationalize immediately. Highlights include:
- A calibrated market model and forecast engine (2026–2032) with scenario toggles for material cost shocks, regulatory acceleration, and EV penetration — delivered as editable financial templates.
- Vendor scorecards and a capability matrix benchmarking mechanical, electrical, software, and aftermarket strengths — intended for supplier selection and RFP shortlists.
- A regulatory and test-spec matrix cross-mapped to design requirements and supplier audit checklists — to compress approval timelines.
- Supply-chain maps with pinch-point identification and hedging playbooks for magnet and semiconductor exposure.
- Go-to-market playbooks for OEMs and suppliers: product positioning, pricing levers, and aftermarket monetization strategies.
- Acquisition target screening criteria and valuation heuristics to support M&A decisions in a fragmented landscape.
Note: in keeping with the “trailer” approach here, detailed segment tables and the granular regional and application splits — which are crucial for platform-specific sourcing decisions — are reserved for the full report and the downloadable model package.
How to use this intelligence in your 2026 planning cycle
- Short-term (0–6 months): Lock regulatory and functional-safety requirements into component RFQs; qualify at least two suppliers per platform for redundancy.
- Medium-term (6–18 months): Execute targeted R&D pilots on brushless and encoderless anti-pinch solutions; validate cost trade-offs under a range of material-price scenarios.
- Long-term (18–36 months): Consider strategic partnerships or M&A to acquire embedded electronics capability or aftermarket service networks that will sustain margins as content per vehicle increases.
Final note — why PW Consulting’s market study is a strategic instrument, not just analysis
For 2026 decision-makers, the difference between a timely, profitable initiative and a stranded program is rarely about headline growth — it’s about anticipating regulatory shifts, pre-qualifying suppliers who can meet functional-safety and serviceability demands, and hardening supply contracts against material volatility. Our study turns market growth projections (from current-year baselines through 2032) into executable options: which suppliers to pilot, which technologies to prioritize, and how to structure contracts that protect margins without stalling product launch timelines.
To access the full dataset, interactive model, and supplier scorecards — including the detailed regional and application splits that underpin targeted sourcing and product decisions — visit the PW Consulting report page and request the Automotive Power Window Motor Market full report and model package.
For detailed analysis of this topic, please visit the official page: Automotive Power Window Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com