

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Chromatography Syringes Market to Reach USD 82.2M in 2025

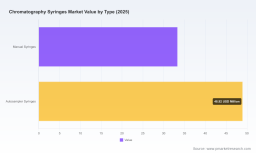
Chromatography Syringes Market: Strategic Imperatives for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present an executive preview of our newest Chromatography Syringes Market study — a practical, decision-focused briefing designed to shape boardroom choices in 2026. The market has expanded steadily over the 2020–2025 historical window and is projected to continue growing through our forecast period (2026–2032) at a compound annual growth rate of 5.6%. Measured in USD Million, the industry’s total market sizing and trajectory are core inputs to every strategic recommendation in this dossier. This preview demonstrates the analytical depth of the full study while deliberately withholding granular segment and regional splits to guide you to the complete report for transaction-grade detail.
Chromatography Syringes Market
Market trajectory: what the numbers mean for strategy
-
Momentum and scale: The market’s recovery and steady rise from the historical base demonstrates resilient demand across laboratory, pharmaceutical, and environmental testing end‑markets. Forecast growth to 2032 reflects not only baseline replacement demand but also structural shifts — automation, single‑use adoption, and traceability requirements — that increase average selling prices and per‑lab consumption.
Chromatography Syringes Market -
Fragmentation with pockets of influence: Market concentration metrics indicate a mid-level consolidation posture — leaders hold meaningful influence but buyers still see multiple credible suppliers. This creates both defensive pressures for incumbents and attack surfaces for challengers pursuing niche specialization or integrated systems plays.
Chromatography Syringes Market -
Unit economics and value capture: As labs push for higher throughput, the willingness to pay for precision, reduced carryover, and smart traceability features rises. Strategic moves that capture service and consumables revenue streams — not just one‑time hardware sales — will disproportionately lift margins in a market growing at a steady mid-single-digit CAGR.
Key demand and technology drivers
-
Automation and autosampler proliferation: Adoption of autosampler-compatible syringes is a primary structural driver. Automated platforms increase per‑instrument consumption of precision syringes and raise the bar on tolerance, durability, and compatibility.
-
Single-use preference and sterilization economics: High-throughput environments are favoring single‑use designs to eliminate cleaning cycles and cross‑contamination risk. This shifts procurement from capital expenditure (reusable syringes plus cleaning) to ongoing consumable spend.
-
Regulatory and materials pressures: Global regulations (including REACH, RoHS) and stringent laboratory certification requirements (FDA expectations, ISO 11040 series) are raising the technical bar for materials selection, testing protocols, and traceability. Non-compliance risks are now commercial risks.
-
Sustainability trade-offs: Buyers face a trade-off between single‑use convenience and material sustainability. Companies that reconcile eco‑design with single‑use economics — for example through bio‑based polymers, take‑back programs, or lifecycle carbon accounting — will win preferential access to certain buyers and tenders.
What the full PW Consulting report delivers (practical content for 2026 planning)
-
Validated market sizing and forecast models (2020–2032) with scenario variants to stress‑test your 2026 plans.
-
Demand-driver mapping and use‑case prioritization to align R&D and sales targets with highest-value applications.
-
Competitive benchmarking: capability matrices, technology roadmaps, product portfolios, and go‑to‑market positioning for the leading suppliers and credible challengers.
-
Supply‑chain and procurement playbooks, including dual‑sourcing templates, lead‑time sensitivity models, and cost to serve analyses.
-
Regulatory compliance matrix that translates REACH, RoHS, FDA guidance, and ISO 11040 requirements into actionable product design and validation checkpoints.
-
M&A and partnership heatmaps: likelihood-of-success scoring for bolt‑on acquisitions and co‑development alliances, complete with valuation sensitives and integration risk flags.
-
Commercial execution toolkit: pricing levers, contract templates, service bundling strategies, and commercial KPIs calibrated to the market’s growth trajectory.
-
Interactive Excel models and slide decks that executives can use in 2026 budget rounds, investor presentations, and due‑diligence processes.
Competitive landscape — who matters and why
The competitive set includes global instrument and consumable specialists, each offering differentiated strengths that matter for strategic decision-making:
-
Hamilton Company (Reno, NV): Known for precision HPLC and GC syringes — both autosampler and manual — with advanced plunger technologies to minimize carryover and maximize chemical resistance.
-
Agilent Technologies (Santa Clara, CA): Supplier of autosampler syringes and needles optimized for high‑throughput automated platforms; recent strategic moves emphasize integrated systems development.
-
Thermo Fisher Scientific (Waltham, MA): Offers gas‑tight and fixed‑needle options with digital traceability features for reproducible injections in regulated labs.
-
Shimadzu Corporation (Kyoto, Japan): Supplies both manual and autosampler syringes with a focus on durability and optical clarity for chromatography workflows.
-
Restek / SGE Analytical Science (Bellefonte, PA & Ringwood, Australia): Specialist precision syringes and cross‑brand compatibility for diverse instrument ecosystems.
-
VICI AG International (Schenkon, Switzerland): Focused on integrated syringe systems and components that enable automation OEMs and integrators.
-
Gilson, PerkinElmer and other analytical vendors: Provide complementary product lines and distribution reach important for route‑to‑market strategies.
Recent industry moves underscore strategic direction: a major acquisition expanded one OEM’s consumables portfolio in 2024, while a strategic partnership between a leading instrument vendor and syringe systems specialist signals acceleration toward integrated automation solutions. These events illustrate two viable competitive playbooks — horizontal consolidation to own consumables, and vertical integration through systems partnerships.
Practical strategic implications for 2026 decision-makers
-
Prioritize autosampler and automation-compatible SKUs in product roadmaps. The combination of higher throughput and willingness to pay for reliability means faster revenue uplift and stickier procurement relationships.
-
Invest in traceability and digital features. Smart identification and reproducibility capabilities reduce customer risk and justify premium pricing, particularly for regulated pharmaceutical and clinical lab customers.
-
Build a compliance-first product design process. Translate REACH / RoHS and ISO 11040 test requirements into documented design gates to speed customer qualification and reduce costly rework during audits.
-
Scale single‑use manufacturing capacity while designing sustainability offsets. Single‑use will dominate many high‑throughput workflows, but buyers increasingly select suppliers who can present credible lifecycle and recycling strategies.
-
Pursue selective M&A and partnerships. Given market concentration metrics, bolt‑on acquisitions that add automation compatibility, materials expertise, or service capabilities are likely to deliver the best ROI vs. broad horizontal consolidation.
-
Secure supply chains proactively. Dual‑sourcing of critical materials and nearshoring where feasible will be decisive in avoiding disruptions that ripple into customer relationships.
-
Monetize services. Field calibration, validation support, and consumable subscription bundles increase lifetime value and smooth revenue seasonality.
How to use this preview in your 2026 planning cycle
-
Board and executive teams: use our scenario models to stress‑test capital allocation between manufacturing scale‑up, R&D for smart syringes, and M&A options.
-
Product and R&D leaders: adopt the regulatory matrix and materials checklist as immediate inputs into 2026 design sprints and product validation timelines.
-
Commercial and procurement teams: apply our pricing levers and customer segmentation playbooks to 2026 tender and contract negotiations.
-
Corporate development: leverage the M&A heatmap and integration playbooks to prioritize targets and to build rapid diligence pipelines.
Note: this preview intentionally omits granular region and application split figures to preserve the strategic lead contained in our full dataset. The complete PW Consulting report unlocks transaction‑grade detail — including regional demand curves, application-level consumption, SKU-level pricing benchmarks, supplier share matrices, and downloadable financial models — to directly support M&A, procurement, and product roadmap decisions in 2026.
Next steps
For teams preparing budgets, vendor negotiations, or M&A pipelines in 2026, the full report provides the actionable datasets and templates required to convert insight into execution. Access the complete dossier to obtain the granular splits, interactive models, and supplier scorecards that will materially de‑risk and accelerate your 2026 plans.
For detailed analysis of this topic, please visit the official page: Chromatography Syringes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com