

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Surround-View Market to Reach USD 344.8 Million by 2032 (14.51% CAGR)

Automotive Surround-View Systems Market: Strategic Imperatives for 2026 Decision‑Makers
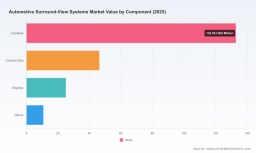
As vehicle architectures accelerate toward higher levels of driver assistance and electrified platforms, surround‑view systems have transitioned from niche convenience features to foundational perception layers for parking, low‑speed autonomy and urban maneuvering. PW Consulting’s latest market study—anchored on a 2025 base year and a 2026–2032 forecast window—captures this transition with a data‑driven narrative: the global market surpassed USD 215 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 14.51% through the forecast period, reaching an estimated USD 345 Million by 2032. For executives setting 2026 priorities, this trajectory demands a recalibration of product, supply chain and partnership strategies to capture value in a maturing yet fast‑growing segment.
Automotive Surround-View Systems Market
Why this study matters for 2026 strategic decisions
- Timing of investment matters: With the market growing at a double‑digit pace, investments initiated in 2026 will determine whether companies secure design wins that compound over the next seven years. The study identifies which technology bets are likely to be de‑risked by 2028 and which will remain optional equipment well into the next decade.
- Architecture choices are value multipliers: OEMs and Tier‑1s that adopt modular, software‑defined surround‑view architectures—capable of integrating AI preprocessing and scalable ECU horsepower—can capture a higher value share than those retaining monolithic, hardware‑centric approaches.
- Regulatory alignment is non‑negotiable: Compliance expectations (UNECE R79, FMVSS 111, IATF 16949 and relevant imaging hardware standards such as ISO 11201) are tightening validation timelines. The report maps these regulatory inflection points to program milestones so engineering, quality and procurement teams can avoid late‑stage design rework.
What the report delivers: actionable intelligence, not academic theory
PW Consulting’s report is designed for commercial and product leaders who must translate macro growth into executable plans. Rather than presenting broad strokes, the study provides:
Automotive Surround-View Systems Market
- Scenario‑based demand forecasts that link penetration curves to vehicle production ramps, option take‑rates and aftermarket/retrofit channels—enabling revenue‑backed business cases for 2026 capital allocations.
- Technology roadmaps that compare imaging sensors, lens families, fusion strategies and AI‑assisted perception stacks—highlighting migration paths from 2D stitched views to 3D/semantic surround perception.
- Supplier and OEM playbooks: procurement scorecards, qualification checklists and commercial negotiation levers tailored for both Tier‑1 supply agreements and strategic minority investments.
- Integration blueprints—hardware, middleware and over‑the‑air software update considerations—to shorten time‑to‑market for new variants and to control total cost of ownership across vehicle fleets.
- A focused risk register covering technical, regulatory, supply and competitive risks with mitigation guidance calibrated to common program timelines (concept, validation, ramp, sustainment).
The report purposefully refrains from publishing sensitive segmentation tables within the executive summary: detailed regional, application and component splits are available in the full study, where readers can interact with scenario toggles and download granular matrices for their internal planning tools.
Automotive Surround-View Systems Market
Competitive landscape: who leads, why it matters
The surround‑view market demonstrates moderate concentration: the top three global suppliers account for roughly 62% of market value, while the top five hold about 65%. This concentration reflects a winner‑takes‑most dynamic on large OEM programs, but it also hides a layer of niche innovation and fast‑moving start‑ups that can influence feature roadmaps. Our competitive analysis focuses on strategic positioning rather than raw share numbers, profiling the capabilities that matter for 2026 program decisions.
- Continental AG (Hanover, Germany) — Known for its ProViu 360 platform, Continental combines 3D imaging with AI‑enhanced object detection targeted at parking assistance and close‑range safety. Their strength lies in system integration and broad OEM relationships that ease program adoption for safety‑critical applications.
- Valeo SA (Paris, France) — Valeo’s surround‑view portfolio emphasizes 360° visibility and human‑machine interface convenience. They compete on packaged solutions that reduce OEM integration effort and are often positioned as upgrade paths for mid‑segment vehicle lines.
- Magna International Inc. (Aurora, Canada) — Magna focuses on 3D surround systems paired with electronic control units (ECUs), offering end‑to‑end subsystems that can be configured for blind‑spot monitoring and parking automation. Their strength is in manufacturing scale and flexible vehicle integration capabilities.
- Aptiv PLC (Schaffhausen, Switzerland) — Aptiv’s strategy centers on ADAS‑integrated platforms and multi‑camera arrays designed to feed perception stacks for higher‑level driver assistance. Their offerings appeal to OEMs aiming to harmonize surround view with broader sensing strategies.
- Robert Bosch GmbH (Gerlingen, Germany) — Bosch markets second‑generation 360° camera systems focused on robust video‑based object detection and reliability in diverse environmental conditions. Their engineering advantage is long experience in automotive safety systems and rigorous validation processes.
- Denso Corporation (Kariya, Japan) — Denso delivers camera modules integrated into platform architectures, aiming for efficiency in production and predictable performance across vehicle variants. They are a preferred partner where tight supplier vehicle integration is a priority.
Each of these players pursues a distinct mix of vertical integration, modularity and software capabilities. The full report contains a supplier matrix that cross‑references these strategic dimensions against OEM program needs and validates potential partner fit for 2026 procurement cycles.
Technology and validation dynamics shaping procurement
- AI and edge analytics: Recent vendor integrations—such as Renesas’s addition of AI‑supported imaging analytics into surround monitoring platforms—have demonstrated measurable safety improvements (reported collision prevention gains on the order of a third in certain implementations). These capabilities shift system value from raw sensor count to perception quality and compute efficiency.
- Hardware‑software co‑design: Commodity camera sensors are increasingly commoditized; differentiation comes from firmware, calibration tools and perception middleware. Suppliers who provide validated OTA update paths and continuous learning pipelines will command premium positions.
- Standards and test regimes: Compliance with UNECE and FMVSS requirements, IATF quality regimes and electromagnetic/noise standards (e.g., ISO 11201 for imaging hardware noise emission) translates into discrete program tasks: documented validation plans, calibration traceability and production quality gates. Our report maps these obligations to development milestones to avoid costly late changes.
Strategic playbook for 2026
Based on the market trajectory and competitive dynamics, PW Consulting recommends a focused set of actions for 2026 decision‑makers:
- Decide architecture by Q2 2026: Commit to either a modular, software‑centric platform or a vertically integrated ECU‑centric approach. Late reversals are expensive; our breakeven analyses show when one choice dominates depending on anticipated option take‑rates and software monetization plans.
- Prioritize perception quality over camera count: Early investments in AI preprocessing and sensor fusion can reduce total system cost while improving detected object fidelity—critical for urban environments and fleet use cases.
- Lock in supply‑chain flex: Negotiate multi‑source options for critical camera modules and secure long‑lead sensors to mitigate node‑level shortages. Use supplier scorecards and KPIs from our study to structure earn‑outs and quality incentives.
- Embed regulatory signoffs in program gates: For OEMs targeting global launches, validate against UNECE, FMVSS and IATF checkpoints within design‑freeze windows to prevent costly requalification.
- Plan software monetization and lifecycle economics: Build OTA delivery and feature‑tiering into the first production release to enable post‑launch revenue streams and iterative safety improvements.
How to use this report in boardroom decisions
Boards and executive teams should treat the surround‑view market as a strategic enabler of broader ADAS and autonomy roadmaps rather than a discrete feature line item. The study provides the financial templates, supplier comparison tools and regulatory mapping required to translate product roadmaps into capital allocation decisions, M&A screening criteria and partnership frameworks. For CFOs, the report includes sensitivity matrices that quantify how option take‑rates and component cost declines impact program IRR across the 2026–2032 window; for CTOs, there are fast‑track integration checklists and validation sequences aligned to industry standards.
Next steps: where to find the granular intelligence
This introduction outlines the high‑level strategic implications and competitive dynamics crucial to 2026 decision cycles. PW Consulting’s full Automotive Surround‑View Systems Market report contains the granular matrices, interactive scenario models and supplier scorecards required to operationalize these insights—including regional penetration forecasts, component-level cost curves, and OEM program matchup tables. Accessing the complete study will equip your team with the actionable artifacts to win design‑ins, structure supplier contracts and optimize your product roadmap in a market growing at ~14.5% annually.
For teams preparing 2026 budgets and product roadmaps, the timing to act is now: the market’s growth profile rewards early clarity on architecture, supplier partners and regulatory sequencing. PW Consulting’s full report delivers the precise, operational intelligence you need to convert that clarity into competitive advantage.
For detailed analysis of this topic, please visit the official page: Automotive Surround-View Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com