

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Insight: Dry Film Market to Reach USD 1,744.04M by 2032 at 6.5% CAGR

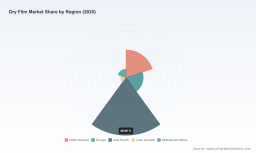
Dry Film Market: Strategic Intelligence for 2026 Decisions
As PW Consulting’s Lead Industry Analyst, I present a concise, decision-focused brief that frames the strategic value of our forthcoming Dry Film Market study for executives planning 2026 horizons. The dry film sector—spanning photoresists, solder masks, and solid-film lubricants—has returned to sustained growth after pandemic-era adjustments and is poised to meaningfully re-shape supplier strategies, capital allocation, and product roadmaps into the early 2030s. Our analysis synthesizes historical performance (2020–2025), forward-looking scenarios (2026–2032), and actionable intelligence to help leaders convert market movement into competitive advantage.
Dry Film Market
Why this study matters for 2026
-
Macro clarity in an uncertain cycle: The overall dry film market has expanded from a mid-single-hundred million baseline in 2020 to an estimated USD 1.115 billion in our 2025 base year. Under a 6.5% CAGR projection, the market trajectory through 2032 reveals material upside for firms that time investments and partnerships effectively.
Dry Film Market -
Concentration shapes strategy: With industry concentration materially favoring a small set of established suppliers, competitive moves by top vendors (product launches, capacity additions, formulation upgrades) can rapidly alter access to advanced materials and premium margins. Our report quantifies concentration metrics and models their implications on supplier bargaining power.
Dry Film Market -
Regulatory and material inflection points: New PFAS-free formulations, stricter aerospace/military specs, and volatile feedstock costs are raising the operational bar—forcing C-suite tradeoffs between short-term margin protection and longer-term compliance-driven differentiation.
What you’ll gain from the full study (high-level)
-
Actionable market-sizing and trend scaffolding: We provide a transparent top-down market model anchored to 2025 as the base year, with scenario runs that capture demand elasticity, price pass-through, and technology substitution through 2032.
-
Scenario-driven capacity planning: Practical tools to evaluate when to expand, delay, or outsource production—incorporating lead times for specialty coating lines, formulation qualification, and customer requalification cycles common in PCB and aerospace programs.
-
Supply-chain stress-testing: A modular heat-map that links raw-material volatility—polymers, photoinitiators, specialty additives—to margin compression under different procurement strategies and hedge positions.
-
Regulatory readiness playbook: Stepwise requirements for PFAS alternatives, MIL-spec approvals, and IPC standard compliance—plus a timeline matrix showing typical qualification durations across defense and commercial OEMs.
-
Commercial playbooks: Go-to-market approaches tailored to high-density IC packaging, rigid-flex PCB customers, and aerospace prime contractors—covering value-based pricing, co-development structures, and distributor partnerships.
-
M&A and partnership diagnostics: A checklist and valuation overlays that highlight when bolt-on acquisitions or manufacturing alliances produce the highest risk-adjusted returns.
Competitive landscape—who moves markets
The sector is anchored by several companies whose recent moves and product portfolios materially influence supplier selection, technical availability, and pricing dynamics. Below I summarize the strategic posture of ten key players we scrutinize in depth in the full report. These company sketches are paired with implications—not raw financials or segment-level shares—to help executives prioritize engagement.
-
Taiyo America (San Diego) : Focused on high-resolution solder mask solutions for flexible and ultra-fine-line PCBs. Their FLEXFINER launch (Aug 2025) signals an offensive into tight-registration flexible substrate niches—areas where design-to-manufacturing alignment yields premium pricing and long qualification cycles. Strategic implication: suppliers of advanced flex substrates and contract manufacturers must evaluate Taiyo’s offering for potential co-development or lock-in risk.
-
DuPont de Nemours, Inc. (Wilmington) : Offers a broad Riston portfolio addressing advanced PCB and semiconductor patterning requirements. As a legacy materials player, DuPont’s strength is integrated chemistry plus global qualification reach—making them a default partner for OEMs migrating to higher-density patterning. Strategic implication: incumbents and challengers should model DuPont’s pricing and channel influence when planning market entry.
-
Eternal Materials (Taichung) : Recently approved capacity expansion (Jan 2025) for photoresists, solder masks and polyimide lines. Their investment reflects anticipated demand from regional EMS and semiconductor packaging customers. Strategic implication: regional supply resilience and lead-time containment will increasingly be a competitive lever in APAC-heavy supply chains.
-
Showa Denko Materials (Tokyo) : Emphasizes photoimageable solder masks and photoresist formulations suited to precision boards. Their product depth supports customers requiring tight process windows and repeatable yields. Strategic implication: OEMs with high-fidelity manufacturing requirements should prioritize multi-source strategies to mitigate single-supplier disruptions.
-
Kolon Industries (Seoul) : Markets Trumask photoresist and solder mask lines with an eye on integration with substrate makers. Strategic implication: substrate-material integration can shorten qualification timelines for new board designs but raises switching costs—an important factor for contract electronics manufacturers.
-
Curtiss-Wright Corporation (Charlotte) : Supplies solid-film lubricants (Everlube, Ecoalube) targeted at aerospace/high-temperature industrial use. Product updates (Jan 2024) show continued demand for high-performance, high-temperature lubricants. Strategic implication: prime contractors and Tier-1 suppliers must balance longer relubrication intervals promised by these materials against higher unit costs and qualification effort.
-
Tiodize (Huntsville) and Sandstrom Products (Port Byron) : Both provide military-grade solid film lubricants—emphasizing precision aerospace application and military-spec compliance. Strategic implication: defense supply chains remain a core, high-margin vertical that rewards deep process knowledge and compliance infrastructure.
-
MacDermid Alpha Electronics Solutions (Waterbury) : Offers adhesion promoters and integration services—an important bridge product that reduces defect rates for advanced solder masks and photoresists. Strategic implication: value-added services and formulation integration are potent differentiation routes for mid-sized suppliers.
-
Agfa-Gevaert Group (Mortsel) : Known for precision dry film photoresists and solder masks for both PCB and semiconductor markets. Strategic implication: European customers seeking geographically diversified supply options consider players like Agfa to manage regional regulatory and logistics risks.
Key market dynamics shaping 2026 choices
-
Raw material volatility: Polymer and specialty chemical price swings are a recurring margin risk. We model multiple procurement responses—multi-sourcing, strategic stockpiles, tolling partnerships—and quantify break-even points for each.
-
Regulatory pivot to PFAS-free and ceramic-based chemistries: New PFAS-free formulations and ceramic-based lubricants are being introduced, and while they often carry a price premium, they reduce regulatory and reputational risk. Our assessment maps which customer segments will pay premiums and the expected payback timelines.
-
Standards and qualification timelines: Military and aerospace standards plus IPC updates are extending qualification lead times for novel formulations. We estimate typical requalification windows and the operational impacts on inventory and production scheduling.
-
Concentration and bargaining dynamics: The market’s top-tier suppliers control a meaningful share of advanced formulations. That concentration creates both barrier effects for challengers and opportunity windows for niche players serving specialized applications.
Practical takeaways and recommended 2026 actions
-
Run an immediate supplier resilience stress-test: Map single points of failure in feedstock and specialty chemical supply chains and stress-test procurement strategies against 6–12 month price shock scenarios.
-
Prioritize PFAS-free roadmap and defense-spec compliance: If you serve aerospace, defense, or regulated industrial clients, accelerate qualification programs today—delays add materially to TTM and can cede share to qualified incumbents.
-
Evaluate selective capacity vs. partnership: For firms considering expansion, use scenario models (available in our report) to compare greenfield, tolling, or JV options under low, base, and high demand cases.
-
Consider M&A and tech licensing as fast-follow moves: Given concentration, acquiring niche formulation expertise or licensing specialized chemistries can shorten time-to-market with lower capital outlay than building internal R&D/production capabilities.
-
Adopt a differentiated commercial playbook: For customers in HDI, rigid-flex, or semiconductor packaging, pair materials with process support and qualification services to command premium margins and lock-in higher lifetime value.
What we intentionally withhold here—and why
In line with our “trailer” principle, this brief highlights the frameworks, competitive context, and tactical implications you need to decide whether to act in 2026. Detailed segmentation tables, granular regional/application revenue splits, full company revenue share models, and downloadable valuation spreadsheets are reserved for the full PW Consulting Dry Film Market report. Those proprietary deliverables contain the calibrated assumptions, excel models, and supplier scorecards executives need for board-level approval of capital and procurement plans.
Next steps
If your 2026 planning requires prioritized supplier lists, go/no-go qualification timelines, or a custom scenario run on capacity or pricing, contact PW Consulting to license the full report or commission a tailored engagement. The macro picture is clear: the dry film market is growing, concentrated, and subject to regulatory and raw-material inflection points that make timely, informed action both high-value and urgent.
For detailed analysis of this topic, please visit the official page: Dry Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com