

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Tubular GEL Battery Market to Reach USD 1,200M in 2025, 5.83% CAGR (2026–2032)

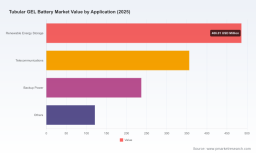
Tubular GEL Battery Market — Strategic Briefing for 2026 Decision-Makers
As energy architectures diversify and resilience becomes a board-level objective, tubular GEL batteries are re-emerging as a strategic asset class for stationary storage, telecom resilience and renewable energy integration. PW Consulting’s latest Tubular GEL Battery Market research (base year 2025; historical window 2020–2025; forecast 2026–2032) synthesizes five years of market movement and models seven years of practical scenarios. This briefing highlights the strategic value of that research for executive decision-making in 2026, outlines what the full study delivers, and previews the competitive and regulatory dynamics shaping capital allocation and commercial strategies.
Tubular GEL Battery Market
Why 2026 is an Inflection Point
The tubular GEL segment has moved from niche to core in several stationary-storage use cases. Our market model reports the global market size at roughly USD 1.2 billion in 2025 and projects a compound annual growth rate (CAGR) of 5.83% over the 2026–2032 forecast window. By 2032 the market is modeled to approach approximately USD 1.78 billion under our central scenario. Those macro dynamics reflect a combination of steady demand in legacy backup and telecom, accelerated deployment in renewable-linked storage, and selective policy-driven demand that favors longer-life, deep-cycle chemistries.
Tubular GEL Battery Market
For corporate leaders, 2026 is the year to move beyond ad-hoc procurement and to operationalize a multi-year battery strategy that aligns product roadmaps, procurement cycles and manufacturing footprints with predictable market growth and evolving regulation.
Tubular GEL Battery Market
What the Full Report Contains (Practical, Actionable Components)
- Market architecture and sizing: validated time series (2020–2025) and a detailed 2026–2032 forecast with scenario variants (base, upside, downside) and sensitivity to price, raw material shocks and regulatory shifts.
- Go-to-market playbooks: differentiated templates for OEMs, system integrators, EPCs and project developers covering pricing strategies, channel design and lifecycle service models.
- Supplier and technology scorecards: comparative assessments of manufacturing scale, quality maturity, warranty practices and after-sales service readiness.
- Commercial models: TCO and LCOE-style analyses for key use cases (utility-scale hybrid, telecom huts, distributed solar-plus-storage) with inputs you can adapt to your project or portfolio.
- Risk and resilience matrices: regulatory, supply-chain and raw materials risk scenarios with contingency plans and hedging strategies.
- M&A and partnership playbook: valuation frameworks, diligence checklists and integration templates tailored to tubular GEL providers and adjacent battery businesses.
- Field validation: case studies and commissioning reports that illustrate real-world performance and failure modes across climatic and operational settings.
Note: this briefing intentionally omits granular segmentation tables and region/application shares — the full dataset and downloadable models are available through the report portal for subscribers and validated purchasers.
Competitive Landscape — Who Matters and Why
The tubular GEL market demonstrates moderate concentration: our market concentration metrics indicate that the top three suppliers collectively hold roughly a third of market revenue, and the top five capture under half. This structure creates both opportunity and strategic risk — market leadership exists, but regional and technological niches remain contestable.
- Exide Technologies (India) — long-standing industrial supplier with deep distribution networks across industrial and telecom channels; strength lies in scale and localized service capability for large project roll-outs.
- EnerSys (United States) — global footprint with a product portfolio oriented to renewable storage and standby power; differentiates through systems integration and warranty structures that appeal to enterprise and utility customers.
- Hoppecke Batteries (Germany) — European engineering-centric player offering OPzV tubular solutions for deep-cycle and stationary applications; positioned to capitalize on local content requirements driven by European policy.
- FIAMM Energy Technology (Italy) — niche industrial and motive-power supplier with strong OEM relationships in European and Mediterranean markets.
- Several China-headquartered firms (Leoch, Narada, Sacred Sun, Coslight, Ritar, CSBattery, BSB, Wolong, Shoto, Vision Group) — supply scale and cost competitiveness; many are increasingly active in system-level projects and global EPC partnerships.
- Microtex Energy (India) — notable for technology transfer and localized manufacturing using German technology platforms; a strategic partner for regional solar and UPS rollouts.
Recent project activity provides a useful barometer of commercial execution. In early 2026, Ritar International commissioned and connected integrated wind-solar-storage projects in Panama and Shenzhen — tangible confirmation that OPzV/tubular GEL systems are migrating from pilot to grid-connected commercial deployments. Such moves lower execution risk profiles and create referenceable performance data that accelerate procurement decisions.
Regulatory Tailwinds and Policy Noise
Two policy dynamics deserve immediate attention:
- Europe’s December 2025 Battery Booster Strategy has explicit measures that encourage localized manufacturing for tubular gel and other long-life stationary chemistries. For firms active in or entering Europe, the strategy is both an incentive and a competitive hurdle — localization commitments and compliance roadmaps must be integrated into any entry plan.
- India’s 2025 approval of viability gap funding (VGF) for a tranche of BESS capacity — including tubular gel solutions — materially de-risks project economics in domestic renewables integration. That funding reshapes procurement timelines and increases the attractiveness of localized suppliers with project execution capabilities.
Regulatory and market signals are not uniform: EU utility-scale deployments in 2025 were dominated by OPzV-type tubular GEL systems for a majority of new capacity in that region. Such concentration can change rapidly with shifts in ancillary services pricing, inverter strategy and policy design. The report’s policy-impact matrices help quantify these moves and their effect on procurement and manufacturing economics.
Strategic Implications for 2026 Decisions
Executives should move from passive observation to structured options analysis. Below are immediate, actionable implications drawn from our modeling and field validation.
- Procurement and inventory: lock multi-year supply agreements where price exposure is manageable, but include flexibility clauses tied to regulatory milestones and performance KPIs. For large projects, blend regional suppliers to mitigate geopolitical and logistics risk.
- Manufacturing footprint: prioritize modular, near-customer assembly over heavy upfront capital investments. The EU booster policy and India’s VGF make staged localization attractive for players with export ambitions.
- Product & warranty design: extend service portfolios — preventive maintenance, performance guarantees and second-life programs — to capture lifecycle revenue beyond cell sales and support higher total cost of ownership justification.
- M&A and partnerships: identify bolt-on targets that fill gaps in after-sales service, local certification, or EPC capability. The mid-range market concentration suggests accretive consolidation opportunities without immediate monopolistic risk.
- Project-level economics: apply the report’s TCO templates to evaluate hybridization (solar + tubular GEL) and to run sensitivities on cycle life, depth-of-discharge and warranty claims. These inputs materially change IRR and payback timelines.
- Risk management: build supply-chain resilience plans — alternate cathode/lead procurement, freight contingencies, and long-lead spares stocking — to mitigate single-source and logistic disruption exposures.
How to Use the Report in Organizational Decision Rhythms
Three use-cases where the research delivers immediate ROI:
- CapEx committees: use the central and stress-case forecasts to justify or postpone manufacturing investments; embed scenario outputs into investment memos.
- Procurement and Sourcing: deploy supplier scorecards and negotiation playbooks to secure favorable terms while preserving flexibility for regulatory or price shocks.
- Business development: leverage go-to-market templates and the competitive matrix to prioritize geographies and verticals where tubular GEL delivers differentiated value.
Closing—Why PW Consulting’s Study Matters for 2026
In 2026, tubular GEL batteries are neither a fringe option nor a homogenous commodity. They sit at the intersection of legacy reliability requirements and the modern drive for grid-edge decarbonization. Our research, grounded in a verified historical series (2020–2025), a 2025 base year, and a transparent 2026–2032 forecast framework (CAGR 5.83%), provides the practical analytics, benchmarking and playbooks needed to make defensible strategic choices.
The analysis showcased here intentionally signals our depth while reserving detailed segmentation tables, regional and application shares, and granular company financials for the full report. If your 2026 strategy depends on optimizing procurement, sizing manufacturing bets, evaluating M&A or designing warranty-backed service models in tubular GEL batteries, the full PW Consulting study contains the models and market intelligence you will need to execute with confidence.
For detailed analysis of this topic, please visit the official page: Tubular GEL Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com